SettleADebt.

FIND THE EXPLANATION

A bank balance you cannot pay: identify the loan or overdraft

Separate an installment loan, credit line, and negative deposit account before treating them as the same bank debt.

Read the complete guide →

This address preserves a dated source document behind the guide. The complete explanation covers the questions, comparisons and next steps for this subject.

If you came here to check a specific citation, open the original archive below. It includes its source dates and recorded qualifications.

Original source archive (optional)Original working documents, complete tables and revision history
About this archive

The explanation above is written for readers. These original working documents preserve the evidence trail, including technical language, dated passages and known corrections. They have not all received independent professional review. Use the marked limits before relying on a particular rule or figure.

DETAILED RESEARCH · EVIDENCE & LIMITS INCLUDED

First focused A010 component: U.S. federal overdraft opt-in and the limits of 12 CFR 1005.17

R010 · pass-01Captured 2026-10-2713 tables · 90 claim records · 18 source recordsScoped coordinator review completed

Read the evidence with its boundaries. These are saved research components, including revisions. A scoped coordinator review checks selected evidence; it does not certify every claim, a complete jurisdiction, current law or individual applicability. Dates and access limits remain attached to the records.

How to read the research →

SettleADebt R010 PASS-01

First focused A010 component: U.S. federal overdraft opt-in and the limits of 12 CFR 1005.17

Actual research-check date: October 27, 2026, America/Los_Angeles. The clock check at 22:02:18 UTC corresponds to 15:02:18 PDT on that date. Dates below distinguish publication, enactment, regulatory effectiveness, compliance triggers, and the date a source was accessed.

Research scope: Generic published federal law, official interpretations, final-rule materials, and a generic model form. No consumer, institution, account, transaction, provider, license, case record, docket, or identifier search was conducted. No form was completed or submitted. No prior report or Library material supplied a foundation. No subagents, browser control, separate research session, or local coordinator files were used.

Execution-provenance limit: Session instructions identify the model as GPT-6 Astra Pro. I cannot independently verify a chatgpt.com frontend or model-selector setting, and do not represent either as verified.

Two material source qualifications remain:

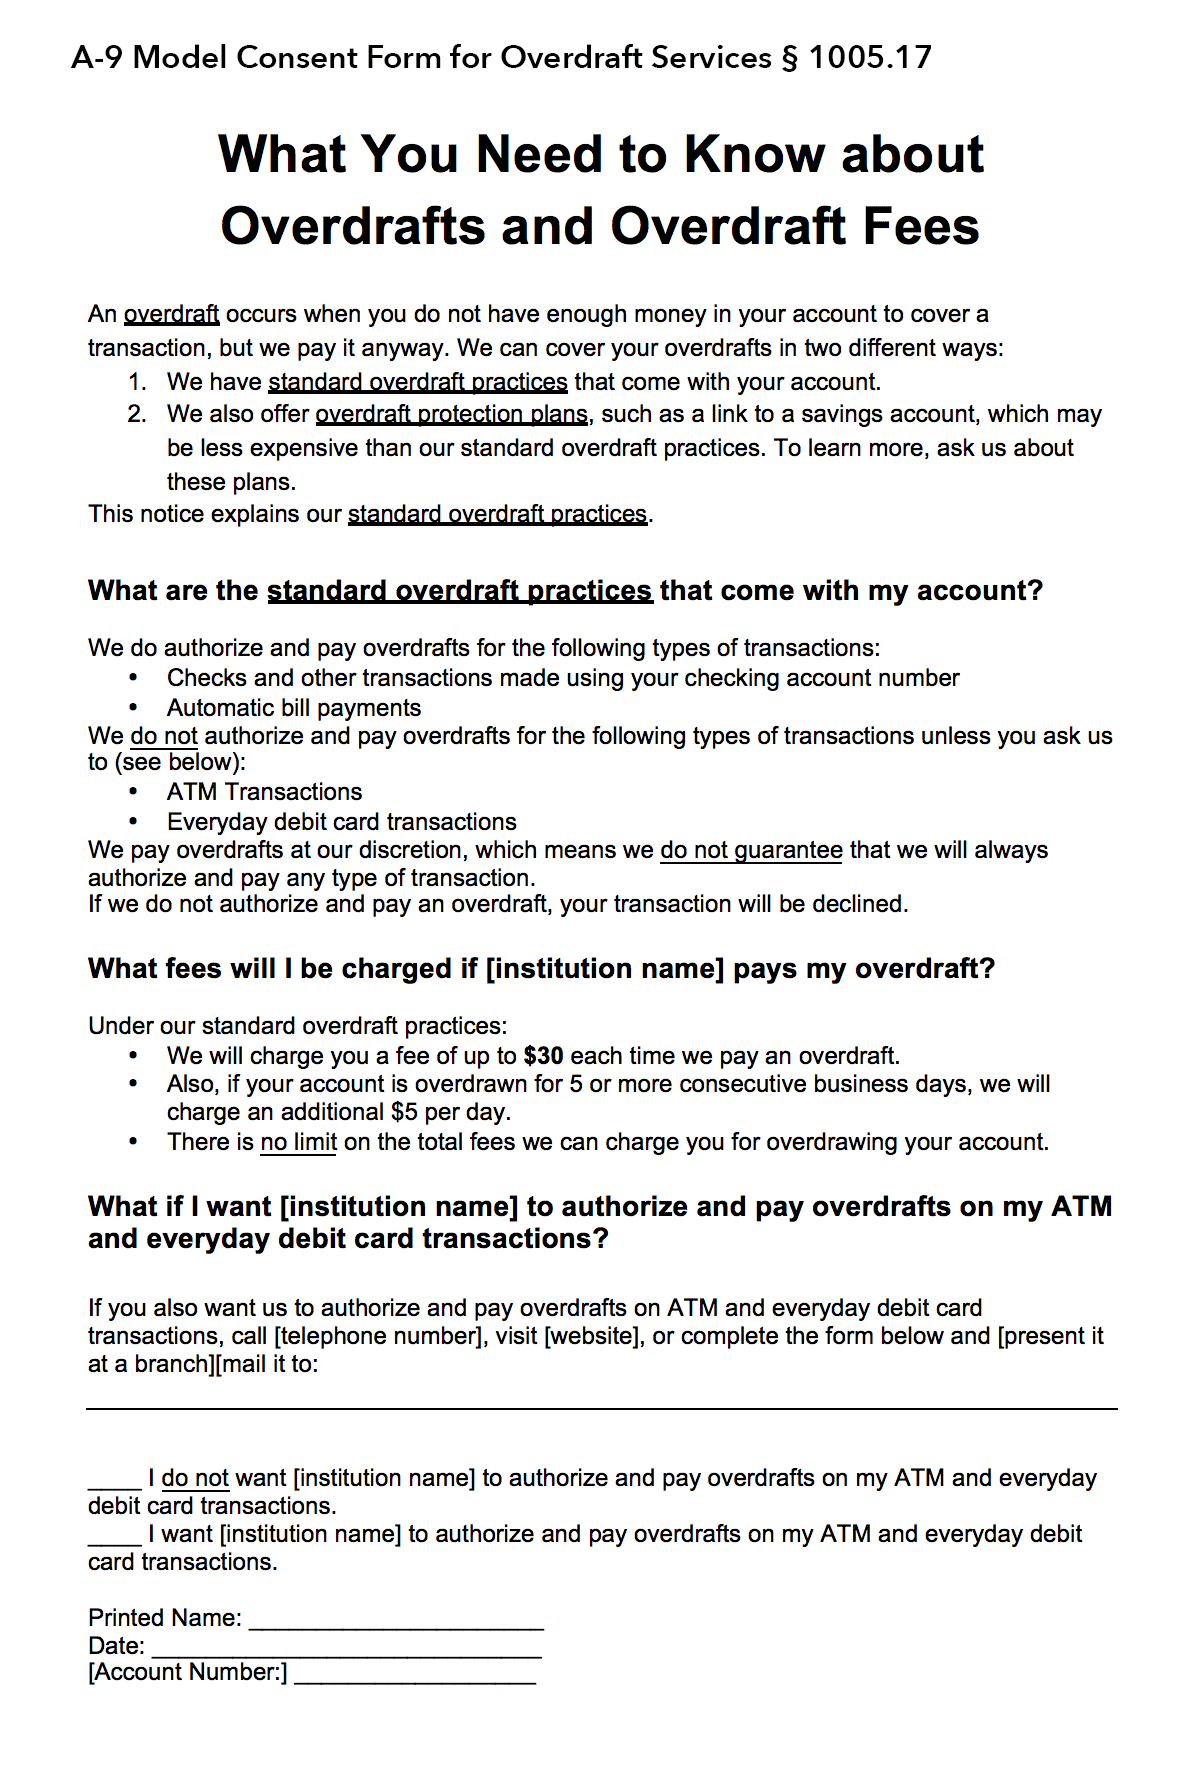
  1. The complete current text of § 1005.17 and its official interpretations was read. The current CFPB A-9 graphic did not yield readable pixels. I recovered and read the complete parsed text of the Federal Reserve’s original generic A-9, and the 2011 recodification expressly says the Bureau’s version was substantively identical, changing only the spelling of “website.” That establishes a useful textual history, but does not establish that I visually inspected the current form.
  2. Current OLRC body retrieval failed for 15 USC 1693a and 1693b and 12 USC 5519. Official 2024 U.S. Code bodies were recovered and read. Current regulation bodies and the specific 2025 public law were also read, but a complete 2025–2026 statutory and publication-lag audit was not completed. The latest eCFR § 1005.17 page inspected displayed Title 12 as updated through October 23, 2026; that is a title-level currency label, not a representation that § 1005.17 itself was amended that day. ecfr.gov+5

1. Substantive findings

1.1 The operative prohibition concerns fees for particular paid overdrafts

For an otherwise covered consumer account and overdraft service, the account-holding financial institution may not assess a fee or charge for paying an ATM or one-time debit-card transaction unless it satisfies all four requirements:

  1. A segregated notice describing the service, provided in writing or electronically if the consumer agrees.
  2. A reasonable opportunity to opt in.
  3. The consumer’s affirmative consent.
  4. Written confirmation, or electronic confirmation if the consumer agrees, including the right to revoke.

Affirmative consent is one requirement within that sequence. A signed general account agreement, a preselected box, continued account use, or the fact that a transaction was paid does not establish the required separate affirmative consent. Claims C029–C039 below separate these requirements and their timing. ecfr.gov+2

The institution may pay a covered overdraft without consent without charging for doing so. The commentary preserves its ability to debit the amount overdrawn only if otherwise permitted by applicable law. Conversely, an opt-in does not require the institution to authorize or pay an overdraft. This pass therefore determines neither an actual principal debt nor a right to collect it. C057–C058. Consumer Financial Protection Bureau

1.2 Coverage must be established before applying that prohibition

The relevant account ordinarily must be a consumer asset account established primarily for personal, family, or household purposes, and the consumer must be a natural person. A natural person’s business-purpose account is not converted into a covered consumer account merely because it has a debit card. Banks and credit unions fall within the relevant financial-institution definitions; the regulation also reaches certain other account holders and access-device issuers. The specific § 1005.17 duty is directed to the account-holding institution, and its debit-card scope depends on issuance by or on behalf of that institution. C002–C006, C018, C059. COMMERCE AND TRADE+4

The definition of overdraft service excludes specified arrangements: Regulation Z credit lines, transfers from another account held individually or jointly by the consumer, specified securities or commodities credit, and the particular prepaid-credit arrangements described in § 1005.17(a)(4). A negative balance alone does not identify which arrangement exists. C019–C025. Consumer Financial Protection Bureau+3

1.3 Checks, ACH, recurring debit cards, and other transfers require separate classification

The opt-in fee prohibition targets ATM and one-time debit-card transactions. It does not impose the same opt-in prerequisite on paid check, ACH, or recurring debit-card overdrafts. An ACH transfer may be an electronic fund transfer under Regulation E without becoming a one-time debit-card transaction under § 1005.17.

The commentary permits reliance on third-party transaction coding if the institution has adapted its systems to distinguish one-time from recurring transactions. Actual coding, the system condition, the payment arrangement, and the underlying channel remain unknown here. Repeated payments to the same payee do not, by themselves, establish the applicable classification. C007–C016, C059–C061. Consumer Financial Protection Bureau+3

1.4 Continuing negative-balance fees depend on attribution and timing

For a consumer who has not opted in:

  • A fee based on the amount of a negative balance is prohibited when that balance is solely attributable to ATM or one-time debit-card transactions.
  • Daily, sustained-overdraft, negative-balance, or similar fees are likewise prohibited when the balance is solely attributable to those transactions.
  • The commentary says § 1005.17 does not prohibit those balance-based or ongoing fees when the negative balance is attributable in whole or in part to checks, ACH, or other transactions outside the specific fee prohibition.
  • For a mixed balance, the timing of an ongoing fee must be based on when the relevant check, ACH, or other nonprotected transaction was paid into overdraft, rather than an earlier protected card transaction.

These are conclusions about this section’s prohibition. They do not establish that a fee is valid under every other law or the contract. Deposit allocation, posting order, associated fees, intervening credits, and the contractual fee trigger remain necessary factual holds. C064–C070. Consumer Financial Protection Bureau

1.5 Electronic delivery and overdraft consent are separate questions

Section 1005.4 supplies the general clear, understandable, retainable-disclosure framework. Section 1005.17 specifically permits electronic notice and confirmation if the consumer agrees.

The original adopting final rule expressly explains in footnote 32 that electronic disclosures under this section are not subject to E-Sign’s consumer-consent and other applicable provisions because the disclosures are not required solely in written form. The same footnote preserves the clear, understandable, retainable requirement. The 2010 clarification separately explains that an oral notice or oral confirmation does not satisfy the rule.

Accordingly, the audit must distinguish agreement to electronic delivery, separate affirmative overdraft consent, and delivery of the required confirmation. I have not added E-Sign’s demonstrated-access procedure as a separate § 1005.17 prerequisite. Other disclosures furnished in the same relationship can present independent E-Sign questions. C030–C034, C037–C038. Consumer Financial Protection Bureau+4

1.6 Authorization-positive/settlement-negative treatment is answered only in part

The current official commentary expressly addresses an institution that does not provide an opt-in notice, authorizes an ATM or one-time debit-card transaction believing funds are sufficient, and later pays it when funds are insufficient at settlement. It says the institution may not assess an overdraft fee for paying that transaction. A general practice of declining insufficient-funds authorizations does not create an exception. C062–C063. Consumer Financial Protection Bureau

Where a compliant opt-in is stipulated, § 1005.17 and the passages read do not resolve every authorization/settlement, available-balance, disclosure, unfairness, contract, or other legal issue. The broader legal basis is held. No court holding or later litigation status is asserted. C088–C090.

1.7 The 2024 rule and the withdrawn circulars cannot supply current operative requirements

The December 30, 2024 final rule, Overdraft Lending: Very Large Financial Institutions, stated an October 1, 2025 effective date. Public Law 119-10, approved May 9, 2025, disapproved that named rule and provided that it has no force or effect. Its added “covered overdraft credit” interpretation and related new framework are not used as current authority here. The preexisting § 1005.17 rule remains the relevant published opt-in framework. C082–C085. govinfo.gov+4

CFPB Circular 2022-06 on unanticipated overdraft fees and Circular 2024-05 on improper overdraft opt-in practices are listed in the official Withdrawn Guidance register as withdrawn May 12, 2025. Their publisher pages were checked, but their historical analyses are not used as substitutes for operative law. Withdrawal does not itself repeal EFTA or Regulation E, and does not establish that every affected fee is lawful. C086–C088. Consumer Financial Protection Bureau+4

2. Source table

Reading conventions: “Fresh” means accessed in this assignment. Repeated opens were rereads within this assignment, not reuse of a prior report. HTML has no printed-page or PDF-index pinpoint unless stated. PDF indices are zero-based. Sections and reproductions of the same regulation are grouped or expressly identified as related; they are not independent corroboration.

All entries below concern U.S. federal authority and were checked on 2026-10-27 PDT.

2.1 Statutes, current regulations, and forms

Source ID Issuer/title and complete literal HTTPS URLs Exact provisions; printed page / PDF index Version, effective predicate, status Fresh-read extent and currentness limits
R010-P1-S001 Congress; GPO, EFTA definitions and rulemaking authority. https://www.govinfo.gov/content/pkg/USCODE-2024-title15/html/USCODE-2024-title15-chap41-subchapVI-sec1693a.htm ; https://www.govinfo.gov/content/pkg/USCODE-2024-title15/pdf/USCODE-2024-title15-chap41-subchapVI-sec1693b.pdf § 1693a operative definitions, especially (2), (6)–(11); § 1693b(a)–(e), particularly (a)–(d). PDF pp. 1645–1648, indices 0–3; its first page also contains the end of § 1693a. Official 2024 Edition bodies. Statutory authority and definitions; not a representation of a fully audited October 2026 statutory edition. Fresh, body read. Current OLRC versions of §§ 1693a–b failed; recovery was the official 2024 edition. 2025–2026 statutory lag remains open. COMMERCE AND TRADE+2
R010-P1-S002 Congress; OLRC, 15 USC 1693l—Waiver of rights. https://uscode.house.gov/us/usc/119-134/t15/s1693l/ Entire operative paragraph and source credit; HTML, page/index N/A. Header states laws in effect through PL 119-134, October 20, 2026. Applies to agreements waiving EFTA rights, with express exceptions. Fresh, complete operative paragraph read. A direct repeat retrieval failed; reopening the previously retrieved reference recovered the body. Compilation label is not a session-law lag audit. uscode.house.gov
R010-P1-S003 CFPB, Regulation E gateway, general disclosures, and ATM-operator distinction. https://www.consumerfinance.gov/rules-policy/regulations/1005/1/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/2/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/3/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/4/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/16/ § 1(a)–(b); necessary § 2 definitions, including (a), (b), (e), (f), (h), (i), (k), (l), with relevant comments; § 3(a)–(c) and embedded interpretations; § 4(a)–(d) and comments; § 16(a)–(d). HTML, page/index N/A. Agency pages labeled current regulation. Scope and exceptions depend on the account, actor, agreement, transfer, and product. Fresh bodies read. Full § 2(b)(3) text was read, but its remote tax, benefits, and gift-card cross-references were not comprehensively followed. Full error-resolution, unauthorized-transfer, remittance, and broader disclosure regimes were not examined. Same Part 1005 as S004–S005, not independent corroboration. Consumer Financial Protection Bureau+6
R010-P1-S004 CFPB/OFR/GPO, 12 CFR 1005.17—Requirements for overdraft services, and official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1005/17/ ; https://www.ecfr.gov/current/title-12/chapter-X/part-1005/subpart-A/section-1005.17 ; https://www.govinfo.gov/link/cfr/12/1005?link-type=pdf&sectionnum=17&year=mostrecent Entire § 17(a)–(g) and all embedded § 17 official comments, including 17(b)-9.ii.A–C and -9.iii. Annual PDF pp. 204–206, indices 0–2, § 17 only. CFPB current label; latest eCFR read displayed Title 12 through 2026-10-23 and described eCFR as authoritative but unofficial. PDF resolves to 1-1-26 Edition, source note 76 FR 81023, amended 81 FR 84328. Historical § 17(c) triggers remain printed in current text. Fresh, complete necessary operative section and interpretations read. Annual PDF parsed text read; screenshots did not yield inspectable pixels. No full post-October-23 publication-lag audit. These are reproductions of one regulatory instrument. ecfr.gov+5
R010-P1-S005 CFPB/OFR, Current Appendix A, Model A-9, and Appendix A interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1005/a/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/interp-a/ ; https://files.consumerfinance.gov/f/ER27DE11.000.png ; https://www.ecfr.gov/current/title-12/chapter-X/part-1005/appendix-Appendix%20A%20to%20Part%201005 A-9 heading and linked graphic; Appendix A comments 1–3; complete A-9-specific instructions in § 17(d) and comments 17(d)-1–5, S004. HTML/PNG; printed page/index N/A. Current agency appendix presentation; eCFR appendix currency label through 2026-10-23. Fresh, partial form read. Current instructions and appendix comments read. Current graphic returned an image placeholder, not visible pixels or complete extracted form text. Current visual form comparison remains unresolved. Consumer Financial Protection Bureau+3
R010-P1-S006 Federal Reserve, generic Model A-9 distributed with the 2009 final rule. https://www.federalreserve.gov/newsevents/pressreleases/files/bcreg20091112a3.pdf ; discovery page: https://www.federalreserve.gov/newsevents/pressreleases/bcreg20091112a.htm Complete one-page form body, parsed lines 0–35; unpaginated, PDF index 0. Historical November 12, 2009 distribution. S011 expressly describes the 2011 A-9 as substantively identical except “website” spelling. Fresh, complete parsed historical form text read; pixels not read. PDF metadata labels it an opt-out form, but the actual body and publisher link identify the relevant A-9 consent form; metadata was not substituted for the body. Illustrative fees and periods are not legal limits. Press release used for discovery, not operative dates. federalreserve.gov+2
R010-P1-S007 CFPB, Regulation Z cross-references necessary to § 17(a). https://www.consumerfinance.gov/rules-policy/regulations/1026/3/ ; https://www.consumerfinance.gov/rules-policy/regulations/1026/61/ § 1026.3(d), comment 3(d)-1; § 1026.61(a)(1)–(5), especially (a)(2), (a)(4), (a)(5)(iii)(D), and necessary embedded comments. HTML, page/index N/A. Agency current-regulation presentation. Applied only to the exclusions expressly incorporated by § 17(a). Fresh, necessary definition/exception bodies read. Full Reg Z lending, APR, origination, repayment, security, and remedy regimes remain held. Historical prepaid-effective-date chain was not comprehensively audited; no historical product application is made. Consumer Financial Protection Bureau+7
R010-P1-S008 Congress; OLRC, 15 USC 7001—E-Sign general rule. https://uscode.house.gov/us/usc/119-134/t15/s7001/ § 7001(a), (b), (c)(1)–(6); additional text and effective-date notes also returned. HTML, page/index N/A. Header through PL 119-134, October 20, 2026. § 7001(c) concerns information legally required in writing; see S009 for the § 17-specific adopting explanation. Fresh, complete relevant subsections read. Used to distinguish the general statute from the special overdraft disclosure treatment, not to create an extra § 17 consent condition. Compilation-lag qualification retained. uscode.house.gov

2.2 Final rules, disapproval, withdrawal status, and recovery sources

Source ID Issuer/title and complete literal HTTPS URLs Exact provisions; printed page / PDF index Version, effective predicate, status Fresh-read extent and currentness limits
R010-P1-S009 Federal Reserve, Electronic Fund Transfers—2009 final rule and official staff commentary. https://www.federalregister.gov/documents/2009/11/17/E9-27474/electronic-fund-transfers ; https://www.govinfo.gov/content/pkg/FR-2009-11-17/pdf/E9-27474.pdf 74 FR 59033–59056, 24-page PDF, indices 0–23. Relevant read: dates at 59033 / 0; notice discussion and complete footnote 32 at 59041–59042 / 8–9; confirmation discussion 59043 / 10. Published 2009-11-17; effective 2010-01-19; mandatory compliance 2010-07-01, with existing-account treatment in § 17(c). Historical adopting rule; subsequently clarified and recodified. Fresh, selected necessary body passages read, not a claimed full 24-page read. Official PDF verified the electronic-delivery explanation. Original former § 205.17(b)(4) is not used as current text. govinfo.gov+3
R010-P1-S010 Federal Reserve, 2010 clarification and correction. https://www.federalregister.gov/documents/2010/06/04/2010-13280/electronic-fund-transfers ; https://www.govinfo.gov/content/pkg/FR-2010-06-04/pdf/2010-13280.pdf ; https://www.federalregister.gov/documents/2010/06/15/2010-14353/electronic-fund-transfers ; https://www.govinfo.gov/content/pkg/FR-2010-06-15/pdf/2010-14353.pdf 75 FR 31665–31673, indices 0–8: scope/confirmation discussion, balance-fee discussion, content instructions, and amendatory text. Correction at 33681 / index 0, operative correction fully read. Both effective 2010-07-06. Clarification removes former (b)(4); correction specifies revision of the (b)(1) introductory text, preserving the subparagraph requirements. Fresh, selected relevant clarification passages and complete correction read. Current complete comments are independently read as the same regulation in S004. Historical PDF’s final page also contains another rule, which is not adopted as a foundation. federalregister.gov+4
R010-P1-S011 CFPB, Electronic Fund Transfers—2011 recodification. https://www.govinfo.gov/content/pkg/FR-2011-12-27/pdf/2011-31725.pdf 76 FR 81020–81058, 39 pages. Necessary read at 81020–81021 / indices 0–1: transfer, recodification, effective date, A-9 change. Interim final rule; effective 2011-12-30. Rulemaking transfer described as effective 2011-07-21. No new substantive obligations asserted by this recodification. Fresh, selected body read. A-9 continuity passage fully read. The embedded A-9 graphic was not visually inspected; its exact graphic-page location is not asserted. Not merely a proposal. govinfo.gov
R010-P1-S012 CFPB, Overdraft Lending: Very Large Financial Institutions. https://www.federalregister.gov/documents/2024/12/30/2024-29699/overdraft-lending-very-large-financial-institutions ; https://www.govinfo.gov/content/pkg/FR-2024-12-30/pdf/2024-29699.pdf 89 FR 106768–106845, 78 pages. Dates 106768 / 0; § IV discussion and § V timing 106816 / 48; complete added comment 17(a)-2 at 106837 / 69. Published 2024-12-30, stated effective 2025-10-01; disapproved before that date by S013. Fresh, selected provisions read, not all 78 pages. Used only to identify the exact disapproved change and original trigger. No proposed or disapproved framework is used as current authority. govinfo.gov+2
R010-P1-S013 Congress, Public Law 119-10, S.J. Res. 18. https://www.govinfo.gov/content/pkg/PLAW-119publ10/pdf/PLAW-119publ10.pdf 139 Stat. 53 / PDF index 0, entire one-page law. Approved 2025-05-09. Disapproves the specifically named 89 FR 106768 final rule and gives it no force or effect. Fresh, complete parsed law read. Screenshot yielded no inspectable pixels; the text body was fully available. No docket or litigation-status inference. govinfo.gov
R010-P1-S014 CFPB, Overdraft Lending compliance resource/status page. https://www.consumerfinance.gov/compliance/compliance-resources/deposit-accounts-resources/overdraft-lending-very-large-financial-institutions/ “Featured topic” paragraph; HTML, page/index N/A. Page modified 2025-07-01. Says the final rule has no force/effect and remaining Reg E/Z remain unchanged. Fresh status paragraph read. Its statement that signing occurred May 12 conflicts with S013’s May 9 approval date. Public-law date controls this report. Resource label does not replace operative text. Consumer Financial Protection Bureau
R010-P1-S015 CFPB, Withdrawn Guidance register and withdrawal notice. https://www.consumerfinance.gov/compliance/guidance/withdrawn-guidance/ ; https://www.federalregister.gov/documents/2025/05/12/2025-08286/interpretive-rules-policy-statements-and-advisory-opinions-withdrawal ; https://www.govinfo.gov/content/pkg/FR-2025-05-12/pdf/2025-08286.pdf Register’s Circulars & Supervisory Guidance entries for 2024-05 and 2022-06; notice parts I–III and relevant entries. 90 FR 20084–20087, indices 0–3; applicability at 20084 / 0, operative withdrawal discussion 20085 / 1, relevant list 20086 / 2. Withdrawals applicable 2025-05-12. Register last-modified label 2026-07-22. Fresh register and necessary notice bodies read. Register and notice are one publisher’s status chain, not independent corroboration. Withdrawal is not treated as statutory repeal or a universal fee validation. Consumer Financial Protection Bureau+3
R010-P1-S016 CFPB, historical circular publisher pages. https://www.consumerfinance.gov/compliance/circulars/consumer-financial-protection-circular-2022-06-unanticipated-overdraft-fee-assessment-practices/ ; https://www.consumerfinance.gov/compliance/circulars/consumer-financial-protection-circular-2024-05/ Titles, questions/answers and relevant scope passages; HTML, page/index N/A. Register cites 87 FR 66935, Nov. 7, 2022, and 89 FR 80075, Oct. 2, 2024. Withdrawn, as verified against S015. Fresh, limited publisher-page read and status check. Not a full read of every cited authority. No historical enforcement/evidence theory is adopted as current operative law. Continued page availability is not currentness. Consumer Financial Protection Bureau+4
R010-P1-S017 Congress; GPO, 12 USC 5519—Exclusion for auto dealers. https://www.govinfo.gov/content/pkg/USCODE-2024-title12/html/USCODE-2024-title12-chap53-subchapV-partB-sec5519.htm Entire operative (a)–(f), particularly jurisdictional exclusion, exceptions, preserved authorities, and definitions. HTML, page/index N/A. Official 2024 Edition recovery. Cross-reference in §§ 1005.2(i), 1005.3(a), and 1693b(a)(2). Fresh body read. Current OLRC retrieval failed. No dealer, license, entity, or business-line classification was attempted. Statutory lag remains held. BANKS AND BANKING
R010-P1-S018 GPO, full Part 1005 recovery attempts. https://www.govinfo.gov/content/pkg/CFR-2025-title12-vol8/pdf/CFR-2025-title12-vol8-part1005.pdf ; https://www.govinfo.gov/content/pkg/CFR-2026-title12-vol8/pdf/CFR-2026-title12-vol8-part1005.pdf ; https://www.govinfo.gov/link/cfr/12/1005?link-type=pdf&year=mostrecent 2025 A-9 location: printed 245 / index 60, heading but missing form-body extraction. 2026 full-part header/initial text retrieved; subsequent targeted retrievals timed out. Annual editions, not October 2026 complete currency guarantees. Fresh, partial/discovery/failure. No whole-part read claimed. Used to attempt form/text recovery, not independent authority beyond S003–S005.

3. Atomic claim table

Status key: R = operative regulation as currently published in the inspected sources; O = official interpretation; S = statutory text, subject to the stated edition limit; H = historical final-rule explanation or event; D = disapproved rule; W = withdrawn guidance; I = expressly identified inference; U = unresolved.

“Current” below inherits the source-currency limits in S001–S018. It does not represent a completed session-law, litigation, or publication-lag audit.

3.1 Coverage, actors, products, and transaction boundaries

Claim ID Precise claim / area Source and pinpoint Trigger, conditions, exceptions Status / limits
R010-P1-C001 EFTA supplies rulemaking authority for Regulation E; the specific overdraft opt-in conditions are in § 1005.17. S001, § 1693b(a)–(c); S003, § 1005.1(a); S011, 81021. govinfo.gov+2 Bureau authority has statutory reservations, including Board authority described in § 1693b(a)(2). S/R; current statutory-body gap disclosed.
R010-P1-C002 The relevant consumer/account gateway requires a natural person and an asset account established primarily for personal, family, or household purposes. S001, § 1693a(2), (6); S003, §§ 1005.2(b)(1), (e). COMMERCE AND TRADE+2 Business-purpose accounts do not qualify merely because a natural person owns or uses them. S/R; actual purpose unknown.
R010-P1-C003 The account definition excludes incidental credit balances in open-end credit plans and accounts held under bona fide trust agreements. S001, § 1693a(2); S003, § 1005.2(b)(1)–(2), comments 2(b)(2). COMMERCE AND TRADE+1 Trust status depends on the actual arrangement and governing law; the comment supplies additional excluded-account examples. S/R/O; no actual account classification.
R010-P1-C004 Banks, savings associations, and credit unions are included financial-institution classes; the regulation also includes specified other account holders and access-device issuers. S001, § 1693a(9); S003, § 1005.2(i). COMMERCE AND TRADE+1 Direct/indirect holding, or access-device issuance plus agreement to provide EFT services, must fit the definition; statutory excluded-person clause remains. S/R; no named institution or charter inquiry.
R010-P1-C005 The CFPA § 1029 cross-reference is a conditional jurisdictional exclusion, not a blanket statement that all auto-related activity is outside federal EFT law. S017, § 5519(a)–(c), (f); S001, § 1693b(a)(2). BANKS AND BANKING+1 Predominant vehicle-dealer activity; exceptions for specified real-property services, retained direct retail credit/leases, and unrelated consumer financial services; other agency authorities preserved. S; 2024 body, later statutory lag and all entity facts held.
R010-P1-C006 Regulation E account coverage requires an EFT-service agreement of the kind described in comment 3(a)-1. S003, § 1005.3(a), comments 3(a)-1–2. Consumer Financial Protection Bureau Consumer–FI agreement, or consumer–third-party agreement with FI notice and transfers begun. ACH membership alone is insufficient. R/O; actual agreement unknown.
R010-P1-C007 EFT coverage includes qualifying ATM, POS, debit-card, ACH, direct-deposit/withdrawal, telephone, and computer-initiated transfers. S003, § 1005.3(b)(1), comment 3(b)(1)-1. Consumer Financial Protection Bureau Must instruct debit/credit of a covered consumer account and survive applicable exclusions. R/O; channel labels require facts.
R010-P1-C008 A check converted into an ACH EFT differs from a check collected or re-presented electronically as a check. S003, § 1005.3(b)(2), comments 3(b)(1)-1.v and 3(c)(1)-1–2. Consumer Financial Protection Bureau+1 Using check information to initiate ACH can be EFT; electronic re-presentment of the original check remains within the check exclusion. R/O; no transaction coding assumed.
R010-P1-C009 Being an EFT does not by itself bring a transfer within the ATM/one-time debit-card fee prohibition. S003, § 1005.3(b); S004, § 1005.17(b)(1). Consumer Financial Protection Bureau+1 The specific transaction must fit § 17’s channel and service conditions. I from R; one-time ACH is not automatically one-time debit card.
R010-P1-C010 Fedwire and similar systems used primarily for interinstitutional or business transfers are excluded EFT channels under § 1005.3(c)(3). S003, § 3(c)(3), comments 1–3. Consumer Financial Protection Bureau A subsequent ACH transfer to the consumer account can still be covered. R/O; no full wire-transfer or UCC analysis.
R010-P1-C011 The securities/commodities EFT exclusion depends on the transfer’s primary purpose and specified regulatory or book-entry conditions. S003, § 3(c)(4), comments 1–3. Consumer Financial Protection Bureau Ordinary purchases or cash withdrawals using a debit device against such an account are not automatically excluded. R/O; separate from the credit exclusion in C021.
R010-P1-C012 Specified automatic transfers within the same institution, including automatic fee entries, may be excluded from the EFT definition. S003, § 3(c)(5), comments 1–2. Consumer Financial Protection Bureau Agreement and institution initiation without a specific consumer request; prescribed account relationships. Affiliated institutions are not automatically the same institution. Compulsory-use and specified liability provisions remain preserved. R/O; exclusion of a bookkeeping transfer does not authorize the underlying fee.
R010-P1-C013 The telephone-transfer exclusion is conditional on absence of the specified telephone bill-payment or other written recurring-transfer plan. S003, § 3(c)(6), comments 1–2. Consumer Financial Protection Bureau A written service description can constitute a plan; infrequent use or separate requests do not necessarily remove coverage. R/O; actual arrangement held.
R010-P1-C014 The small-institution exemption is limited to preauthorized transfers, not every EFT or every overdraft fee. S003, § 3(c)(7), comment 1. Consumer Financial Protection Bureau Assets $100 million or less on the preceding December 31; specified phase-out one year after the end of the year in which assets exceed that figure; preserved provisions remain applicable. R/O; sourced threshold, no entity calculation.
R010-P1-C015 Comment 3(a)-3 supplies a U.S.-account/state-resident geographic framework, including certain U.S. offices of foreign banks. S003, comment 3(a)-3; § 2(l). Consumer Financial Protection Bureau+1 A foreign branch of a U.S. bank is not covered unless services connect to an account in a defined state; a particular transfer’s foreign location is not conclusive. O/R; international and actual-location questions held.
R010-P1-C016 A preauthorized EFT is authorized in advance to recur at substantially regular intervals without further consumer action. S003, § 2(k), comment 2(k)-1. Consumer Financial Protection Bureau Repeated separately initiated payments do not establish that definition; § 17 coding reliance remains separately relevant. R/O; recurring classification unknown without facts.
R010-P1-C017 “Prepaid account” is a defined category with specific inclusions and exclusions, not a synonym for every stored-value, gift, benefit, or digital-wallet product. S003, § 2(b)(3) and comments. Consumer Financial Protection Bureau+1 Payroll/government-benefit categories and specified prepaid/general-transaction products; exclusions include enumerated health, disaster, military closed-loop, gift, and needs-tested benefit arrangements. Checking/share-draft/NOW accounts are excluded from the residual prepaid category. R/O; remote benefits, tax, and gift-card definitions not comprehensively closed.
R010-P1-C018 A § 17 overdraft service involves the institution charging its consumer account for paying a transaction when funds are insufficient or unavailable. S004, § 17(a). Consumer Financial Protection Bureau Account held by that institution; paid transaction; fee or charge; no applicable § 17(a)(1)–(4) exclusion. R; a negative ledger entry alone is insufficient classification evidence.
R010-P1-C019 Payments pursuant to a credit line subject to Regulation Z are excluded from the § 17 overdraft-service definition. S004, § 17(a)(1). Consumer Financial Protection Bureau Includes transfers from a credit-card account, HELOC, or overdraft credit line if the specified predicate is met. R; full credit-law consequences held.
R010-P1-C020 A service transferring funds from another account held individually or jointly by the consumer is excluded from the § 17 overdraft-service definition. S004, § 17(a)(2). Consumer Financial Protection Bureau Actual transfer arrangement required; the definition does not simply equate every negative balance with such a transfer. R; transfer charges and other laws not decided.
R010-P1-C021 Specified securities/commodities credit exempt under Regulation Z § 1026.3(d) is excluded from § 17. S004, § 17(a)(3), comment 17(a)-1; S007, § 1026.3(d), comment 1. Consumer Financial Protection Bureau+1 Credit involving securities/commodities accounts extended by the specified SEC/CFTC-registered broker-dealer; a separate loan merely used to buy securities is not enough. R/O; no registration or entity lookup.
R010-P1-C022 The covered separate-credit-feature exclusion is specific to the qualifying feature accessible by a hybrid prepaid-credit card. S004, § 17(a)(4); S007, § 1026.61(a)(1)–(2), (5). Consumer Financial Protection Bureau+2 Card capability to access credit during transaction authorization, settlement, or completion, and provision by issuer, affiliate, or qualifying business partner. Noncovered separate credit can independently be subject to Reg Z. R/O; no blanket exclusion of the entire prepaid account.
R010-P1-C023 The prepaid negative-asset-balance exclusion requires the complete § 1026.61(a)(4) conditions. S007, § 61(a)(4)(i)–(ii)(A)–(C) and comments. Consumer Financial Protection Bureau+2 No access to issuer/affiliate covered separate credit; required decline policy/practice, with permitted $10 and unsettled-load cushions, which may coexist; no prohibited credit/negative-balance fees or higher fees because of credit. Actual collection costs are excepted only if otherwise lawful, and late fees are not such costs. Ordinary nonprohibited fees can themselves create a negative balance. R/O; sourced legal cushion, no worked calculation; ordinary checking-account overdrafts cannot borrow this exception.
R010-P1-C024 The business-partner definition has a specific exception for qualifying traditional-credit-card links. S007, § 61(a)(5)(iii)(A)–(D), related comments. Consumer Financial Protection Bureau+2 Traditional open-end non-home-secured card; separately signed/initialized request subject to stated pre-April-1-2019/pre-arrangement treatment; no prohibited conditioning; same prepaid terms/comparable load fees; same specified credit terms across linking and access methods. Network membership alone is insufficient to establish the arrangement. R/O; definition only, no full credit-account compliance determination.
R010-P1-C025 “Deposit advance,” “negative account,” and “setoff” labels do not establish a § 17 overdraft service or exclusion. S004, § 17(a), comment 17(b)-2; S003, § 2(f), § 3(c)(5). Consumer Financial Protection Bureau+3 Funding mechanism, paid transaction, credit agreement, fee causation, and any asserted debit/setoff authority must be distinguished. I/U; no lending or setoff authority resolved.
R010-P1-C026 A fee for returning an item unpaid is analytically different from a fee for paying an overdraft. S004, § 17(a), (b)(1); S003, § 3(b)(3). Consumer Financial Protection Bureau+2 Establish whether the item was actually paid or returned; do not classify by an ambiguous fee label. R/I; § 17’s paid-overdraft prohibition does not establish NSF legality.
R010-P1-C027 Electronic collection of a returned-item fee has its own authorization rule, distinct from overdraft opt-in. S003, § 3(b)(3)(i)–(ii), comments 1–4. Consumer Financial Protection Bureau+1 Notice plus proceeding with the underlying transaction can authorize that particular fee EFT; POS notice/copy conditions apply. Comment 1 excludes the account-holding FI’s own return/pay fee from this particular authorization provision. R/O; this rule cannot be imported to infer § 17 opt-in from account use.
R010-P1-C028 An ATM operator’s access/balance-inquiry fee is distinct from the account-holding institution’s overdraft fee. S003, § 1005.16(a)–(d); S001, § 1693b(d)(3). Consumer Financial Protection Bureau+1 § 16 operator does not hold the account; fee notice with amount must precede commitment, and the consumer must elect to continue. R/S; continuing after an ATM fee screen does not itself establish separate overdraft consent.

3.2 Notice, consent, confirmation, form, and delivery

Claim ID Precise claim / area Source and pinpoint Trigger, conditions, exceptions Status / limits
R010-P1-C029 Four cumulative conditions govern charging for a covered paid ATM/one-time debit-card overdraft. S004, § 17(b)(1)(i)–(iv). ecfr.gov Notice, reasonable opportunity, affirmative consent, and confirmation with revocation information; historical timing in (c). R; affirmative consent alone is insufficient.
R010-P1-C030 The notice must be segregated, written or agreed electronic, clear, understandable, and retainable. S004, § 17(b)(1)(i); S003, § 4(a); S010, 31667. ecfr.gov+2 Oral notice does not satisfy the written/electronic disclosure requirement. R/O/H; actual delivery and retained form unknown.
R010-P1-C031 E-Sign § 7001(c) supplies a general consumer-electronic-record framework when law requires information in writing. S008, § 7001(b), (c)(1)–(6). uscode.house.gov Includes consent, prescribed information, access demonstration, and relevant exceptions when applicable. S; not automatically imported into § 17.
R010-P1-C032 The § 17 adopting explanation expressly treats electronic disclosures under that section as outside E-Sign’s consumer-consent requirements, while retaining clarity and retainability. S009, footnote 32, 59041–59042, indices 8–9; current § 17(b)(1)(i), (iv). govinfo.gov+2 Consumer agreement to electronic delivery remains required by § 17’s own text. H explaining R; not a withdrawn CFPB circular; other documents’ E-Sign treatment held.
R010-P1-C033 Reasonable opportunity includes reasonable means of communicating consent. S004, comment 17(b)-4.i–iv. Consumer Financial Protection Bureau Mail form, readily available telephone line, electronic choice/affirmation, and in-person form are examples; not a mandate to offer all four. O; actual opportunity unknown.
R010-P1-C034 Overdraft consent must be obtained separately from other consents and acknowledgments. S004, comment 17(b)-6. Consumer Financial Protection Bureau Includes separation from electronic-delivery consent. General preprinted account language and preselected opt-in boxes do not satisfy it. O; actual consent evidence held.
R010-P1-C035 Account use or acceptance of an access device cannot, without an authorized separate basis, be substituted for affirmative overdraft consent. S004, § 17(b)(1)(iii), comments 17(b)-5–6; S003, § 2(a). Consumer Financial Protection Bureau+1 Different statutory/regulatory forms of acceptance must not be conflated. I from R/O; no implied-consent finding.
R010-P1-C036 An institution may require an account-opening yes/no choice, but silence is not opt-in. S004, comment 17(b)-5. Consumer Financial Protection Bureau No selected box/signature means no opt-in; offered accounts must comply with (b)(2)–(3). O; not permission to require the “yes” answer.
R010-P1-C037 Confirmation must record the consent and include the right to revoke; a completed notice copy or acknowledgment letter can suffice. S004, § 17(b)(1)(iv), comment 17(b)-7. Consumer Financial Protection Bureau Writing, or electronic if agreed; oral confirmation does not satisfy the disclosure requirement. R/O; actual content and delivery unknown.
R010-P1-C038 The confirmation timing standard concerns transactions paid after confirmation is mailed or delivered. S004, comment 17(b)-7; S010, 31667–31668. Consumer Financial Protection Bureau+1 Comment recognizes compliance through reasonable procedures designed to ensure that timing. Consumer receipt is not required before a fee; later fee posting alone does not cure the payment-timing issue. O/H; actual procedures and any error remain unresolved.
R010-P1-C039 Covered overdraft fees may concern only overdrafts paid on or after receipt of affirmative consent, subject also to confirmation requirements. S004, comment 17(c)-1. Consumer Financial Protection Bureau Later consent does not retrospectively validate fees for earlier paid transactions. O; event times unknown.
R010-P1-C040 The opt-in notice must be substantially similar to A-9, include every applicable required item, and contain only specified or permitted information. S004, § 17(d). Consumer Financial Protection Bureau Specific § 17 rules govern permissible content and format. R; no current form visual-comparison conclusion.
R010-P1-C041 The notice must explain the service and relevant transaction types; other-transaction policies must not overshadow the opt-in right. S004, § 17(d)(1), comment 17(d)-1. Consumer Financial Protection Bureau Include discretion/possible decline explanation as applicable. R/O; actual policy and accuracy unknown.
R010-P1-C042 All applicable overdraft fees must be disclosed, including daily, sustained, and negative-balance fees; a variable fee requires its maximum. S004, § 17(d)(2), comment 17(d)-2. Consumer Financial Protection Bureau Amount can vary by number of overdrafts, overdraft size, or other factors. R/O; no actual fee amount supplied or calculated.
R010-P1-C043 The notice must disclose the maximum number of fees per day, or disclose that there is no limit. S004, § 17(d)(3). Consumer Financial Protection Bureau This is a disclosure requirement; it is not a national numerical fee cap or blanket permission under other law. R/I.
R010-P1-C044 The notice must explain the right to opt in and the means available for doing so. S004, § 17(d)(4), comment 17(d)-3. Consumer Financial Protection Bureau Methods must match what the institution actually offers. R/O.
R010-P1-C045 Offered linked-credit and same-institution account-transfer alternatives must be disclosed as applicable. S004, § 17(d)(5), comment 17(d)-5. Consumer Financial Protection Bureau Both offered means disclose both; one means disclose that one; neither means omit that reference. Other alternatives may be listed. R/O; offering an alternative is not established here.
R010-P1-C046 Section 17(d)(6) permits specified additional content concerning other-transaction choices, associated returned-item/merchant fees, revocation, and historical existing-account wording. S004, § 17(d)(6). Consumer Financial Protection Bureau Only as applicable; optional initial revocation wording does not eliminate mandatory revocation information in confirmation. R.
R010-P1-C047 A-9 can be tailored to offered consent methods; a tear-off form and a decline box are not invariably required. S004, comments 17(d)-3–4. Consumer Financial Protection Bureau Reasonable account-identification methods are permitted; no identifiers are entered in this pass. O; no specific form approved.
R010-P1-C048 Appendix A comments do not give blanket approval of institutional forms or every fee charged under them. S005, Appendix A comments 1–3; S004, § 17(d). Consumer Financial Protection Bureau+1 Accurate use of appropriate model language concerns proper disclosure form; specific § 17 content limits remain. O/I; no individualized safe-harbor or liability decision.
R010-P1-C049 Historical A-9 text was fully read; current A-9 pixels were not. S005–S006; S011, 81021. federalreserve.gov+1 The 2011 text-continuity statement supports historical comparison, not an assertion of current visual inspection. H/U; current visual/read completeness remains partial.
R010-P1-C050 Section 4’s general permission to combine disclosures does not override § 17’s specific segregation and content restrictions. S003, § 4(b); S004, § 17(b)(1)(i), (d); S010, 31671. Consumer Financial Protection Bureau+2 Other material may be in the same mailing while the opt-in notice remains segregated. R/H/I.
R010-P1-C051 Regulation E permits another disclosure language if English is available on request. S003, § 4(a)(2), comment 4(a)-2. Consumer Financial Protection Bureau Applies alongside the required content and clarity standards. R/O; actual language/accessibility facts unknown.
R010-P1-C052 For joint accounts, one set of required disclosures may be provided to any account holder. S003, § 4(c)(2). Consumer Financial Protection Bureau Separate § 17(e) governs whose consent or revocation binds the account. R; disclosure delivery is not itself consent.
R010-P1-C053 Institutions offering EFT services jointly may allocate compliance by agreement, but § 4(d)’s knowledge limitation expressly concerns §§ 7 and 8. S003, § 4(d). Consumer Financial Protection Bureau Does not itself create a § 17 exception for the account-holding institution. R/I; actual actor allocation unknown.

3.3 Fee authority, causation, transaction coding, and revocation

Claim ID Precise claim / area Source and pinpoint Trigger, conditions, exceptions Status / limits
R010-P1-C054 An institution cannot condition paying check/ACH/other overdrafts on ATM/debit opt-in or decline them because opt-in was refused. S004, § 17(b)(2), comment 17(b)(2)-1. ecfr.gov+1 Apply the same payment criteria consistently; this does not compel payment of every check or ACH item. R/O.
R010-P1-C055 Consumers declining opt-in must receive the same other account terms, conditions, and features. S004, § 17(b)(3), comment 17(b)(3)-1. Consumer Financial Protection Bureau Includes interest paid, fees, card capabilities, minimum balance, and online bill pay; exception is the protected overdraft service itself. R/O.
R010-P1-C056 Independently justified limited-feature accounts remain possible, but refusal to opt in cannot be used to divert an otherwise eligible consumer to them. S004, comment 17(b)(3)-2. Consumer Financial Protection Bureau Actual eligibility and account terms required. O; no creditworthiness decision.
R010-P1-C057 Without opt-in, the institution may pay the covered transaction but cannot charge for paying it. S004, comment 17(b)-2. Consumer Financial Protection Bureau Debit of principal is preserved only if permitted under other applicable law. O; no debt-validity, collection, or setoff conclusion.
R010-P1-C058 Opt-in does not guarantee authorization or payment of an overdraft. S004, comment 17(b)-3. Consumer Financial Protection Bureau Contractual or other obligations are not adjudicated here. O.
R010-P1-C059 Section 17(b) covers the relevant debit card only when issued by or on behalf of the account-holding institution. S004, comment 17(b)-1.i. Consumer Financial Protection Bureau Third-party issuance without the “on behalf of” relationship is outside that stated scope. O; actual issuance/funding relationship unknown.
R010-P1-C060 A one-time debit-card transaction can qualify whether conducted at POS, online, or by telephone. S004, comment 17(b)-1.iii. Consumer Financial Protection Bureau Channel location does not substitute for recurring/one-time classification. O.
R010-P1-C061 The coding reliance rule requires systems adapted to identify one-time versus recurring transactions. S004, comment 17(b)-1.ii. Consumer Financial Protection Bureau After that condition is met, merchant/institution/third-party coding may be relied upon. O; coding accuracy, system adaptation, and actual reliance not established.
R010-P1-C062 The fee prohibition applies to all otherwise covered institutions, including those with a general decline policy. S004, comment 17(b)-1.iv. Consumer Financial Protection Bureau An institution charging no fees for these paid overdrafts need not perform the § 17(b)(1)(i)–(iv) notice/opt-in process for that fee-free service. O; no general policy-based fee exception.
R010-P1-C063 Positive authorization followed by negative settlement does not excuse a covered fee where the required opt-in was absent. S004, comment 17(b)-1.iv. Consumer Financial Protection Bureau Commentary’s express example includes intervening transactions reducing funds before settlement. O; other timing configurations and actual balances held.
R010-P1-C064 With no opt-in, a fee based on negative-balance amount is prohibited when that balance is solely attributable to protected ATM/one-time debit transactions. S004, comment 17(b)-8. Consumer Financial Protection Bureau Requires fee classification and sole attribution. O.
R010-P1-C065 Section 17 does not prohibit that amount-based fee when the negative balance is wholly or partly attributable to a check, ACH, or another nonprotected transaction. S004, comment 17(b)-8. Consumer Financial Protection Bureau Does not validate a separate per-item fee for an unconsented protected card transaction. O; other law/contract held.
R010-P1-C066 With no opt-in, daily/sustained/negative-balance/similar fees are prohibited when the negative balance is solely attributable to protected transactions. S004, comment 17(b)-9.i. Consumer Financial Protection Bureau Fee substance and causation govern; a new fee label does not answer causation. O/I.
R010-P1-C067 Section 17 does not prohibit those ongoing fees where a negative balance is wholly or partly attributable to nonprotected transactions. S004, comment 17(b)-9.i. Consumer Financial Protection Bureau Subject to the timing rule in C068 and actual remaining balance attribution. O; no all-law fee authorization.
R010-P1-C068 For a mixed negative balance, the ongoing-fee timing anchor is when the nonprotected transaction was paid into overdraft. S004, comment 17(b)-9.i, -9.ii.C. Consumer Financial Protection Bureau An earlier protected card overdraft does not supply that start date. O; contractual period, units, calendar, and events unknown.
R010-P1-C069 The official mixed-balance examples depend on expressly stipulated posting and deposit-allocation assumptions. S004, comment 17(b)-9.ii, examples A–C. Consumer Financial Protection Bureau Later deposits can alter which debit component remains; associated fees matter in the examples. Their sample amounts and periods are not national legal thresholds. O/I; no mandatory universal allocation method or actual calculation inferred.
R010-P1-C070 A conservative alternative permits avoiding ongoing fees unless the outstanding negative balance is solely attributable to nonprotected transactions. S004, comment 17(b)-9.iii. Consumer Financial Protection Bureau This alternative avoids calculating allocation of partial deposits; it is an alternative, not the only required method. O.
R010-P1-C071 Any joint consumer’s affirmative consent binds the account; any joint consumer’s revocation likewise revokes account consent. S004, § 17(e). Consumer Financial Protection Bureau Joint relationship must actually exist. R; no requirement that every joint holder separately opt in or revoke.
R010-P1-C072 A consumer may opt in at any time and revoke at any time through the means made available for consent. S004, § 17(f). Consumer Financial Protection Bureau Opt-in follows the notice’s manner; revocation access must reflect available consent methods. R.
R010-P1-C073 Revocation must be implemented as soon as reasonably practicable. S004, § 17(f). Consumer Financial Protection Bureau The section supplies no fixed number of days for this implementation. R; actual elapsed time and practicability unknown.
R010-P1-C074 Revocation alone does not require reversal of fees assessed before implementation of the revocation request. S004, comment 17(f)-1. Consumer Financial Protection Bureau Does not establish that earlier fees were lawful or excuse unreasonable implementation delay. O/I; separate grounds remain held.
R010-P1-C075 Consent continues until revoked by the consumer or the institution terminates the service. S004, § 17(g), comment 17(g)-1. Consumer Financial Protection Bureau Termination is possible; excessive use is the comment’s example. R/O; no actual termination or reconsent finding.

3.4 Effective triggers, repeal/withdrawal, and unresolved legal limits

Claim ID Precise claim / area Source and pinpoint Trigger, conditions, exceptions Status / limits
R010-P1-C076 The original final rule distinguished its effective date from its mandatory compliance date. S009, 74 FR 59033, index 0. govinfo.gov Effective January 19, 2010; mandatory compliance July 1, 2010, with the specific existing-account transition. H; historical regulatory dates, not individual deadlines.
R010-P1-C077 The 2010 clarification removed former (b)(4); its correction preserved the four subparagraph requirements by specifying amendment of the introductory text. S010, 75 FR 31671–31672; correction 33681. govinfo.gov+1 Both effective July 6, 2010. H; former (b)(4) is not a current fee exception.
R010-P1-C078 The 2011 rule recodified Regulation E into Part 1005 without new substantive obligations. S011, 76 FR 81020–81021. govinfo.gov Effective December 30, 2011; transfer of relevant rulemaking authority described as July 21, 2011. H; current duties come from current text.
R010-P1-C079 Accounts opened before July 1, 2010 were not permanently grandfathered out of opt-in. S004, § 17(c)(1). Consumer Financial Protection Bureau Covered fees assessed on or after August 15, 2010 require § 17(b)(1) compliance and affirmative consent. R; opening date/fee facts unknown.
R010-P1-C080 Accounts opened on or after July 1, 2010 require compliance and consent before covered fees are assessed. S004, § 17(c)(2), comment 17(c)-1. Consumer Financial Protection Bureau Also apply consent/payment and confirmation timing. R/O; no actual event-date calculation.
R010-P1-C081 Opt-in is not a waiver of all EFTA protections or every other fee limitation. S002, § 1693l; S004, § 17. uscode.house.gov+1 Statute preserves greater protection and expressly excepts a waiver given in settlement of a dispute or action. S/I; no settlement, enforceability, or remedy decision.
R010-P1-C082 The 2024 overdraft final rule originally stated an October 1, 2025 effective date. S012, 89 FR 106768 and § V. govinfo.gov+1 It was a final rule with a future effective date when issued. H/D; that planned date is not treated as having activated the disapproved rule.
R010-P1-C083 Public Law 119-10 disapproved the specifically identified 2024 final rule and gave it no force or effect. S013, 139 Stat. 53, entire operative sentence. govinfo.gov Approved May 9, 2025; identifies 89 FR 106768, December 30, 2024. S; exact enacted effect read.
R010-P1-C084 The disapproved rule’s added comment 17(a)-2 and new covered-overdraft framework cannot be used here as current requirements or exclusions. S012, 106837, index 69; S013; current S004. govinfo.gov+2 The preexisting Regulation Z-line exclusion still exists on its own terms. D/R/I; no new fee cap inferred from the disapproved rule.
R010-P1-C085 The CFPB resource page’s May 12 signing date conflicts with the enacted public law’s May 9 approval date. S014 featured paragraph; S013 heading and approval line. Consumer Financial Protection Bureau+1 This report uses May 9, 2025 for enactment/approval. Verified source discrepancy; resource date not substituted for statute.
R010-P1-C086 Circulars 2022-06 and 2024-05 are withdrawn guidance under the inspected official status materials. S015 register and 90 FR 20084–20086; S016 publisher pages. Consumer Financial Protection Bureau+4 Withdrawal applicable May 12, 2025. W; historical analyses not current-rule substitutes.
R010-P1-C087 Withdrawal of those circulars does not itself repeal the statute/regulation or affirmatively validate all fees discussed in them. S015’s specified withdrawal action; S002–S004. federalregister.gov+2 Distinguish guidance status from the continued text and scope of statutes/regulations. I from S/R/W; other legal grounds remain open.
R010-P1-C088 A stipulated compliant opt-in does not settle the full legality of an authorization-positive/settlement-negative fee. S004, § 17 and comment 17(b)-1.iv; C081, C086–C087. Consumer Financial Protection Bureau+2 Other applicable statutory, contract, disclosure, balance-method, and judicial questions need their own authority and facts. U; no current broader liability theory asserted.
R010-P1-C089 The generic rules cannot determine actual consent, causation, coding, contract compliance, liability, eligibility, or relief without facts not supplied and not searched. Analytical limit of C002–C088; user scope. All actual identity, account, balance, timing, agreement, and transaction facts remain blank. U; no individual or class-action determination.
R010-P1-C090 The checked current-resource labels and retrieved bodies support this bounded report, but do not certify all intervening legislation, publications, litigation, or current form pixels. S001–S018 and failure log. ecfr.gov+2 eCFR title currency through October 23; selected OLRC labels through October 20; older statutory recoveries; unread current image. U / methodological qualification; no component or parent closure.

4. Clearly hypothetical qualitative branches

These are anonymous legal branches, not accounts, consumers, institutions, or records. No names, identifiers, fee amounts, awards, individual dates, or filing deadlines are invented. “Evidence needed” identifies the type of unresolved fact, not a request or instruction to search for actual records.

Example Stipulated hypothetical facts Section-specific result and remaining unknown Evidence category needed Adverse misclassification to avoid
E01 — No opt-in; paid one-time debit All coverage predicates are stipulated; an account-holding FI pays a one-time debit-card overdraft; no affirmative consent exists. § 17 prohibits a fee for paying it. Principal debit authority is separately conditional on applicable law. C018, C029, C057, C066. Paid-item status, card relationship, channel, absence of consent, fee linkage. Treating payment itself as consent; treating the fee prohibition as automatic principal forgiveness.
E02 — Affirmative opt-in; other conditions unknown A separate affirmative choice is stipulated, but notice, opportunity, confirmation, and timing are unknown. Fee authority under § 17 is not established merely by that choice. C029–C039. No actual violation or remedy is adjudicated. Notice content/delivery, opportunity, confirmation, payment chronology, procedures. Collapsing four cumulative requirements into “a consent box exists.”
E03 — Recurring classification uncertain Debit-card payments recur in ordinary language, but advance authorization, further consumer action, coding, and adapted systems are unknown. Classification remains unresolved. C016, C061. Payment arrangement, initiation method, recurrence indicator, system adaptation/reliance. Calling every repeated merchant payment recurring, or disregarding the commentary’s conditional coding rule.
E04 — Paid check or ACH A transaction is stipulated to be a check or ACH debit, not an ATM/one-time card transaction; it is paid into overdraft. The specific ATM/one-time-card opt-in prerequisite does not by itself prohibit the fee. C008–C009, C054, C065, C067. Other law and contract remain unknown. Actual rail and paid status; fee type; governing contract. Treating all EFTs as debit-card transactions; treating absence of this prohibition as universal legality.
E05 — No consent; other negative-balance source No opt-in; the negative balance is stipulated to arise solely from a paid check or ACH transaction. Comments 17(b)-8 and -9 do not prohibit the described balance-based/ongoing fee merely because there was no ATM/debit opt-in. C064–C068. Complete causation and contract trigger. Assuming every negative balance without opt-in is fee-free.
E06 — Revoked consent A valid revocation has been implemented; a later covered one-time debit is paid. The prior consent no longer supplies the opt-in predicate for a fee on that payment. C029, C072–C075. Earlier fees are not automatically reversed solely by revocation. Revocation receipt, available methods, implementation, payment/fee events. Treating revocation as retroactive cancellation of every prior fee, or as ineffective indefinitely.
E07 — Linked credit excluded Payment is stipulated to occur pursuant to an overdraft line subject to Regulation Z. Excluded from “overdraft service” under § 17(a)(1). C019. Credit agreement, APR, usury, origination, repayment, and other protections remain held. Nature of credit line and funding mechanism. Applying the § 17 opt-in rule as the complete law of the credit line.
E08 — Mixed transactions No opt-in; protected card and check/ACH debits contribute to a continuing negative balance. The protected card payment cannot carry its own unconsented overdraft fee. A separate ongoing fee requires the mixed-balance analysis and the nonprotected payment-date anchor. C064–C070. Debit sequence, deposits/credits, allocation, associated fees, residual balance, fee period. Letting one check validate all card fees; using the earliest card overdraft as the sustained-fee start.
E09 — Positive authorization; negative settlement; no opt-in Covered one-time debit authorized when funds are believed sufficient; intervening activity leaves insufficient funds at settlement; no required opt-in. The current comment expressly prohibits the fee for paying that transaction. C062–C063. Authorization/settlement facts and consent status. Treating a general decline policy or positive authorization as an exception.
E10 — Positive authorization; negative settlement; opt-in stipulated All § 17 opt-in steps are stipulated satisfied; authorization and settlement balances differ. This pass does not conclude that the fee is lawful or unlawful under all applicable law. C081, C086–C088. Actual balance methodology, contract/disclosures, causation, independently applicable authority. Using withdrawn Circular 2022-06 as current operative law, or treating its withdrawal as a universal permission.
E11 — Returned unpaid / NSF The underlying item is stipulated to have been returned unpaid. Classify the charge as a returned-item/NSF issue; the paid-overdraft fee rule alone does not decide it. A separate fee-collection EFT can implicate § 3(b)(3). C026–C027. Returned/paid disposition; who assessed/collected the fee; collection method. Calling an unpaid item a paid overdraft; confusing a merchant fee EFT with the FI’s own fee entry.
E12 — General agreement or account use only The only stipulated acts are signing general account terms and using the account; no separate affirmative choice is stipulated. Those acts do not establish the required separate opt-in. C034–C036. Dedicated consent act and associated disclosure sequence. Importing “use constitutes authorization” from a different rule.
E13 — Joint-holder revocation A joint consumer revokes existing opt-in, with implementation stipulated. Revocation operates for the account under § 17(e). C052, C071–C075. Joint relationship and revocation chronology. Requiring every joint holder to revoke, or treating one disclosure copy as every holder’s affirmative consent.
E14 — Prepaid negative balance A product is called prepaid and has a negative asset balance; credit access, issuer relationships, decline policy, and fee conditions are unknown. Neither § 17(a)(4) exclusion is established from the label or negative balance alone. C017, C022–C024. Defined prepaid status; feature structure; issuer/affiliate/business-partner relationship; authorization policy; fee predicates. Applying the prepaid exception to ordinary checking accounts or ignoring its no-prohibited-fee conditions.
E15 — ATM access fee A non-account-holding ATM operator discloses its access fee and the consumer continues. Analyze that operator fee under § 16; this does not itself establish § 17 overdraft consent to the account-holding FI. C028–C034. Fee actor, fee purpose, screen/paper notice, separate overdraft process. Treating acceptance of an ATM surcharge as overdraft opt-in.

5. Blank generic document-audit worksheet

This is a blank analytical worksheet. It contains no actual or fictional identity entries. It does not authorize obtaining records, contacting anyone, submitting a form, or changing an account.

Field Generic question / document attribute Entry Claim / example links
W01 Product purpose Is the asset account established primarily for personal/family/household or business purposes? — C002–C003
W02 Account category Checking/share draft/savings/prepaid/trust/other; which exact definition and exclusion governs? — C003, C017–C024
W03 Actor role Account holder, card issuer on its behalf, separate card issuer, ATM operator, merchant/payee, creditor, transfer-service actor? — C004–C006, C028, C053, C059
W04 Geographic predicate Account location and relevant statutory/regulatory residence/location predicates? — C015
W05 EFT agreement What generic agreement establishes EFT services, and which party’s agreement is relevant? — C006
W06 Transaction rail/channel ATM, one-time card, recurring card, ACH, check, converted check, wire, internal transfer, other? — C007–C016, C060–C061
W07 Recurring classification Advance authorization, substantially regular intervals, and further consumer action? — C016; E03
W08 Coding reliance Classification indicator, system adaptation, and basis for reliance on third-party coding? — C061; E03
W09 Card relationship Was the debit device issued by or on behalf of the account-holding institution? — C059
W10 Payment disposition Was the underlying item actually paid, declined, reversed, or returned unpaid? — C018, C026–C027; E11
W11 Authorization/settlement Relevant authorization and payment/settlement events; what does the operative rule actually answer? — C038–C039, C063, C088
W12 Balance methodology Ledger/available balance definitions, holds, unsettled items, posting order, reversals, and intervening credits? — C018, C063–C070, C088
W13 Notice version/content Service, transaction types, all fees, variable maxima, fee count, consent methods, offered alternatives, permitted additions? — C040–C047
W14 Notice separation Is the notice segregated from other information and the consent choice separate from other acknowledgments? — C030, C034, C050
W15 Delivery/retention Written or agreed electronic delivery; clear, understandable, retainable form; relevant language availability? — C030–C032, C051
W16 Opportunity What reasonable method and opportunity for affirmative choice were provided? — C033, C036
W17 Consent act What dedicated affirmative act occurred, and when was it received? — C034–C039
W18 Confirmation Written/agreed electronic confirmation, revocation statement, mailing/delivery event, reasonable procedures? — C037–C038
W19 Joint relationship Which joint-holder rule applies to disclosure, opt-in, or revocation? — C052, C071
W20 Revocation Method, receipt, implementation, practicability, and any later valid opt-in? — C072–C075
W21 Fee classification Per-item payment fee, balance-tier fee, daily/sustained fee, NSF, returned-deposit fee, transfer fee, credit charge, ATM surcharge, other? — C025–C028, C042–C043, C064–C070
W22 Fee causation Which paid transaction or remaining negative-balance components caused the particular fee? — C064–C069
W23 Mixed-balance allocation How do posting order, later deposits, associated fees, credits, and reversals affect residual attribution? — C068–C070; E08
W24 Fee period and trigger Disclosed contractual period; calendar or business-day units; starting event; continuing-balance condition; applicable exclusions? — C042, C068–C069
W25 Linked arrangement Reg Z line, own-account transfer, securities credit, qualifying prepaid feature, or another mechanism? — C019–C025
W26 Other account terms Same pricing/features and payment criteria regardless of opt-in; independent basis for any limited-feature product? — C054–C056
W27 Unresolved governing facts State/country/tribal status, contract terms, other legal limits, benefit protections, security/setoff, and other parent dimensions? — C081, C088–C090; parent holds

Period versus calculation: W24 records a disclosed period and its trigger. It does not calculate a calendar date. No individual deadline or fee arithmetic was necessary or performed. The numerical amounts and timing assumptions embedded in official examples and A-9 were not converted into legal caps, mandatory grace periods, or actual obligations.

6. Granular coverage table

Answered means the generic rule is answered within the cited read bounds. It does not mean an actual transaction, component, state, or parent assignment has been accepted. Partial distinguishes source-retrieval limits from deliberately unavailable facts.

Assigned subquestion / branch Coverage Claim / example links Exact missing authority or facts Next bounded permissible investigation
1.a Enabling EFTA authority Partial: substantive text read; currentness gap C001; S001, S003, S011 Current OLRC §§ 1693a–b bodies and complete later session-law lag audit. Recover current official statutory text and check only relevant published amendments.
1.b Consumer versus business account Answered generically C002–C003 Actual primary purpose and account arrangement. No actual-record inquiry authorized; maintain fact hold.
1.c Bank/credit-union/other FI coverage Answered generically C004–C005, C053, C059 Actual account-holder/issuer roles and any statutory excluded-person predicates. Published definition clarification only; no institution/license search.
1.d EFT-service agreement gateway Answered generically C006–C009 Actual agreement, notice of third-party arrangement, transfer initiation. Maintain fact hold.
1.e Necessary EFT exclusions Answered within relevant clauses C008, C010–C014 Actual rail, purpose, within-institution relationship, qualifying assets/plan. Narrow public authority follow-up only if a specific legal ambiguity becomes material.
1.f Geographic scope Answered at federal gateway; broader scope held C015 Actual account location/residence; non-U.S. law. No country-wide or international closure; separate bounded law review only.
1.g Covered paid overdraft definition Answered generically C018 Paid status, insufficient/unavailable funds, fee cause, account-holding actor. Maintain fact hold.
1.h Linked credit/own-account transfer/securities exclusions Answered generically C019–C021; E07 Actual mechanism and agreement. No credit-product or provider search.
1.i Prepaid exclusion Answered as conditional gate; product taxonomy partial C017, C022–C024; E14 Product facts; remote incorporated benefits/gift/tax definitions; historical prepaid-date chain. Follow only a material published cross-reference; no full prepaid/credit closure.
1.j Actual coding/classification Unresolved facts C016, C059–C061; E03 Actual coding, adapted systems, reliance, recurring authorization. No actual transaction search authorized.
2.a Complete § 17 notice/consent/confirmation/revocation text Answered; full section/comments read C029–C047, C071–C080; S004 Actual compliance facts only. No additional generic authority needed for the stated text.
2.b Segregated notice and separate choice Answered generically C030, C034–C036, C050; E12 Actual presentation, dedicated choice, preselection. Maintain fact hold.
2.c Reasonable opportunity and methods Answered generically C033, C036, C044 Actual opportunity and available methods. Maintain fact hold.
2.d Electronic delivery and retainability Answered with authority-type distinction C030–C032, C037 Actual delivery agreement/retention; independent requirements for other documents. Any further E-Sign work must identify the distinct legally required disclosure.
2.e Confirmation timing Answered generically C037–C039; E02 Mailing/delivery, consent receipt, transaction payment, reasonable procedures. Maintain fact hold; no invented receipt deadline.
2.f Complete required notice content Answered generically C040–C047 Actual fees, service policies, alternatives, tailored text. Compare only a permissible generic blank form if later needed.
2.g Current A-9 body/image Partial source retrieval C049; S005–S006, S011 Current image pixels and complete current image transcription not obtained. Obtain readable official current form through permitted public tools; no access workaround.
2.h Historical A-9 and current instructions Answered within read bounds C040–C049 Historical-to-current visual comparison remains unverified. Preserve distinction between historical parsed text and current image.
2.i Revocation, joint holders, duration Answered generically C071–C075; E06, E13 Actual joint status and event chronology. Maintain fact hold.
2.j Effective dates and existing accounts Answered for § 17 transition/recodification C076–C080 Actual opening and payment dates. No individual calendar calculation.
3.a Complete fee prerequisite Answered generically C029, C057–C063 Actual satisfaction of coverage and four conditions. Maintain fact hold.
3.b No conditioning of other overdrafts Answered generically C054 Actual payment criteria and reason for decline. No institutional practice investigation.
3.c Same terms/features Answered generically C055–C056 Actual comparative terms and independent eligibility. No creditworthiness or account-eligibility decision.
3.d Payment discretion versus fee authority Answered generically C057–C058; E01 Applicable principal-debit law and contract remain unknown. Preserve setoff/collection/contract holds.
3.e Checks/ACH/recurring versus one-time card Answered generically; classification facts unresolved C008–C016, C059–C061; E03–E04 Actual channel and recurring predicates. Maintain fact hold.
3.f Balance-amount fees Answered generically C064–C065; E05, E08 Actual balance components and fee basis. No ledger reconstruction authorized.
3.g Daily/sustained/negative-balance fees Answered generically C066–C070 Actual continuing attribution, contractual period, deposits and allocations. Maintain fact hold; no universal period inferred.
3.h Mixed-balance timing Answered generically C068–C070; E08 Nonprotected payment date, period units, residual source. Only generic further interpretation; no individual deadline.
3.i Opt-in and other limits Answered as limitation C081, C088 Broader governing law/contract and any settlement context. Preserve parent holds.
4.a Authorization-positive/settlement-negative without opt-in Answered by current comment C062–C063; E09 Actual predicates, if any. No withdrawn guidance needed.
4.b Authorization-positive/settlement-negative with compliant opt-in Unresolved broader legal basis C088; E10 Independently applicable law, balance/disclosure/contract facts. If later necessary, inspect only material published primary authority; no docket query.
4.c Withdrawn-guidance checks Answered for every circular used for status C086–C087; S015–S016 No broader guidance-universe audit asserted. Recheck official register only if another guidance item becomes necessary.
4.d 2024/2025 final-rule disapproval Answered for authority actually implicated C082–C085; S012–S014 Full unrelated provisions of disapproved rule not examined. No need to revive its framework; retain exact statutory effect.
4.e Paid versus returned/unpaid, NSF Answered as distinction; broader law excluded C026–C027; E11 Actual disposition, actor and collection method; substantive NSF law. Separate generic NSF component if later assigned.
4.f Deposit advance, linked credit, setoff Partial by intentional scope C019–C025; E07 Credit/security/setoff contracts and broader legal authority. Preserve separate lending/setoff dimensions.
4.g Published opinions/later litigation status Excluded from conclusions; no case holding needed here C088–C090 No majority-opinion holding or later-history audit performed. Only material published opinions if later strictly necessary; no case-record/docket-status query.
5.a Blank audit worksheet Delivered W01–W27 All entries intentionally blank. No records request or identifier entry.
5.b No-opt-in paid one-time branch Delivered E01; C029, C057 Actual facts not supplied. None within this published-source pass.
5.c Affirmative consent, other conditions unknown Delivered E02; C029–C039 Notice/opportunity/confirmation/timing facts. Maintain hold.
5.d Recurring classification branch Delivered E03; C016, C061 Classification/coding/system facts. Maintain hold.
5.e Check or ACH branch Delivered E04; C008–C009, C054 Channel and contract facts. Maintain hold.
5.f No consent, other negative source Delivered E05; C064–C068 Causation and fee trigger. Maintain hold.
5.g Revoked-consent branch Delivered E06; C072–C075 Receipt/implementation/payment chronology. Maintain hold.
5.h Linked-credit exclusion branch Delivered E07; C019 Actual Reg Z credit arrangement. Preserve credit-law holds.
5.i Mixed-transactions branch Delivered E08; C064–C070 Complete component allocation and timing. Maintain hold.
5.j Authorization/settlement branch Delivered in two distinct forms E09–E10; C063, C088 With-opt-in broader legal basis remains unresolved. No universal APSN conclusion.
Standards: current statutory/body/edition completeness Partial C090; failure log Current bodies for identified statutes; complete intervening-publication audit. Public primary-source recovery only.
Standards: UI/model provenance Unverified beyond session identity Opening provenance statement Frontend and selector evidence unavailable. No claim of unseen UI verification.
Parent/operational/publication acceptance Excluded Parent holds below No authority or factual basis for acceptance/closure requested. Preserve all holds; no operational action.

7. Question → claim/source crosswalk

User assignment Principal claims Principal sources Delivered examples / audit
1. EFTA/Reg E consumer, account, institution, transfer coverage and exclusions C001–C028, C059–C061 S001, S003–S004, S007, S017 E03–E04, E07, E11, E14–E15; W01–W12, W25
2. Complete notice, separate content/form, consent, confirmation, revocation, model, dates C029–C053, C071–C080 S003–S006, S008–S011 E02, E06, E12–E13; W13–W20
3. Fee prohibition, conditioning, same terms, discretion, mixed-balance causation C029, C054–C075, C081 S002–S004, S010 E01, E04–E08; W21–W26
4. Authorization/settlement, guidance withdrawal, repeal, unpaid/NSF/credit/setoff distinctions C019–C028, C062–C063, C082–C090 S003–S004, S007, S012–S017 E07–E11, E14–E15; W10–W12, W21–W25
5. Blank audit and qualitative branches C089–C090 and branch-specific claims above Source-linked claim register W01–W27 and E01–E15
Standards and parent holds C049, C081–C090 Source table and read/failure log Coverage table, self-check, parent holds

8. Read and failure log

8.1 Actual read bounds

Log item What was actually read What was not represented as read
L01 — Current § 17 Entire operative § 17(a)–(g), all embedded official interpretations, all three mixed-balance examples, and the alternative method. Annual § 17 PDF text also read in full. No claim that the whole of Regulation E, all related regulations, or all annual-CFR pages were read.
L02 — Necessary gateway Relevant § 2 definitions; complete § 3 coverage/exclusion text and relevant interpretations; complete § 4; complete § 16 for the ATM-operator distinction. No full error-resolution, unauthorized-transfer-loss, benefits, remittance, gift-card, or state-law investigation.
L03 — Linked/prepaid exclusions Necessary § 1026.3(d) and § 1026.61 definition/exception text, including negative-balance conditions and business-partner exception. No comprehensive Regulation Z, APR, origination, security, repayment, or credit-account compliance review.
L04 — A-9 Current heading/link and current § 17(d)/Appendix A instructions; complete parsed historical one-page A-9; 2011 statement of substantive continuity. No current A-9 pixels seen. No claim of complete current-image transcription or visual comparison.
L05 — Final-rule dates and explanations Necessary 2009 dates/electronic-delivery explanation; relevant 2010 clarification passages and complete correction; 2011 recodification/A-9 passage. Not every page of each historical preamble. Historical provisions superseded by later clarification were not treated as current.
L06 — Disapproval Complete Public Law 119-10; the 2024 rule’s stated effective date, necessary discussion, and complete added § 17(a)-2 comment; agency status paragraph. Not the entire 78-page disapproved rule or a broader Congressional Review Act reissuance analysis.
L07 — Withdrawal Official register, operative withdrawal discussion, relevant listed circulars, and publisher-page identification/scope passages. No wholesale adoption of historical circular analyses or their cited cases; no assumption that a live URL means current guidance.
L08 — Statutes Official 2024 §§ 1693a–b and § 5519 recovery bodies; current-labeled § 1693l and § 7001 bodies. No claim that annual recovery text or a compilation header establishes complete current session-law status.
L09 — Images and screenshots Parsed PDF text and image-link metadata only. PDF text is not pixels. Placeholder image results and the failed A-9 screenshot were not counted as image inspection.
L10 — Discovery exclusions Search results were used to locate permitted primary bodies. Search snippets, headnotes, secondary reports, proposed-rule summaries, incidental case/entity results, and unopened prototype forms were not substantive foundations. No actual-case search was pursued.

8.2 Material retrieval failures and recoveries

Repeated attempts at the same source are consolidated. These are retrieval gaps, not findings that a rule does not exist.

Failure ID / source Complete requested URLs or identified failed representation Result and bounded consequence
F01 / S001 — Current § 1693a https://uscode.house.gov/view.xhtml?req=granuleid:USC-prelim-title15-section1693a&num=0&edition=prelim ; https://uscode.house.gov/view.xhtml?req=%28title%3A15+section%3A1693a+edition%3Aprelim%29 ; https://uscode.house.gov/us/usc/119-134/t15/s1693a/ ; https://uscode.house.gov/us/usc/119-124/t15/s1693a/ ; https://uscode.house.gov/us/usc/119-121/t15/s1693a/ ; https://www.govinfo.gov/content/pkg/USCODE-2025-title15/html/USCODE-2025-title15-chap41-subchapVI-sec1693a.htm Returned combinations of 404, page-not-found, disabled/inaccessible results. Recovered official 2024 body, S001. Current statutory lag remains unresolved.
F02 / S001 — Current § 1693b https://uscode.house.gov/view.xhtml?req=granuleid:USC-prelim-title15-section1693b&num=0&edition=prelim ; https://uscode.house.gov/us/usc/119-134/t15/s1693b/ ; https://uscode.house.gov/us/usc/119-124/t15/s1693b/ ; https://uscode.house.gov/us/usc/119-121/t15/s1693b/ ; https://uscode.house.gov/us/usc/t15/s1693b/ ; https://www.govinfo.gov/content/pkg/USCODE-2025-title15/html/USCODE-2025-title15-chap41-subchapVI-sec1693b.htm ; https://www.govinfo.gov/content/pkg/USCODE-2024-title15/html/USCODE-2024-title15-chap41-subchapVI-sec1693b.htm 500/inaccessible responses. Recovered official 2024 PDF body, S001. No inference of missing authority.
F03 / S001 — Current chapter fallback https://uscode.house.gov/view.xhtml?edition=prelim&req=granuleid%3AUSC-prelim-title15-chapter41-subchapter6 404. Did not close statutory-currentness gap.
F04 / S002 — § 1693l path and repeat retrieval https://uscode.house.gov/view.xhtml?req=granuleid:USC-prelim-title15-section1693l&num=0&edition=prelim ; https://uscode.house.gov/us/usc/119-134/t15/s1693l/ Old path failed; modern body initially succeeded. One direct repeat failed; reopening the retrieved reference again returned the complete body. Recovered, with header limit preserved.
F05 / S017 — Current § 5519 https://uscode.house.gov/view.xhtml?req=granuleid:USC-prelim-title12-section5519&num=0&edition=prelim ; https://uscode.house.gov/us/usc/119-134/t12/s5519/ ; https://uscode.house.gov/us/usc/t12/s5519/ 404/inaccessible. Recovered 2024 official body, S017. No actual excluded-person determination.
F06 / S004 — Fixed annual § 17 URL https://www.govinfo.gov/content/pkg/CFR-2026-title12-vol8/pdf/CFR-2026-title12-vol8-sec1005-17.pdf Fixed path inaccessible. Recovered complete 2026 § 17 through the Govinfo link URL in S004.
F07 / S005, S011, S018 — Current A-9 representation Current PNG and appendix URLs in S005; embedded graphic in S011; full-part annual PDFs in S018. Current image returned a placeholder; appendix extraction supplied heading but not full form body; PDF extraction omitted the graphic text. Current pixels/full-image transcription remain unverified. Historical parsed model recovered through S006.
F08 / S018 — Large 2026 CFR PDF Both 2026 full-part URLs in S018. Initial header/text success followed by targeted find/open timeouts. No full-part body-read claim.
F09 / S004, S006, S013 — Screenshots § 17 PDF indices 0–2; public law index 0; historical A-9 index 0. Earlier calls supplied image placeholders without inspectable image content. The historical A-9 screenshot returned an inability-to-resolve/screenshot-not-enabled error despite parsed PDF availability. No pixel-read claim.
F10 — Search-domain restriction Search service reported a non-retryable robots restriction for https://www.congress.gov/ during generic legislative discovery. No workaround attempted. The enacted public-law body was read from Govinfo, S013; no Congress.gov body is claimed read.

9. Self-check — NOT independent review

Check Result
Independent primary-source investigation, without prior-report foundation Performed. No unreviewed Library report or prior chat was used.
Complete focused § 1005.17 operative text and official interpretations Read, including exclusions, all four conditions, notice content, conditioning, same terms, joint relationships, revocation, duration, and mixed-balance examples.
Statute versus regulation versus official interpretation versus guidance Separated in source and claim statuses.
Current, historical, future-effective, disapproved, withdrawn, unknown Separated. The 2024 rule’s planned effective date was not treated as operative; withdrawal was not treated as statutory repeal.
Current A-9 image read Not achieved. Historical parsed text and current instructions are explicitly distinguished from current pixels.
Current statutory/edition/session-law audit Partial. Identified current-body failures and older official recoveries are preserved.
Fee-causation reasoning Qualified. Per-item, amount-based, ongoing, mixed-source, and returned-item branches are separated.
Authorization/settlement treatment Bounded. No-opt-in example answered from the current comment; broader with-opt-in legality held.
Numerical integrity No invented fees, awards, or deadlines. Regulatory thresholds stated are sourced; no individual arithmetic performed.
Actual-record, entity, identifier, or docket investigation None conducted.
Individual liability, class eligibility, standing, remedies, filing advice No determination made.
Component, state, parent, operations, or publication acceptance None given.

10. Specific parent holds preserved

The following remain outside any closure or acceptance:

  • Actual facts: consumer status; account purpose and type; actor roles; account/card relationship; EFT agreement; consent; delivery; confirmation; revocation; payment; authorization and settlement; recurring classification and coding; system adaptation; ledger/available balances; posting order; deposits, reversals and allocations; fee causation; contract terms; and linked arrangements.
  • Full Regulation E protections: complete error-resolution procedures, unauthorized-transfer loss allocation, and other disclosure, preauthorized-payment, compulsory-use, benefit-account, remittance, and record-retention issues beyond the narrow provisions needed here.
  • Credit and lending: unsecured installments, open-end lines, credit-union lending, deposit-secured borrowing, deposit advances, online lending, loan origination, underwriting, APR, finance charges, usury, credit agreements, repayment, and broader Regulation Z obligations.
  • Other deposit and payment law: broader overdraft and NSF restrictions; returned payments and returned deposited items; deposit disclosure law; account agreements; security interests; setoff; protected benefits; and any separate federal unfairness, deception, or other statutory theory.
  • Jurisdictions: state, local, tribal, territorial-specific, and international law; actual choice-of-law and country facts.
  • Enforcement and consequences: collections, settlement, limitations, standing, remedies, litigation, published-opinion later history, court filing, class eligibility, awards, tax, and insolvency.
  • Source/provenance limits: current A-9 pixels; the identified current statutory-body and publication-lag gaps; and unverified frontend/model-selector provenance.

This report supplies the focused generic rules and expressly bounded conclusions for R010 PASS-01. It makes no operational, publication, component, state, or parent acceptance determination.

END R010 PASS-01

Every captured table

Captured cells with original header handling and explicitly labeled bounded correction overlays. Downloaded JSON retains original cells. Tables may contain source limitations, historical examples and identified corrections; the complete reading supplies context.

Read the evidence with its boundaries. These are saved research components, including revisions. A scoped coordinator review checks selected evidence; it does not certify every claim, a complete jurisdiction, current law or individual applicability. Dates and access limits remain attached to the records.

How to read the research →

Captured table 01

Source ID · Issuer/title and complete literal HTTPS URLs · Exact provisions; printed page / PDF index · 8 data rows

Source IDIssuer/title and complete literal HTTPS URLsExact provisions; printed page / PDF indexVersion, effective predicate, statusFresh-read extent and currentness limits
R010-P1-S001Congress; GPO, EFTA definitions and rulemaking authority. https://www.govinfo.gov/content/pkg/USCODE-2024-title15/html/USCODE-2024-title15-chap41-subchapVI-sec1693a.htm ; https://www.govinfo.gov/content/pkg/USCODE-2024-title15/pdf/USCODE-2024-title15-chap41-subchapVI-sec1693b.pdf§ 1693a operative definitions, especially (2), (6)–(11); § 1693b(a)–(e), particularly (a)–(d). PDF pp. 1645–1648, indices 0–3; its first page also contains the end of § 1693a.Official 2024 Edition bodies. Statutory authority and definitions; not a representation of a fully audited October 2026 statutory edition.Fresh, body read. Current OLRC versions of §§ 1693a–b failed; recovery was the official 2024 edition. 2025–2026 statutory lag remains open. COMMERCE AND TRADE +2
R010-P1-S002Congress; OLRC, 15 USC 1693l—Waiver of rights. https://uscode.house.gov/us/usc/119-134/t15/s1693l/Entire operative paragraph and source credit; HTML, page/index N/A.Header states laws in effect through PL 119-134, October 20, 2026. Applies to agreements waiving EFTA rights, with express exceptions.Fresh, complete operative paragraph read. A direct repeat retrieval failed; reopening the previously retrieved reference recovered the body. Compilation label is not a session-law lag audit. uscode.house.gov
R010-P1-S003CFPB, Regulation E gateway, general disclosures, and ATM-operator distinction. https://www.consumerfinance.gov/rules-policy/regulations/1005/1/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/2/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/3/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/4/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/16/§ 1(a)–(b); necessary § 2 definitions, including (a), (b), (e), (f), (h), (i), (k), (l), with relevant comments; § 3(a)–(c) and embedded interpretations; § 4(a)–(d) and comments; § 16(a)–(d). HTML, page/index N/A.Agency pages labeled current regulation. Scope and exceptions depend on the account, actor, agreement, transfer, and product.Fresh bodies read. Full § 2(b)(3) text was read, but its remote tax, benefits, and gift-card cross-references were not comprehensively followed. Full error-resolution, unauthorized-transfer, remittance, and broader disclosure regimes were not examined. Same Part 1005 as S004–S005, not independent corroboration. Consumer Financial Protection Bureau +6
R010-P1-S004CFPB/OFR/GPO, 12 CFR 1005.17—Requirements for overdraft services, and official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1005/17/ ; https://www.ecfr.gov/current/title-12/chapter-X/part-1005/subpart-A/section-1005.17 ; https://www.govinfo.gov/link/cfr/12/1005?link-type=pdf&sectionnum=17&year=mostrecentEntire § 17(a)–(g) and all embedded § 17 official comments, including 17(b)-9.ii.A–C and -9.iii. Annual PDF pp. 204–206, indices 0–2, § 17 only.CFPB current label; latest eCFR read displayed Title 12 through 2026-10-23 and described eCFR as authoritative but unofficial. PDF resolves to 1-1-26 Edition, source note 76 FR 81023, amended 81 FR 84328. Historical § 17(c) triggers remain printed in current text.Fresh, complete necessary operative section and interpretations read. Annual PDF parsed text read; screenshots did not yield inspectable pixels. No full post-October-23 publication-lag audit. These are reproductions of one regulatory instrument. ecfr.gov +5
R010-P1-S005CFPB/OFR, Current Appendix A, Model A-9, and Appendix A interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1005/a/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/interp-a/ ; https://files.consumerfinance.gov/f/ER27DE11.000.png ; https://www.ecfr.gov/current/title-12/chapter-X/part-1005/appendix-Appendix%20A%20to%20Part%201005A-9 heading and linked graphic; Appendix A comments 1–3; complete A-9-specific instructions in § 17(d) and comments 17(d)-1–5, S004. HTML/PNG; printed page/index N/A.Current agency appendix presentation; eCFR appendix currency label through 2026-10-23.Fresh, partial form read. Current instructions and appendix comments read. Current graphic returned an image placeholder, not visible pixels or complete extracted form text. Current visual form comparison remains unresolved. Consumer Financial Protection Bureau +3
R010-P1-S006Federal Reserve, generic Model A-9 distributed with the 2009 final rule. https://www.federalreserve.gov/newsevents/pressreleases/files/bcreg20091112a3.pdf ; discovery page: https://www.federalreserve.gov/newsevents/pressreleases/bcreg20091112a.htmComplete one-page form body, parsed lines 0–35; unpaginated, PDF index 0.Historical November 12, 2009 distribution. S011 expressly describes the 2011 A-9 as substantively identical except “website” spelling.Fresh, complete parsed historical form text read; pixels not read. PDF metadata labels it an opt-out form, but the actual body and publisher link identify the relevant A-9 consent form; metadata was not substituted for the body. Illustrative fees and periods are not legal limits. Press release used for discovery, not operative dates. federalreserve.gov +2
R010-P1-S007CFPB, Regulation Z cross-references necessary to § 17(a). https://www.consumerfinance.gov/rules-policy/regulations/1026/3/ ; https://www.consumerfinance.gov/rules-policy/regulations/1026/61/§ 1026.3(d), comment 3(d)-1; § 1026.61(a)(1)–(5), especially (a)(2), (a)(4), (a)(5)(iii)(D), and necessary embedded comments. HTML, page/index N/A.Agency current-regulation presentation. Applied only to the exclusions expressly incorporated by § 17(a).Fresh, necessary definition/exception bodies read. Full Reg Z lending, APR, origination, repayment, security, and remedy regimes remain held. Historical prepaid-effective-date chain was not comprehensively audited; no historical product application is made. Consumer Financial Protection Bureau +7
R010-P1-S008Congress; OLRC, 15 USC 7001—E-Sign general rule. https://uscode.house.gov/us/usc/119-134/t15/s7001/§ 7001(a), (b), (c)(1)–(6); additional text and effective-date notes also returned. HTML, page/index N/A.Header through PL 119-134, October 20, 2026. § 7001(c) concerns information legally required in writing; see S009 for the § 17-specific adopting explanation.Fresh, complete relevant subsections read. Used to distinguish the general statute from the special overdraft disclosure treatment, not to create an extra § 17 consent condition. Compilation-lag qualification retained. uscode.house.gov
Source links captured in this table

Captured table 02

Source ID · Issuer/title and complete literal HTTPS URLs · Exact provisions; printed page / PDF index · 10 data rows

Source IDIssuer/title and complete literal HTTPS URLsExact provisions; printed page / PDF indexVersion, effective predicate, statusFresh-read extent and currentness limits
R010-P1-S009Federal Reserve, Electronic Fund Transfers—2009 final rule and official staff commentary. https://www.federalregister.gov/documents/2009/11/17/E9-27474/electronic-fund-transfers ; https://www.govinfo.gov/content/pkg/FR-2009-11-17/pdf/E9-27474.pdf74 FR 59033–59056, 24-page PDF, indices 0–23. Relevant read: dates at 59033 / 0; notice discussion and complete footnote 32 at 59041–59042 / 8–9; confirmation discussion 59043 / 10.Published 2009-11-17; effective 2010-01-19; mandatory compliance 2010-07-01, with existing-account treatment in § 17(c). Historical adopting rule; subsequently clarified and recodified.Fresh, selected necessary body passages read, not a claimed full 24-page read. Official PDF verified the electronic-delivery explanation. Original former § 205.17(b)(4) is not used as current text. govinfo.gov +3
R010-P1-S010Federal Reserve, 2010 clarification and correction. https://www.federalregister.gov/documents/2010/06/04/2010-13280/electronic-fund-transfers ; https://www.govinfo.gov/content/pkg/FR-2010-06-04/pdf/2010-13280.pdf ; https://www.federalregister.gov/documents/2010/06/15/2010-14353/electronic-fund-transfers ; https://www.govinfo.gov/content/pkg/FR-2010-06-15/pdf/2010-14353.pdf75 FR 31665–31673, indices 0–8: scope/confirmation discussion, balance-fee discussion, content instructions, and amendatory text. Correction at 33681 / index 0, operative correction fully read.Both effective 2010-07-06. Clarification removes former (b)(4); correction specifies revision of the (b)(1) introductory text, preserving the subparagraph requirements.Fresh, selected relevant clarification passages and complete correction read. Current complete comments are independently read as the same regulation in S004. Historical PDF’s final page also contains another rule, which is not adopted as a foundation. federalregister.gov +4
R010-P1-S011CFPB, Electronic Fund Transfers—2011 recodification. https://www.govinfo.gov/content/pkg/FR-2011-12-27/pdf/2011-31725.pdf76 FR 81020–81058, 39 pages. Necessary read at 81020–81021 / indices 0–1: transfer, recodification, effective date, A-9 change.Interim final rule; effective 2011-12-30. Rulemaking transfer described as effective 2011-07-21. No new substantive obligations asserted by this recodification.Fresh, selected body read. A-9 continuity passage fully read. The embedded A-9 graphic was not visually inspected; its exact graphic-page location is not asserted. Not merely a proposal. govinfo.gov
R010-P1-S012CFPB, Overdraft Lending: Very Large Financial Institutions. https://www.federalregister.gov/documents/2024/12/30/2024-29699/overdraft-lending-very-large-financial-institutions ; https://www.govinfo.gov/content/pkg/FR-2024-12-30/pdf/2024-29699.pdf89 FR 106768–106845, 78 pages. Dates 106768 / 0; § IV discussion and § V timing 106816 / 48; complete added comment 17(a)-2 at 106837 / 69.Published 2024-12-30, stated effective 2025-10-01; disapproved before that date by S013.Fresh, selected provisions read, not all 78 pages. Used only to identify the exact disapproved change and original trigger. No proposed or disapproved framework is used as current authority. govinfo.gov +2
R010-P1-S013Congress, Public Law 119-10, S.J. Res. 18. https://www.govinfo.gov/content/pkg/PLAW-119publ10/pdf/PLAW-119publ10.pdf139 Stat. 53 / PDF index 0, entire one-page law.Approved 2025-05-09. Disapproves the specifically named 89 FR 106768 final rule and gives it no force or effect.Fresh, complete parsed law read. Screenshot yielded no inspectable pixels; the text body was fully available. No docket or litigation-status inference. govinfo.gov
R010-P1-S014CFPB, Overdraft Lending compliance resource/status page. https://www.consumerfinance.gov/compliance/compliance-resources/deposit-accounts-resources/overdraft-lending-very-large-financial-institutions/“Featured topic” paragraph; HTML, page/index N/A.Page modified 2025-07-01. Says the final rule has no force/effect and remaining Reg E/Z remain unchanged.Fresh status paragraph read. Its statement that signing occurred May 12 conflicts with S013’s May 9 approval date. Public-law date controls this report. Resource label does not replace operative text. Consumer Financial Protection Bureau
R010-P1-S015CFPB, Withdrawn Guidance register and withdrawal notice. https://www.consumerfinance.gov/compliance/guidance/withdrawn-guidance/ ; https://www.federalregister.gov/documents/2025/05/12/2025-08286/interpretive-rules-policy-statements-and-advisory-opinions-withdrawal ; https://www.govinfo.gov/content/pkg/FR-2025-05-12/pdf/2025-08286.pdfRegister’s Circulars & Supervisory Guidance entries for 2024-05 and 2022-06; notice parts I–III and relevant entries. 90 FR 20084–20087, indices 0–3; applicability at 20084 / 0, operative withdrawal discussion 20085 / 1, relevant list 20086 / 2.Withdrawals applicable 2025-05-12. Register last-modified label 2026-07-22.Fresh register and necessary notice bodies read. Register and notice are one publisher’s status chain, not independent corroboration. Withdrawal is not treated as statutory repeal or a universal fee validation. Consumer Financial Protection Bureau +3
R010-P1-S016CFPB, historical circular publisher pages. https://www.consumerfinance.gov/compliance/circulars/consumer-financial-protection-circular-2022-06-unanticipated-overdraft-fee-assessment-practices/ ; https://www.consumerfinance.gov/compliance/circulars/consumer-financial-protection-circular-2024-05/Titles, questions/answers and relevant scope passages; HTML, page/index N/A. Register cites 87 FR 66935, Nov. 7, 2022, and 89 FR 80075, Oct. 2, 2024.Withdrawn, as verified against S015.Fresh, limited publisher-page read and status check. Not a full read of every cited authority. No historical enforcement/evidence theory is adopted as current operative law. Continued page availability is not currentness. Consumer Financial Protection Bureau +4
R010-P1-S017Congress; GPO, 12 USC 5519—Exclusion for auto dealers. https://www.govinfo.gov/content/pkg/USCODE-2024-title12/html/USCODE-2024-title12-chap53-subchapV-partB-sec5519.htmEntire operative (a)–(f), particularly jurisdictional exclusion, exceptions, preserved authorities, and definitions. HTML, page/index N/A.Official 2024 Edition recovery. Cross-reference in §§ 1005.2(i), 1005.3(a), and 1693b(a)(2).Fresh body read. Current OLRC retrieval failed. No dealer, license, entity, or business-line classification was attempted. Statutory lag remains held. BANKS AND BANKING
R010-P1-S018GPO, full Part 1005 recovery attempts. https://www.govinfo.gov/content/pkg/CFR-2025-title12-vol8/pdf/CFR-2025-title12-vol8-part1005.pdf ; https://www.govinfo.gov/content/pkg/CFR-2026-title12-vol8/pdf/CFR-2026-title12-vol8-part1005.pdf ; https://www.govinfo.gov/link/cfr/12/1005?link-type=pdf&year=mostrecent2025 A-9 location: printed 245 / index 60, heading but missing form-body extraction. 2026 full-part header/initial text retrieved; subsequent targeted retrievals timed out.Annual editions, not October 2026 complete currency guarantees.Fresh, partial/discovery/failure. No whole-part read claimed. Used to attempt form/text recovery, not independent authority beyond S003–S005.
Source links captured in this table

Captured table 03

Claim ID · Precise claim / area · Source and pinpoint · 28 data rows

Claim IDPrecise claim / areaSource and pinpointTrigger, conditions, exceptionsStatus / limits
R010-P1-C001EFTA supplies rulemaking authority for Regulation E; the specific overdraft opt-in conditions are in § 1005.17.S001, § 1693b(a)–(c); S003, § 1005.1(a); S011, 81021. govinfo.gov +2Bureau authority has statutory reservations, including Board authority described in § 1693b(a)(2).S/R; current statutory-body gap disclosed.
R010-P1-C002The relevant consumer/account gateway requires a natural person and an asset account established primarily for personal, family, or household purposes.S001, § 1693a(2), (6); S003, §§ 1005.2(b)(1), (e). COMMERCE AND TRADE +2Business-purpose accounts do not qualify merely because a natural person owns or uses them.S/R; actual purpose unknown.
R010-P1-C003The account definition excludes incidental credit balances in open-end credit plans and accounts held under bona fide trust agreements.S001, § 1693a(2); S003, § 1005.2(b)(1)–(2), comments 2(b)(2). COMMERCE AND TRADE +1Trust status depends on the actual arrangement and governing law; the comment supplies additional excluded-account examples.S/R/O; no actual account classification.
R010-P1-C004Banks, savings associations, and credit unions are included financial-institution classes; the regulation also includes specified other account holders and access-device issuers.S001, § 1693a(9); S003, § 1005.2(i). COMMERCE AND TRADE +1Direct/indirect holding, or access-device issuance plus agreement to provide EFT services, must fit the definition; statutory excluded-person clause remains.S/R; no named institution or charter inquiry.
R010-P1-C005The CFPA § 1029 cross-reference is a conditional jurisdictional exclusion, not a blanket statement that all auto-related activity is outside federal EFT law.S017, § 5519(a)–(c), (f); S001, § 1693b(a)(2). BANKS AND BANKING +1Predominant vehicle-dealer activity; exceptions for specified real-property services, retained direct retail credit/leases, and unrelated consumer financial services; other agency authorities preserved.S; 2024 body, later statutory lag and all entity facts held.
R010-P1-C006Regulation E account coverage requires an EFT-service agreement of the kind described in comment 3(a)-1.S003, § 1005.3(a), comments 3(a)-1–2. Consumer Financial Protection BureauConsumer–FI agreement, or consumer–third-party agreement with FI notice and transfers begun. ACH membership alone is insufficient.R/O; actual agreement unknown.
R010-P1-C007EFT coverage includes qualifying ATM, POS, debit-card, ACH, direct-deposit/withdrawal, telephone, and computer-initiated transfers.S003, § 1005.3(b)(1), comment 3(b)(1)-1. Consumer Financial Protection BureauMust instruct debit/credit of a covered consumer account and survive applicable exclusions.R/O; channel labels require facts.
R010-P1-C008A check converted into an ACH EFT differs from a check collected or re-presented electronically as a check.S003, § 1005.3(b)(2), comments 3(b)(1)-1.v and 3(c)(1)-1–2. Consumer Financial Protection Bureau +1Using check information to initiate ACH can be EFT; electronic re-presentment of the original check remains within the check exclusion.R/O; no transaction coding assumed.
R010-P1-C009Being an EFT does not by itself bring a transfer within the ATM/one-time debit-card fee prohibition.S003, § 1005.3(b); S004, § 1005.17(b)(1). Consumer Financial Protection Bureau +1The specific transaction must fit § 17’s channel and service conditions.I from R; one-time ACH is not automatically one-time debit card.
R010-P1-C010Fedwire and similar systems used primarily for interinstitutional or business transfers are excluded EFT channels under § 1005.3(c)(3).S003, § 3(c)(3), comments 1–3. Consumer Financial Protection BureauA subsequent ACH transfer to the consumer account can still be covered.R/O; no full wire-transfer or UCC analysis.
R010-P1-C011The securities/commodities EFT exclusion depends on the transfer’s primary purpose and specified regulatory or book-entry conditions.S003, § 3(c)(4), comments 1–3. Consumer Financial Protection BureauOrdinary purchases or cash withdrawals using a debit device against such an account are not automatically excluded.R/O; separate from the credit exclusion in C021.
R010-P1-C012Specified automatic transfers within the same institution, including automatic fee entries, may be excluded from the EFT definition.S003, § 3(c)(5), comments 1–2. Consumer Financial Protection BureauAgreement and institution initiation without a specific consumer request; prescribed account relationships. Affiliated institutions are not automatically the same institution. Compulsory-use and specified liability provisions remain preserved.R/O; exclusion of a bookkeeping transfer does not authorize the underlying fee.
R010-P1-C013The telephone-transfer exclusion is conditional on absence of the specified telephone bill-payment or other written recurring-transfer plan.S003, § 3(c)(6), comments 1–2. Consumer Financial Protection BureauA written service description can constitute a plan; infrequent use or separate requests do not necessarily remove coverage.R/O; actual arrangement held.
R010-P1-C014The small-institution exemption is limited to preauthorized transfers, not every EFT or every overdraft fee.S003, § 3(c)(7), comment 1. Consumer Financial Protection BureauAssets $100 million or less on the preceding December 31; specified phase-out one year after the end of the year in which assets exceed that figure; preserved provisions remain applicable.R/O; sourced threshold, no entity calculation.
R010-P1-C015Comment 3(a)-3 supplies a U.S.-account/state-resident geographic framework, including certain U.S. offices of foreign banks.S003, comment 3(a)-3; § 2(l). Consumer Financial Protection Bureau +1A foreign branch of a U.S. bank is not covered unless services connect to an account in a defined state; a particular transfer’s foreign location is not conclusive.O/R; international and actual-location questions held.
R010-P1-C016A preauthorized EFT is authorized in advance to recur at substantially regular intervals without further consumer action.S003, § 2(k), comment 2(k)-1. Consumer Financial Protection BureauRepeated separately initiated payments do not establish that definition; § 17 coding reliance remains separately relevant.R/O; recurring classification unknown without facts.
R010-P1-C017“Prepaid account” is a defined category with specific inclusions and exclusions, not a synonym for every stored-value, gift, benefit, or digital-wallet product.S003, § 2(b)(3) and comments. Consumer Financial Protection Bureau +1Payroll/government-benefit categories and specified prepaid/general-transaction products; exclusions include enumerated health, disaster, military closed-loop, gift, and needs-tested benefit arrangements. Checking/share-draft/NOW accounts are excluded from the residual prepaid category.R/O; remote benefits, tax, and gift-card definitions not comprehensively closed.
R010-P1-C018A § 17 overdraft service involves the institution charging its consumer account for paying a transaction when funds are insufficient or unavailable.S004, § 17(a). Consumer Financial Protection BureauAccount held by that institution; paid transaction; fee or charge; no applicable § 17(a)(1)–(4) exclusion.R; a negative ledger entry alone is insufficient classification evidence.
R010-P1-C019Payments pursuant to a credit line subject to Regulation Z are excluded from the § 17 overdraft-service definition.S004, § 17(a)(1). Consumer Financial Protection BureauIncludes transfers from a credit-card account, HELOC, or overdraft credit line if the specified predicate is met.R; full credit-law consequences held.
R010-P1-C020A service transferring funds from another account held individually or jointly by the consumer is excluded from the § 17 overdraft-service definition.S004, § 17(a)(2). Consumer Financial Protection BureauActual transfer arrangement required; the definition does not simply equate every negative balance with such a transfer.R; transfer charges and other laws not decided.
R010-P1-C021Specified securities/commodities credit exempt under Regulation Z § 1026.3(d) is excluded from § 17.S004, § 17(a)(3), comment 17(a)-1; S007, § 1026.3(d), comment 1. Consumer Financial Protection Bureau +1Credit involving securities/commodities accounts extended by the specified SEC/CFTC-registered broker-dealer; a separate loan merely used to buy securities is not enough.R/O; no registration or entity lookup.
R010-P1-C022The covered separate-credit-feature exclusion is specific to the qualifying feature accessible by a hybrid prepaid-credit card.S004, § 17(a)(4); S007, § 1026.61(a)(1)–(2), (5). Consumer Financial Protection Bureau +2Card capability to access credit during transaction authorization, settlement, or completion, and provision by issuer, affiliate, or qualifying business partner. Noncovered separate credit can independently be subject to Reg Z.R/O; no blanket exclusion of the entire prepaid account.
R010-P1-C023The prepaid negative-asset-balance exclusion requires the complete § 1026.61(a)(4) conditions.S007, § 61(a)(4)(i)–(ii)(A)–(C) and comments. Consumer Financial Protection Bureau +2No access to issuer/affiliate covered separate credit; required decline policy/practice, with permitted $10 and unsettled-load cushions, which may coexist; no prohibited credit/negative-balance fees or higher fees because of credit. Actual collection costs are excepted only if otherwise lawful, and late fees are not such costs. Ordinary nonprohibited fees can themselves create a negative balance.R/O; sourced legal cushion, no worked calculation; ordinary checking-account overdrafts cannot borrow this exception.
R010-P1-C024The business-partner definition has a specific exception for qualifying traditional-credit-card links.S007, § 61(a)(5)(iii)(A)–(D), related comments. Consumer Financial Protection Bureau +2Traditional open-end non-home-secured card; separately signed/initialized request subject to stated pre-April-1-2019/pre-arrangement treatment; no prohibited conditioning; same prepaid terms/comparable load fees; same specified credit terms across linking and access methods. Network membership alone is insufficient to establish the arrangement.R/O; definition only, no full credit-account compliance determination.
R010-P1-C025“Deposit advance,” “negative account,” and “setoff” labels do not establish a § 17 overdraft service or exclusion.S004, § 17(a), comment 17(b)-2; S003, § 2(f), § 3(c)(5). Consumer Financial Protection Bureau +3Funding mechanism, paid transaction, credit agreement, fee causation, and any asserted debit/setoff authority must be distinguished.I/U; no lending or setoff authority resolved.
R010-P1-C026A fee for returning an item unpaid is analytically different from a fee for paying an overdraft.S004, § 17(a), (b)(1); S003, § 3(b)(3). Consumer Financial Protection Bureau +2Establish whether the item was actually paid or returned; do not classify by an ambiguous fee label.R/I; § 17’s paid-overdraft prohibition does not establish NSF legality.
R010-P1-C027Electronic collection of a returned-item fee has its own authorization rule, distinct from overdraft opt-in.S003, § 3(b)(3)(i)–(ii), comments 1–4. Consumer Financial Protection Bureau +1Notice plus proceeding with the underlying transaction can authorize that particular fee EFT; POS notice/copy conditions apply. Comment 1 excludes the account-holding FI’s own return/pay fee from this particular authorization provision.R/O; this rule cannot be imported to infer § 17 opt-in from account use.
R010-P1-C028An ATM operator’s access/balance-inquiry fee is distinct from the account-holding institution’s overdraft fee.S003, § 1005.16(a)–(d); S001, § 1693b(d)(3). Consumer Financial Protection Bureau +1§ 16 operator does not hold the account; fee notice with amount must precede commitment, and the consumer must elect to continue.R/S; continuing after an ATM fee screen does not itself establish separate overdraft consent.
Source links captured in this table

Captured table 04

Claim ID · Precise claim / area · Source and pinpoint · 25 data rows

Claim IDPrecise claim / areaSource and pinpointTrigger, conditions, exceptionsStatus / limits
R010-P1-C029Four cumulative conditions govern charging for a covered paid ATM/one-time debit-card overdraft.S004, § 17(b)(1)(i)–(iv). ecfr.govNotice, reasonable opportunity, affirmative consent, and confirmation with revocation information; historical timing in (c).R; affirmative consent alone is insufficient.
R010-P1-C030The notice must be segregated, written or agreed electronic, clear, understandable, and retainable.S004, § 17(b)(1)(i); S003, § 4(a); S010, 31667. ecfr.gov +2Oral notice does not satisfy the written/electronic disclosure requirement.R/O/H; actual delivery and retained form unknown.
R010-P1-C031E-Sign § 7001(c) supplies a general consumer-electronic-record framework when law requires information in writing.S008, § 7001(b), (c)(1)–(6). uscode.house.govIncludes consent, prescribed information, access demonstration, and relevant exceptions when applicable.S; not automatically imported into § 17.
R010-P1-C032The § 17 adopting explanation expressly treats electronic disclosures under that section as outside E-Sign’s consumer-consent requirements, while retaining clarity and retainability.S009, footnote 32, 59041–59042, indices 8–9; current § 17(b)(1)(i), (iv). govinfo.gov +2Consumer agreement to electronic delivery remains required by § 17’s own text.H explaining R; not a withdrawn CFPB circular; other documents’ E-Sign treatment held.
R010-P1-C033Reasonable opportunity includes reasonable means of communicating consent.S004, comment 17(b)-4.i–iv. Consumer Financial Protection BureauMail form, readily available telephone line, electronic choice/affirmation, and in-person form are examples; not a mandate to offer all four.O; actual opportunity unknown.
R010-P1-C034Overdraft consent must be obtained separately from other consents and acknowledgments.S004, comment 17(b)-6. Consumer Financial Protection BureauIncludes separation from electronic-delivery consent. General preprinted account language and preselected opt-in boxes do not satisfy it.O; actual consent evidence held.
R010-P1-C035Account use or acceptance of an access device cannot, without an authorized separate basis, be substituted for affirmative overdraft consent.S004, § 17(b)(1)(iii), comments 17(b)-5–6; S003, § 2(a). Consumer Financial Protection Bureau +1Different statutory/regulatory forms of acceptance must not be conflated.I from R/O; no implied-consent finding.
R010-P1-C036An institution may require an account-opening yes/no choice, but silence is not opt-in.S004, comment 17(b)-5. Consumer Financial Protection BureauNo selected box/signature means no opt-in; offered accounts must comply with (b)(2)–(3).O; not permission to require the “yes” answer.
R010-P1-C037Confirmation must record the consent and include the right to revoke; a completed notice copy or acknowledgment letter can suffice.S004, § 17(b)(1)(iv), comment 17(b)-7. Consumer Financial Protection BureauWriting, or electronic if agreed; oral confirmation does not satisfy the disclosure requirement.R/O; actual content and delivery unknown.
R010-P1-C038The confirmation timing standard concerns transactions paid after confirmation is mailed or delivered.S004, comment 17(b)-7; S010, 31667–31668. Consumer Financial Protection Bureau +1Comment recognizes compliance through reasonable procedures designed to ensure that timing. Consumer receipt is not required before a fee; later fee posting alone does not cure the payment-timing issue.O/H; actual procedures and any error remain unresolved.
R010-P1-C039Covered overdraft fees may concern only overdrafts paid on or after receipt of affirmative consent, subject also to confirmation requirements.S004, comment 17(c)-1. Consumer Financial Protection BureauLater consent does not retrospectively validate fees for earlier paid transactions.O; event times unknown.
R010-P1-C040The opt-in notice must be substantially similar to A-9, include every applicable required item, and contain only specified or permitted information.S004, § 17(d). Consumer Financial Protection BureauSpecific § 17 rules govern permissible content and format.R; no current form visual-comparison conclusion.
R010-P1-C041The notice must explain the service and relevant transaction types; other-transaction policies must not overshadow the opt-in right.S004, § 17(d)(1), comment 17(d)-1. Consumer Financial Protection BureauInclude discretion/possible decline explanation as applicable.R/O; actual policy and accuracy unknown.
R010-P1-C042All applicable overdraft fees must be disclosed, including daily, sustained, and negative-balance fees; a variable fee requires its maximum.S004, § 17(d)(2), comment 17(d)-2. Consumer Financial Protection BureauAmount can vary by number of overdrafts, overdraft size, or other factors.R/O; no actual fee amount supplied or calculated.
R010-P1-C043The notice must disclose the maximum number of fees per day, or disclose that there is no limit.S004, § 17(d)(3). Consumer Financial Protection BureauThis is a disclosure requirement; it is not a national numerical fee cap or blanket permission under other law.R/I.
R010-P1-C044The notice must explain the right to opt in and the means available for doing so.S004, § 17(d)(4), comment 17(d)-3. Consumer Financial Protection BureauMethods must match what the institution actually offers.R/O.
R010-P1-C045Offered linked-credit and same-institution account-transfer alternatives must be disclosed as applicable.S004, § 17(d)(5), comment 17(d)-5. Consumer Financial Protection BureauBoth offered means disclose both; one means disclose that one; neither means omit that reference. Other alternatives may be listed.R/O; offering an alternative is not established here.
R010-P1-C046Section 17(d)(6) permits specified additional content concerning other-transaction choices, associated returned-item/merchant fees, revocation, and historical existing-account wording.S004, § 17(d)(6). Consumer Financial Protection BureauOnly as applicable; optional initial revocation wording does not eliminate mandatory revocation information in confirmation.R.
R010-P1-C047A-9 can be tailored to offered consent methods; a tear-off form and a decline box are not invariably required.S004, comments 17(d)-3–4. Consumer Financial Protection BureauReasonable account-identification methods are permitted; no identifiers are entered in this pass.O; no specific form approved.
R010-P1-C048Appendix A comments do not give blanket approval of institutional forms or every fee charged under them.S005, Appendix A comments 1–3; S004, § 17(d). Consumer Financial Protection Bureau +1Accurate use of appropriate model language concerns proper disclosure form; specific § 17 content limits remain.O/I; no individualized safe-harbor or liability decision.
R010-P1-C049Historical A-9 text was fully read; current A-9 pixels were not.S005–S006; S011, 81021. federalreserve.gov +1The 2011 text-continuity statement supports historical comparison, not an assertion of current visual inspection.H/U; current visual/read completeness remains partial.
R010-P1-C050Section 4’s general permission to combine disclosures does not override § 17’s specific segregation and content restrictions.S003, § 4(b); S004, § 17(b)(1)(i), (d); S010, 31671. Consumer Financial Protection Bureau +2Other material may be in the same mailing while the opt-in notice remains segregated.R/H/I.
R010-P1-C051Regulation E permits another disclosure language if English is available on request.S003, § 4(a)(2), comment 4(a)-2. Consumer Financial Protection BureauApplies alongside the required content and clarity standards.R/O; actual language/accessibility facts unknown.
R010-P1-C052For joint accounts, one set of required disclosures may be provided to any account holder.S003, § 4(c)(2). Consumer Financial Protection BureauSeparate § 17(e) governs whose consent or revocation binds the account.R; disclosure delivery is not itself consent.
R010-P1-C053Institutions offering EFT services jointly may allocate compliance by agreement, but § 4(d)’s knowledge limitation expressly concerns §§ 7 and 8.S003, § 4(d). Consumer Financial Protection BureauDoes not itself create a § 17 exception for the account-holding institution.R/I; actual actor allocation unknown.
Source links captured in this table

Captured table 05

Claim ID · Precise claim / area · Source and pinpoint · 22 data rows

Claim IDPrecise claim / areaSource and pinpointTrigger, conditions, exceptionsStatus / limits
R010-P1-C054An institution cannot condition paying check/ACH/other overdrafts on ATM/debit opt-in or decline them because opt-in was refused.S004, § 17(b)(2), comment 17(b)(2)-1. ecfr.gov +1Apply the same payment criteria consistently; this does not compel payment of every check or ACH item.R/O.
R010-P1-C055Consumers declining opt-in must receive the same other account terms, conditions, and features.S004, § 17(b)(3), comment 17(b)(3)-1. Consumer Financial Protection BureauIncludes interest paid, fees, card capabilities, minimum balance, and online bill pay; exception is the protected overdraft service itself.R/O.
R010-P1-C056Independently justified limited-feature accounts remain possible, but refusal to opt in cannot be used to divert an otherwise eligible consumer to them.S004, comment 17(b)(3)-2. Consumer Financial Protection BureauActual eligibility and account terms required.O; no creditworthiness decision.
R010-P1-C057Without opt-in, the institution may pay the covered transaction but cannot charge for paying it.S004, comment 17(b)-2. Consumer Financial Protection BureauDebit of principal is preserved only if permitted under other applicable law.O; no debt-validity, collection, or setoff conclusion.
R010-P1-C058Opt-in does not guarantee authorization or payment of an overdraft.S004, comment 17(b)-3. Consumer Financial Protection BureauContractual or other obligations are not adjudicated here.O.
R010-P1-C059Section 17(b) covers the relevant debit card only when issued by or on behalf of the account-holding institution.S004, comment 17(b)-1.i. Consumer Financial Protection BureauThird-party issuance without the “on behalf of” relationship is outside that stated scope.O; actual issuance/funding relationship unknown.
R010-P1-C060A one-time debit-card transaction can qualify whether conducted at POS, online, or by telephone.S004, comment 17(b)-1.iii. Consumer Financial Protection BureauChannel location does not substitute for recurring/one-time classification.O.
R010-P1-C061The coding reliance rule requires systems adapted to identify one-time versus recurring transactions.S004, comment 17(b)-1.ii. Consumer Financial Protection BureauAfter that condition is met, merchant/institution/third-party coding may be relied upon.O; coding accuracy, system adaptation, and actual reliance not established.
R010-P1-C062The fee prohibition applies to all otherwise covered institutions, including those with a general decline policy.S004, comment 17(b)-1.iv. Consumer Financial Protection BureauAn institution charging no fees for these paid overdrafts need not perform the § 17(b)(1)(i)–(iv) notice/opt-in process for that fee-free service.O; no general policy-based fee exception.
R010-P1-C063Positive authorization followed by negative settlement does not excuse a covered fee where the required opt-in was absent.S004, comment 17(b)-1.iv. Consumer Financial Protection BureauCommentary’s express example includes intervening transactions reducing funds before settlement.O; other timing configurations and actual balances held.
R010-P1-C064With no opt-in, a fee based on negative-balance amount is prohibited when that balance is solely attributable to protected ATM/one-time debit transactions.S004, comment 17(b)-8. Consumer Financial Protection BureauRequires fee classification and sole attribution.O.
R010-P1-C065Section 17 does not prohibit that amount-based fee when the negative balance is wholly or partly attributable to a check, ACH, or another nonprotected transaction.S004, comment 17(b)-8. Consumer Financial Protection BureauDoes not validate a separate per-item fee for an unconsented protected card transaction.O; other law/contract held.
R010-P1-C066With no opt-in, daily/sustained/negative-balance/similar fees are prohibited when the negative balance is solely attributable to protected transactions.S004, comment 17(b)-9.i. Consumer Financial Protection BureauFee substance and causation govern; a new fee label does not answer causation.O/I.
R010-P1-C067Section 17 does not prohibit those ongoing fees where a negative balance is wholly or partly attributable to nonprotected transactions.S004, comment 17(b)-9.i. Consumer Financial Protection BureauSubject to the timing rule in C068 and actual remaining balance attribution.O; no all-law fee authorization.
R010-P1-C068For a mixed negative balance, the ongoing-fee timing anchor is when the nonprotected transaction was paid into overdraft.S004, comment 17(b)-9.i, -9.ii.C. Consumer Financial Protection BureauAn earlier protected card overdraft does not supply that start date.O; contractual period, units, calendar, and events unknown.
R010-P1-C069The official mixed-balance examples depend on expressly stipulated posting and deposit-allocation assumptions.S004, comment 17(b)-9.ii, examples A–C. Consumer Financial Protection BureauLater deposits can alter which debit component remains; associated fees matter in the examples. Their sample amounts and periods are not national legal thresholds.O/I; no mandatory universal allocation method or actual calculation inferred.
R010-P1-C070A conservative alternative permits avoiding ongoing fees unless the outstanding negative balance is solely attributable to nonprotected transactions.S004, comment 17(b)-9.iii. Consumer Financial Protection BureauThis alternative avoids calculating allocation of partial deposits; it is an alternative, not the only required method.O.
R010-P1-C071Any joint consumer’s affirmative consent binds the account; any joint consumer’s revocation likewise revokes account consent.S004, § 17(e). Consumer Financial Protection BureauJoint relationship must actually exist.R; no requirement that every joint holder separately opt in or revoke.
R010-P1-C072A consumer may opt in at any time and revoke at any time through the means made available for consent.S004, § 17(f). Consumer Financial Protection BureauOpt-in follows the notice’s manner; revocation access must reflect available consent methods.R.
R010-P1-C073Revocation must be implemented as soon as reasonably practicable.S004, § 17(f). Consumer Financial Protection BureauThe section supplies no fixed number of days for this implementation.R; actual elapsed time and practicability unknown.
R010-P1-C074Revocation alone does not require reversal of fees assessed before implementation of the revocation request.S004, comment 17(f)-1. Consumer Financial Protection BureauDoes not establish that earlier fees were lawful or excuse unreasonable implementation delay.O/I; separate grounds remain held.
R010-P1-C075Consent continues until revoked by the consumer or the institution terminates the service.S004, § 17(g), comment 17(g)-1. Consumer Financial Protection BureauTermination is possible; excessive use is the comment’s example.R/O; no actual termination or reconsent finding.
Source links captured in this table

Captured table 06

Claim ID · Precise claim / area · Source and pinpoint · 15 data rows

Claim IDPrecise claim / areaSource and pinpointTrigger, conditions, exceptionsStatus / limits
R010-P1-C076The original final rule distinguished its effective date from its mandatory compliance date.S009, 74 FR 59033, index 0. govinfo.govEffective January 19, 2010; mandatory compliance July 1, 2010, with the specific existing-account transition.H; historical regulatory dates, not individual deadlines.
R010-P1-C077The 2010 clarification removed former (b)(4); its correction preserved the four subparagraph requirements by specifying amendment of the introductory text.S010, 75 FR 31671–31672; correction 33681. govinfo.gov +1Both effective July 6, 2010.H; former (b)(4) is not a current fee exception.
R010-P1-C078The 2011 rule recodified Regulation E into Part 1005 without new substantive obligations.S011, 76 FR 81020–81021. govinfo.govEffective December 30, 2011; transfer of relevant rulemaking authority described as July 21, 2011.H; current duties come from current text.
R010-P1-C079Accounts opened before July 1, 2010 were not permanently grandfathered out of opt-in.S004, § 17(c)(1). Consumer Financial Protection BureauCovered fees assessed on or after August 15, 2010 require § 17(b)(1) compliance and affirmative consent.R; opening date/fee facts unknown.
R010-P1-C080Accounts opened on or after July 1, 2010 require compliance and consent before covered fees are assessed.S004, § 17(c)(2), comment 17(c)-1. Consumer Financial Protection BureauAlso apply consent/payment and confirmation timing.R/O; no actual event-date calculation.
R010-P1-C081Opt-in is not a waiver of all EFTA protections or every other fee limitation.S002, § 1693l; S004, § 17. uscode.house.gov +1Statute preserves greater protection and expressly excepts a waiver given in settlement of a dispute or action.S/I; no settlement, enforceability, or remedy decision.
R010-P1-C082The 2024 overdraft final rule originally stated an October 1, 2025 effective date.S012, 89 FR 106768 and § V. govinfo.gov +1It was a final rule with a future effective date when issued.H/D; that planned date is not treated as having activated the disapproved rule.
R010-P1-C083Public Law 119-10 disapproved the specifically identified 2024 final rule and gave it no force or effect.S013, 139 Stat. 53, entire operative sentence. govinfo.govApproved May 9, 2025; identifies 89 FR 106768, December 30, 2024.S; exact enacted effect read.
R010-P1-C084The disapproved rule’s added comment 17(a)-2 and new covered-overdraft framework cannot be used here as current requirements or exclusions.S012, 106837, index 69; S013; current S004. govinfo.gov +2The preexisting Regulation Z-line exclusion still exists on its own terms.D/R/I; no new fee cap inferred from the disapproved rule.
R010-P1-C085The CFPB resource page’s May 12 signing date conflicts with the enacted public law’s May 9 approval date.S014 featured paragraph; S013 heading and approval line. Consumer Financial Protection Bureau +1This report uses May 9, 2025 for enactment/approval.Verified source discrepancy; resource date not substituted for statute.
R010-P1-C086Circulars 2022-06 and 2024-05 are withdrawn guidance under the inspected official status materials.S015 register and 90 FR 20084–20086; S016 publisher pages. Consumer Financial Protection Bureau +4Withdrawal applicable May 12, 2025.W; historical analyses not current-rule substitutes.
R010-P1-C087Withdrawal of those circulars does not itself repeal the statute/regulation or affirmatively validate all fees discussed in them.S015’s specified withdrawal action; S002–S004. federalregister.gov +2Distinguish guidance status from the continued text and scope of statutes/regulations.I from S/R/W; other legal grounds remain open.
R010-P1-C088A stipulated compliant opt-in does not settle the full legality of an authorization-positive/settlement-negative fee.S004, § 17 and comment 17(b)-1.iv; C081, C086–C087. Consumer Financial Protection Bureau +2Other applicable statutory, contract, disclosure, balance-method, and judicial questions need their own authority and facts.U; no current broader liability theory asserted.
R010-P1-C089The generic rules cannot determine actual consent, causation, coding, contract compliance, liability, eligibility, or relief without facts not supplied and not searched.Analytical limit of C002–C088; user scope.All actual identity, account, balance, timing, agreement, and transaction facts remain blank.U; no individual or class-action determination.
R010-P1-C090The checked current-resource labels and retrieved bodies support this bounded report, but do not certify all intervening legislation, publications, litigation, or current form pixels.S001–S018 and failure log. ecfr.gov +2eCFR title currency through October 23; selected OLRC labels through October 20; older statutory recoveries; unread current image.U / methodological qualification; no component or parent closure.
Source links captured in this table

Captured table 07

Example · Stipulated hypothetical facts · Section-specific result and remaining unknown · 15 data rows

ExampleStipulated hypothetical factsSection-specific result and remaining unknownEvidence category neededAdverse misclassification to avoid
E01 — No opt-in; paid one-time debitAll coverage predicates are stipulated; an account-holding FI pays a one-time debit-card overdraft; no affirmative consent exists.§ 17 prohibits a fee for paying it. Principal debit authority is separately conditional on applicable law. C018, C029, C057, C066.Paid-item status, card relationship, channel, absence of consent, fee linkage.Treating payment itself as consent; treating the fee prohibition as automatic principal forgiveness.
E02 — Affirmative opt-in; other conditions unknownA separate affirmative choice is stipulated, but notice, opportunity, confirmation, and timing are unknown.Fee authority under § 17 is not established merely by that choice. C029–C039. No actual violation or remedy is adjudicated.Notice content/delivery, opportunity, confirmation, payment chronology, procedures.Collapsing four cumulative requirements into “a consent box exists.”
E03 — Recurring classification uncertainDebit-card payments recur in ordinary language, but advance authorization, further consumer action, coding, and adapted systems are unknown.Classification remains unresolved. C016, C061.Payment arrangement, initiation method, recurrence indicator, system adaptation/reliance.Calling every repeated merchant payment recurring, or disregarding the commentary’s conditional coding rule.
E04 — Paid check or ACHA transaction is stipulated to be a check or ACH debit, not an ATM/one-time card transaction; it is paid into overdraft.The specific ATM/one-time-card opt-in prerequisite does not by itself prohibit the fee. C008–C009, C054, C065, C067. Other law and contract remain unknown.Actual rail and paid status; fee type; governing contract.Treating all EFTs as debit-card transactions; treating absence of this prohibition as universal legality.
E05 — No consent; other negative-balance sourceNo opt-in; the negative balance is stipulated to arise solely from a paid check or ACH transaction.Comments 17(b)-8 and -9 do not prohibit the described balance-based/ongoing fee merely because there was no ATM/debit opt-in. C064–C068.Complete causation and contract trigger.Assuming every negative balance without opt-in is fee-free.
E06 — Revoked consentA valid revocation has been implemented; a later covered one-time debit is paid.The prior consent no longer supplies the opt-in predicate for a fee on that payment. C029, C072–C075. Earlier fees are not automatically reversed solely by revocation.Revocation receipt, available methods, implementation, payment/fee events.Treating revocation as retroactive cancellation of every prior fee, or as ineffective indefinitely.
E07 — Linked credit excludedPayment is stipulated to occur pursuant to an overdraft line subject to Regulation Z.Excluded from “overdraft service” under § 17(a)(1). C019. Credit agreement, APR, usury, origination, repayment, and other protections remain held.Nature of credit line and funding mechanism.Applying the § 17 opt-in rule as the complete law of the credit line.
E08 — Mixed transactionsNo opt-in; protected card and check/ACH debits contribute to a continuing negative balance.The protected card payment cannot carry its own unconsented overdraft fee. A separate ongoing fee requires the mixed-balance analysis and the nonprotected payment-date anchor. C064–C070.Debit sequence, deposits/credits, allocation, associated fees, residual balance, fee period.Letting one check validate all card fees; using the earliest card overdraft as the sustained-fee start.
E09 — Positive authorization; negative settlement; no opt-inCovered one-time debit authorized when funds are believed sufficient; intervening activity leaves insufficient funds at settlement; no required opt-in.The current comment expressly prohibits the fee for paying that transaction. C062–C063.Authorization/settlement facts and consent status.Treating a general decline policy or positive authorization as an exception.
E10 — Positive authorization; negative settlement; opt-in stipulatedAll § 17 opt-in steps are stipulated satisfied; authorization and settlement balances differ.This pass does not conclude that the fee is lawful or unlawful under all applicable law. C081, C086–C088.Actual balance methodology, contract/disclosures, causation, independently applicable authority.Using withdrawn Circular 2022-06 as current operative law, or treating its withdrawal as a universal permission.
E11 — Returned unpaid / NSFThe underlying item is stipulated to have been returned unpaid.Classify the charge as a returned-item/NSF issue; the paid-overdraft fee rule alone does not decide it. A separate fee-collection EFT can implicate § 3(b)(3). C026–C027.Returned/paid disposition; who assessed/collected the fee; collection method.Calling an unpaid item a paid overdraft; confusing a merchant fee EFT with the FI’s own fee entry.
E12 — General agreement or account use onlyThe only stipulated acts are signing general account terms and using the account; no separate affirmative choice is stipulated.Those acts do not establish the required separate opt-in. C034–C036.Dedicated consent act and associated disclosure sequence.Importing “use constitutes authorization” from a different rule.
E13 — Joint-holder revocationA joint consumer revokes existing opt-in, with implementation stipulated.Revocation operates for the account under § 17(e). C052, C071–C075.Joint relationship and revocation chronology.Requiring every joint holder to revoke, or treating one disclosure copy as every holder’s affirmative consent.
E14 — Prepaid negative balanceA product is called prepaid and has a negative asset balance; credit access, issuer relationships, decline policy, and fee conditions are unknown.Neither § 17(a)(4) exclusion is established from the label or negative balance alone. C017, C022–C024.Defined prepaid status; feature structure; issuer/affiliate/business-partner relationship; authorization policy; fee predicates.Applying the prepaid exception to ordinary checking accounts or ignoring its no-prohibited-fee conditions.
E15 — ATM access feeA non-account-holding ATM operator discloses its access fee and the consumer continues.Analyze that operator fee under § 16; this does not itself establish § 17 overdraft consent to the account-holding FI. C028–C034.Fee actor, fee purpose, screen/paper notice, separate overdraft process.Treating acceptance of an ATM surcharge as overdraft opt-in.

Captured table 08

Field · Generic question / document attribute · Entry · 27 data rows

FieldGeneric question / document attributeEntryClaim / example links
W01 Product purposeIs the asset account established primarily for personal/family/household or business purposes?—C002–C003
W02 Account categoryChecking/share draft/savings/prepaid/trust/other; which exact definition and exclusion governs?—C003, C017–C024
W03 Actor roleAccount holder, card issuer on its behalf, separate card issuer, ATM operator, merchant/payee, creditor, transfer-service actor?—C004–C006, C028, C053, C059
W04 Geographic predicateAccount location and relevant statutory/regulatory residence/location predicates?—C015
W05 EFT agreementWhat generic agreement establishes EFT services, and which party’s agreement is relevant?—C006
W06 Transaction rail/channelATM, one-time card, recurring card, ACH, check, converted check, wire, internal transfer, other?—C007–C016, C060–C061
W07 Recurring classificationAdvance authorization, substantially regular intervals, and further consumer action?—C016; E03
W08 Coding relianceClassification indicator, system adaptation, and basis for reliance on third-party coding?—C061; E03
W09 Card relationshipWas the debit device issued by or on behalf of the account-holding institution?—C059
W10 Payment dispositionWas the underlying item actually paid, declined, reversed, or returned unpaid?—C018, C026–C027; E11
W11 Authorization/settlementRelevant authorization and payment/settlement events; what does the operative rule actually answer?—C038–C039, C063, C088
W12 Balance methodologyLedger/available balance definitions, holds, unsettled items, posting order, reversals, and intervening credits?—C018, C063–C070, C088
W13 Notice version/contentService, transaction types, all fees, variable maxima, fee count, consent methods, offered alternatives, permitted additions?—C040–C047
W14 Notice separationIs the notice segregated from other information and the consent choice separate from other acknowledgments?—C030, C034, C050
W15 Delivery/retentionWritten or agreed electronic delivery; clear, understandable, retainable form; relevant language availability?—C030–C032, C051
W16 OpportunityWhat reasonable method and opportunity for affirmative choice were provided?—C033, C036
W17 Consent actWhat dedicated affirmative act occurred, and when was it received?—C034–C039
W18 ConfirmationWritten/agreed electronic confirmation, revocation statement, mailing/delivery event, reasonable procedures?—C037–C038
W19 Joint relationshipWhich joint-holder rule applies to disclosure, opt-in, or revocation?—C052, C071
W20 RevocationMethod, receipt, implementation, practicability, and any later valid opt-in?—C072–C075
W21 Fee classificationPer-item payment fee, balance-tier fee, daily/sustained fee, NSF, returned-deposit fee, transfer fee, credit charge, ATM surcharge, other?—C025–C028, C042–C043, C064–C070
W22 Fee causationWhich paid transaction or remaining negative-balance components caused the particular fee?—C064–C069
W23 Mixed-balance allocationHow do posting order, later deposits, associated fees, credits, and reversals affect residual attribution?—C068–C070; E08
W24 Fee period and triggerDisclosed contractual period; calendar or business-day units; starting event; continuing-balance condition; applicable exclusions?—C042, C068–C069
W25 Linked arrangementReg Z line, own-account transfer, securities credit, qualifying prepaid feature, or another mechanism?—C019–C025
W26 Other account termsSame pricing/features and payment criteria regardless of opt-in; independent basis for any limited-feature product?—C054–C056
W27 Unresolved governing factsState/country/tribal status, contract terms, other legal limits, benefit protections, security/setoff, and other parent dimensions?—C081, C088–C090; parent holds

Captured table 09

Assigned subquestion / branch · Coverage · Claim / example links · 49 data rows

Assigned subquestion / branchCoverageClaim / example linksExact missing authority or factsNext bounded permissible investigation
1.a Enabling EFTA authorityPartial: substantive text read; currentness gapC001; S001, S003, S011Current OLRC §§ 1693a–b bodies and complete later session-law lag audit.Recover current official statutory text and check only relevant published amendments.
1.b Consumer versus business accountAnswered genericallyC002–C003Actual primary purpose and account arrangement.No actual-record inquiry authorized; maintain fact hold.
1.c Bank/credit-union/other FI coverageAnswered genericallyC004–C005, C053, C059Actual account-holder/issuer roles and any statutory excluded-person predicates.Published definition clarification only; no institution/license search.
1.d EFT-service agreement gatewayAnswered genericallyC006–C009Actual agreement, notice of third-party arrangement, transfer initiation.Maintain fact hold.
1.e Necessary EFT exclusionsAnswered within relevant clausesC008, C010–C014Actual rail, purpose, within-institution relationship, qualifying assets/plan.Narrow public authority follow-up only if a specific legal ambiguity becomes material.
1.f Geographic scopeAnswered at federal gateway; broader scope heldC015Actual account location/residence; non-U.S. law.No country-wide or international closure; separate bounded law review only.
1.g Covered paid overdraft definitionAnswered genericallyC018Paid status, insufficient/unavailable funds, fee cause, account-holding actor.Maintain fact hold.
1.h Linked credit/own-account transfer/securities exclusionsAnswered genericallyC019–C021; E07Actual mechanism and agreement.No credit-product or provider search.
1.i Prepaid exclusionAnswered as conditional gate; product taxonomy partialC017, C022–C024; E14Product facts; remote incorporated benefits/gift/tax definitions; historical prepaid-date chain.Follow only a material published cross-reference; no full prepaid/credit closure.
1.j Actual coding/classificationUnresolved factsC016, C059–C061; E03Actual coding, adapted systems, reliance, recurring authorization.No actual transaction search authorized.
2.a Complete § 17 notice/consent/confirmation/revocation textAnswered; full section/comments readC029–C047, C071–C080; S004Actual compliance facts only.No additional generic authority needed for the stated text.
2.b Segregated notice and separate choiceAnswered genericallyC030, C034–C036, C050; E12Actual presentation, dedicated choice, preselection.Maintain fact hold.
2.c Reasonable opportunity and methodsAnswered genericallyC033, C036, C044Actual opportunity and available methods.Maintain fact hold.
2.d Electronic delivery and retainabilityAnswered with authority-type distinctionC030–C032, C037Actual delivery agreement/retention; independent requirements for other documents.Any further E-Sign work must identify the distinct legally required disclosure.
2.e Confirmation timingAnswered genericallyC037–C039; E02Mailing/delivery, consent receipt, transaction payment, reasonable procedures.Maintain fact hold; no invented receipt deadline.
2.f Complete required notice contentAnswered genericallyC040–C047Actual fees, service policies, alternatives, tailored text.Compare only a permissible generic blank form if later needed.
2.g Current A-9 body/imagePartial source retrievalC049; S005–S006, S011Current image pixels and complete current image transcription not obtained.Obtain readable official current form through permitted public tools; no access workaround.
2.h Historical A-9 and current instructionsAnswered within read boundsC040–C049Historical-to-current visual comparison remains unverified.Preserve distinction between historical parsed text and current image.
2.i Revocation, joint holders, durationAnswered genericallyC071–C075; E06, E13Actual joint status and event chronology.Maintain fact hold.
2.j Effective dates and existing accountsAnswered for § 17 transition/recodificationC076–C080Actual opening and payment dates.No individual calendar calculation.
3.a Complete fee prerequisiteAnswered genericallyC029, C057–C063Actual satisfaction of coverage and four conditions.Maintain fact hold.
3.b No conditioning of other overdraftsAnswered genericallyC054Actual payment criteria and reason for decline.No institutional practice investigation.
3.c Same terms/featuresAnswered genericallyC055–C056Actual comparative terms and independent eligibility.No creditworthiness or account-eligibility decision.
3.d Payment discretion versus fee authorityAnswered genericallyC057–C058; E01Applicable principal-debit law and contract remain unknown.Preserve setoff/collection/contract holds.
3.e Checks/ACH/recurring versus one-time cardAnswered generically; classification facts unresolvedC008–C016, C059–C061; E03–E04Actual channel and recurring predicates.Maintain fact hold.
3.f Balance-amount feesAnswered genericallyC064–C065; E05, E08Actual balance components and fee basis.No ledger reconstruction authorized.
3.g Daily/sustained/negative-balance feesAnswered genericallyC066–C070Actual continuing attribution, contractual period, deposits and allocations.Maintain fact hold; no universal period inferred.
3.h Mixed-balance timingAnswered genericallyC068–C070; E08Nonprotected payment date, period units, residual source.Only generic further interpretation; no individual deadline.
3.i Opt-in and other limitsAnswered as limitationC081, C088Broader governing law/contract and any settlement context.Preserve parent holds.
4.a Authorization-positive/settlement-negative without opt-inAnswered by current commentC062–C063; E09Actual predicates, if any.No withdrawn guidance needed.
4.b Authorization-positive/settlement-negative with compliant opt-inUnresolved broader legal basisC088; E10Independently applicable law, balance/disclosure/contract facts.If later necessary, inspect only material published primary authority; no docket query.
4.c Withdrawn-guidance checksAnswered for every circular used for statusC086–C087; S015–S016No broader guidance-universe audit asserted.Recheck official register only if another guidance item becomes necessary.
4.d 2024/2025 final-rule disapprovalAnswered for authority actually implicatedC082–C085; S012–S014Full unrelated provisions of disapproved rule not examined.No need to revive its framework; retain exact statutory effect.
4.e Paid versus returned/unpaid, NSFAnswered as distinction; broader law excludedC026–C027; E11Actual disposition, actor and collection method; substantive NSF law.Separate generic NSF component if later assigned.
4.f Deposit advance, linked credit, setoffPartial by intentional scopeC019–C025; E07Credit/security/setoff contracts and broader legal authority.Preserve separate lending/setoff dimensions.
4.g Published opinions/later litigation statusExcluded from conclusions; no case holding needed hereC088–C090No majority-opinion holding or later-history audit performed.Only material published opinions if later strictly necessary; no case-record/docket-status query.
5.a Blank audit worksheetDeliveredW01–W27All entries intentionally blank.No records request or identifier entry.
5.b No-opt-in paid one-time branchDeliveredE01; C029, C057Actual facts not supplied.None within this published-source pass.
5.c Affirmative consent, other conditions unknownDeliveredE02; C029–C039Notice/opportunity/confirmation/timing facts.Maintain hold.
5.d Recurring classification branchDeliveredE03; C016, C061Classification/coding/system facts.Maintain hold.
5.e Check or ACH branchDeliveredE04; C008–C009, C054Channel and contract facts.Maintain hold.
5.f No consent, other negative sourceDeliveredE05; C064–C068Causation and fee trigger.Maintain hold.
5.g Revoked-consent branchDeliveredE06; C072–C075Receipt/implementation/payment chronology.Maintain hold.
5.h Linked-credit exclusion branchDeliveredE07; C019Actual Reg Z credit arrangement.Preserve credit-law holds.
5.i Mixed-transactions branchDeliveredE08; C064–C070Complete component allocation and timing.Maintain hold.
5.j Authorization/settlement branchDelivered in two distinct formsE09–E10; C063, C088With-opt-in broader legal basis remains unresolved.No universal APSN conclusion.
Standards: current statutory/body/edition completenessPartialC090; failure logCurrent bodies for identified statutes; complete intervening-publication audit.Public primary-source recovery only.
Standards: UI/model provenanceUnverified beyond session identityOpening provenance statementFrontend and selector evidence unavailable.No claim of unseen UI verification.
Parent/operational/publication acceptanceExcludedParent holds belowNo authority or factual basis for acceptance/closure requested.Preserve all holds; no operational action.

Captured table 10

User assignment · Principal claims · Principal sources · 6 data rows

User assignmentPrincipal claimsPrincipal sourcesDelivered examples / audit
1. EFTA/Reg E consumer, account, institution, transfer coverage and exclusionsC001–C028, C059–C061S001, S003–S004, S007, S017E03–E04, E07, E11, E14–E15; W01–W12, W25
2. Complete notice, separate content/form, consent, confirmation, revocation, model, datesC029–C053, C071–C080S003–S006, S008–S011E02, E06, E12–E13; W13–W20
3. Fee prohibition, conditioning, same terms, discretion, mixed-balance causationC029, C054–C075, C081S002–S004, S010E01, E04–E08; W21–W26
4. Authorization/settlement, guidance withdrawal, repeal, unpaid/NSF/credit/setoff distinctionsC019–C028, C062–C063, C082–C090S003–S004, S007, S012–S017E07–E11, E14–E15; W10–W12, W21–W25
5. Blank audit and qualitative branchesC089–C090 and branch-specific claims aboveSource-linked claim registerW01–W27 and E01–E15
Standards and parent holdsC049, C081–C090Source table and read/failure logCoverage table, self-check, parent holds

Captured table 11

Log item · What was actually read · What was not represented as read · 10 data rows

Log itemWhat was actually readWhat was not represented as read
L01 — Current § 17Entire operative § 17(a)–(g), all embedded official interpretations, all three mixed-balance examples, and the alternative method. Annual § 17 PDF text also read in full.No claim that the whole of Regulation E, all related regulations, or all annual-CFR pages were read.
L02 — Necessary gatewayRelevant § 2 definitions; complete § 3 coverage/exclusion text and relevant interpretations; complete § 4; complete § 16 for the ATM-operator distinction.No full error-resolution, unauthorized-transfer-loss, benefits, remittance, gift-card, or state-law investigation.
L03 — Linked/prepaid exclusionsNecessary § 1026.3(d) and § 1026.61 definition/exception text, including negative-balance conditions and business-partner exception.No comprehensive Regulation Z, APR, origination, security, repayment, or credit-account compliance review.
L04 — A-9Current heading/link and current § 17(d)/Appendix A instructions; complete parsed historical one-page A-9; 2011 statement of substantive continuity.No current A-9 pixels seen. No claim of complete current-image transcription or visual comparison.
L05 — Final-rule dates and explanationsNecessary 2009 dates/electronic-delivery explanation; relevant 2010 clarification passages and complete correction; 2011 recodification/A-9 passage.Not every page of each historical preamble. Historical provisions superseded by later clarification were not treated as current.
L06 — DisapprovalComplete Public Law 119-10; the 2024 rule’s stated effective date, necessary discussion, and complete added § 17(a)-2 comment; agency status paragraph.Not the entire 78-page disapproved rule or a broader Congressional Review Act reissuance analysis.
L07 — WithdrawalOfficial register, operative withdrawal discussion, relevant listed circulars, and publisher-page identification/scope passages.No wholesale adoption of historical circular analyses or their cited cases; no assumption that a live URL means current guidance.
L08 — StatutesOfficial 2024 §§ 1693a–b and § 5519 recovery bodies; current-labeled § 1693l and § 7001 bodies.No claim that annual recovery text or a compilation header establishes complete current session-law status.
L09 — Images and screenshotsParsed PDF text and image-link metadata only.PDF text is not pixels. Placeholder image results and the failed A-9 screenshot were not counted as image inspection.
L10 — Discovery exclusionsSearch results were used to locate permitted primary bodies.Search snippets, headnotes, secondary reports, proposed-rule summaries, incidental case/entity results, and unopened prototype forms were not substantive foundations. No actual-case search was pursued.

Captured table 12

Failure ID / source · Complete requested URLs or identified failed representation · Result and bounded consequence · 10 data rows

Failure ID / sourceComplete requested URLs or identified failed representationResult and bounded consequence
F01 / S001 — Current § 1693ahttps://uscode.house.gov/view.xhtml?req=granuleid:USC-prelim-title15-section1693a&num=0&edition=prelim ; https://uscode.house.gov/view.xhtml?req=%28title%3A15+section%3A1693a+edition%3Aprelim%29 ; https://uscode.house.gov/us/usc/119-134/t15/s1693a/ ; https://uscode.house.gov/us/usc/119-124/t15/s1693a/ ; https://uscode.house.gov/us/usc/119-121/t15/s1693a/ ; https://www.govinfo.gov/content/pkg/USCODE-2025-title15/html/USCODE-2025-title15-chap41-subchapVI-sec1693a.htmReturned combinations of 404, page-not-found, disabled/inaccessible results. Recovered official 2024 body, S001. Current statutory lag remains unresolved.
F02 / S001 — Current § 1693bhttps://uscode.house.gov/view.xhtml?req=granuleid:USC-prelim-title15-section1693b&num=0&edition=prelim ; https://uscode.house.gov/us/usc/119-134/t15/s1693b/ ; https://uscode.house.gov/us/usc/119-124/t15/s1693b/ ; https://uscode.house.gov/us/usc/119-121/t15/s1693b/ ; https://uscode.house.gov/us/usc/t15/s1693b/ ; https://www.govinfo.gov/content/pkg/USCODE-2025-title15/html/USCODE-2025-title15-chap41-subchapVI-sec1693b.htm ; https://www.govinfo.gov/content/pkg/USCODE-2024-title15/html/USCODE-2024-title15-chap41-subchapVI-sec1693b.htm500/inaccessible responses. Recovered official 2024 PDF body, S001. No inference of missing authority.
F03 / S001 — Current chapter fallbackhttps://uscode.house.gov/view.xhtml?edition=prelim&req=granuleid%3AUSC-prelim-title15-chapter41-subchapter6404. Did not close statutory-currentness gap.
F04 / S002 — § 1693l path and repeat retrievalhttps://uscode.house.gov/view.xhtml?req=granuleid:USC-prelim-title15-section1693l&num=0&edition=prelim ; https://uscode.house.gov/us/usc/119-134/t15/s1693l/Old path failed; modern body initially succeeded. One direct repeat failed; reopening the retrieved reference again returned the complete body. Recovered, with header limit preserved.
F05 / S017 — Current § 5519https://uscode.house.gov/view.xhtml?req=granuleid:USC-prelim-title12-section5519&num=0&edition=prelim ; https://uscode.house.gov/us/usc/119-134/t12/s5519/ ; https://uscode.house.gov/us/usc/t12/s5519/404/inaccessible. Recovered 2024 official body, S017. No actual excluded-person determination.
F06 / S004 — Fixed annual § 17 URLhttps://www.govinfo.gov/content/pkg/CFR-2026-title12-vol8/pdf/CFR-2026-title12-vol8-sec1005-17.pdfFixed path inaccessible. Recovered complete 2026 § 17 through the Govinfo link URL in S004.
F07 / S005, S011, S018 — Current A-9 representationCurrent PNG and appendix URLs in S005; embedded graphic in S011; full-part annual PDFs in S018.Current image returned a placeholder; appendix extraction supplied heading but not full form body; PDF extraction omitted the graphic text. Current pixels/full-image transcription remain unverified. Historical parsed model recovered through S006.
F08 / S018 — Large 2026 CFR PDFBoth 2026 full-part URLs in S018.Initial header/text success followed by targeted find/open timeouts. No full-part body-read claim.
F09 / S004, S006, S013 — Screenshots§ 17 PDF indices 0–2; public law index 0; historical A-9 index 0.Earlier calls supplied image placeholders without inspectable image content. The historical A-9 screenshot returned an inability-to-resolve/screenshot-not-enabled error despite parsed PDF availability. No pixel-read claim.
F10 — Search-domain restrictionSearch service reported a non-retryable robots restriction for https://www.congress.gov/ during generic legislative discovery.No workaround attempted. The enacted public-law body was read from Govinfo, S013; no Congress.gov body is claimed read.
Source links captured in this table

Captured table 13

Check · Result · 12 data rows

CheckResult
Independent primary-source investigation, without prior-report foundationPerformed. No unreviewed Library report or prior chat was used.
Complete focused § 1005.17 operative text and official interpretationsRead, including exclusions, all four conditions, notice content, conditioning, same terms, joint relationships, revocation, duration, and mixed-balance examples.
Statute versus regulation versus official interpretation versus guidanceSeparated in source and claim statuses.
Current, historical, future-effective, disapproved, withdrawn, unknownSeparated. The 2024 rule’s planned effective date was not treated as operative; withdrawal was not treated as statutory repeal.
Current A-9 image readNot achieved. Historical parsed text and current instructions are explicitly distinguished from current pixels.
Current statutory/edition/session-law auditPartial. Identified current-body failures and older official recoveries are preserved.
Fee-causation reasoningQualified. Per-item, amount-based, ongoing, mixed-source, and returned-item branches are separated.
Authorization/settlement treatmentBounded. No-opt-in example answered from the current comment; broader with-opt-in legality held.
Numerical integrityNo invented fees, awards, or deadlines. Regulatory thresholds stated are sourced; no individual arithmetic performed.
Actual-record, entity, identifier, or docket investigationNone conducted.
Individual liability, class eligibility, standing, remedies, filing adviceNo determination made.
Component, state, parent, operations, or publication acceptanceNone given.

Find the assertion and its boundaries

Read the evidence with its boundaries. These are saved research components, including revisions. A scoped coordinator review checks selected evidence; it does not certify every claim, a complete jurisdiction, current law or individual applicability. Dates and access limits remain attached to the records.

How to read the research →

R010-P1-C001 Saved research record

Bureau authority has statutory reservations, including Board authority described in § 1693b(a)(2).

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
EFTA supplies rulemaking authority for Regulation E; the specific overdraft opt-in conditions are in § 1005.17.
Source and pinpoint
S001, § 1693b(a)–(c); S003, § 1005.1(a); S011, 81021. govinfo.gov +2
Status / limits
S/R; current statutory-body gap disclosed.
R010-P1-C002 Saved research record

Business-purpose accounts do not qualify merely because a natural person owns or uses them.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The relevant consumer/account gateway requires a natural person and an asset account established primarily for personal, family, or household purposes.
Source and pinpoint
S001, § 1693a(2), (6); S003, §§ 1005.2(b)(1), (e). COMMERCE AND TRADE +2
Status / limits
S/R; actual purpose unknown.
R010-P1-C003 Saved research record

Trust status depends on the actual arrangement and governing law; the comment supplies additional excluded-account examples.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The account definition excludes incidental credit balances in open-end credit plans and accounts held under bona fide trust agreements.
Source and pinpoint
S001, § 1693a(2); S003, § 1005.2(b)(1)–(2), comments 2(b)(2). COMMERCE AND TRADE +1
Status / limits
S/R/O; no actual account classification.
R010-P1-C004 Saved research record

Direct/indirect holding, or access-device issuance plus agreement to provide EFT services, must fit the definition; statutory excluded-person clause remains.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Banks, savings associations, and credit unions are included financial-institution classes; the regulation also includes specified other account holders and access-device issuers.
Source and pinpoint
S001, § 1693a(9); S003, § 1005.2(i). COMMERCE AND TRADE +1
Status / limits
S/R; no named institution or charter inquiry.
R010-P1-C005 Saved research record

Predominant vehicle-dealer activity; exceptions for specified real-property services, retained direct retail credit/leases, and unrelated consumer financial services; other agency authorities preserved.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The CFPA § 1029 cross-reference is a conditional jurisdictional exclusion, not a blanket statement that all auto-related activity is outside federal EFT law.
Source and pinpoint
S017, § 5519(a)–(c), (f); S001, § 1693b(a)(2). BANKS AND BANKING +1
Status / limits
S; 2024 body, later statutory lag and all entity facts held.
R010-P1-C006 Saved research record

Consumer–FI agreement, or consumer–third-party agreement with FI notice and transfers begun. ACH membership alone is insufficient.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Regulation E account coverage requires an EFT-service agreement of the kind described in comment 3(a)-1.
Source and pinpoint
S003, § 1005.3(a), comments 3(a)-1–2. Consumer Financial Protection Bureau
Status / limits
R/O; actual agreement unknown.
R010-P1-C007 Saved research record

Must instruct debit/credit of a covered consumer account and survive applicable exclusions.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
EFT coverage includes qualifying ATM, POS, debit-card, ACH, direct-deposit/withdrawal, telephone, and computer-initiated transfers.
Source and pinpoint
S003, § 1005.3(b)(1), comment 3(b)(1)-1. Consumer Financial Protection Bureau
Status / limits
R/O; channel labels require facts.
R010-P1-C008 Saved research record

Using check information to initiate ACH can be EFT; electronic re-presentment of the original check remains within the check exclusion.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
A check converted into an ACH EFT differs from a check collected or re-presented electronically as a check.
Source and pinpoint
S003, § 1005.3(b)(2), comments 3(b)(1)-1.v and 3(c)(1)-1–2. Consumer Financial Protection Bureau +1
Status / limits
R/O; no transaction coding assumed.
R010-P1-C009 Saved research record

The specific transaction must fit § 17’s channel and service conditions.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Being an EFT does not by itself bring a transfer within the ATM/one-time debit-card fee prohibition.
Source and pinpoint
S003, § 1005.3(b); S004, § 1005.17(b)(1). Consumer Financial Protection Bureau +1
Status / limits
I from R; one-time ACH is not automatically one-time debit card.
R010-P1-C010 Saved research record

A subsequent ACH transfer to the consumer account can still be covered.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Fedwire and similar systems used primarily for interinstitutional or business transfers are excluded EFT channels under § 1005.3(c)(3).
Source and pinpoint
S003, § 3(c)(3), comments 1–3. Consumer Financial Protection Bureau
Status / limits
R/O; no full wire-transfer or UCC analysis.
R010-P1-C011 Saved research record

Ordinary purchases or cash withdrawals using a debit device against such an account are not automatically excluded.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The securities/commodities EFT exclusion depends on the transfer’s primary purpose and specified regulatory or book-entry conditions.
Source and pinpoint
S003, § 3(c)(4), comments 1–3. Consumer Financial Protection Bureau
Status / limits
R/O; separate from the credit exclusion in C021.
R010-P1-C012 Saved research record

Agreement and institution initiation without a specific consumer request; prescribed account relationships. Affiliated institutions are not automatically the same institution. Compulsory-use and specified liability provisions remain preserved.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Specified automatic transfers within the same institution, including automatic fee entries, may be excluded from the EFT definition.
Source and pinpoint
S003, § 3(c)(5), comments 1–2. Consumer Financial Protection Bureau
Status / limits
R/O; exclusion of a bookkeeping transfer does not authorize the underlying fee.
R010-P1-C013 Saved research record

A written service description can constitute a plan; infrequent use or separate requests do not necessarily remove coverage.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The telephone-transfer exclusion is conditional on absence of the specified telephone bill-payment or other written recurring-transfer plan.
Source and pinpoint
S003, § 3(c)(6), comments 1–2. Consumer Financial Protection Bureau
Status / limits
R/O; actual arrangement held.
R010-P1-C014 Saved research record

Assets $100 million or less on the preceding December 31; specified phase-out one year after the end of the year in which assets exceed that figure; preserved provisions remain applicable.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The small-institution exemption is limited to preauthorized transfers, not every EFT or every overdraft fee.
Source and pinpoint
S003, § 3(c)(7), comment 1. Consumer Financial Protection Bureau
Status / limits
R/O; sourced threshold, no entity calculation.
R010-P1-C015 Saved research record

A foreign branch of a U.S. bank is not covered unless services connect to an account in a defined state; a particular transfer’s foreign location is not conclusive.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Comment 3(a)-3 supplies a U.S.-account/state-resident geographic framework, including certain U.S. offices of foreign banks.
Source and pinpoint
S003, comment 3(a)-3; § 2(l). Consumer Financial Protection Bureau +1
Status / limits
O/R; international and actual-location questions held.
R010-P1-C016 Saved research record

Repeated separately initiated payments do not establish that definition; § 17 coding reliance remains separately relevant.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
A preauthorized EFT is authorized in advance to recur at substantially regular intervals without further consumer action.
Source and pinpoint
S003, § 2(k), comment 2(k)-1. Consumer Financial Protection Bureau
Status / limits
R/O; recurring classification unknown without facts.
R010-P1-C017 Saved research record

Payroll/government-benefit categories and specified prepaid/general-transaction products; exclusions include enumerated health, disaster, military closed-loop, gift, and needs-tested benefit arrangements. Checking/share-draft/NOW accounts are excluded from the residual prepaid category.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
“Prepaid account” is a defined category with specific inclusions and exclusions, not a synonym for every stored-value, gift, benefit, or digital-wallet product.
Source and pinpoint
S003, § 2(b)(3) and comments. Consumer Financial Protection Bureau +1
Status / limits
R/O; remote benefits, tax, and gift-card definitions not comprehensively closed.
R010-P1-C018 Saved research record

Account held by that institution; paid transaction; fee or charge; no applicable § 17(a)(1)–(4) exclusion.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
A § 17 overdraft service involves the institution charging its consumer account for paying a transaction when funds are insufficient or unavailable.
Source and pinpoint
S004, § 17(a). Consumer Financial Protection Bureau
Status / limits
R; a negative ledger entry alone is insufficient classification evidence.
R010-P1-C019 Saved research record

Includes transfers from a credit-card account, HELOC, or overdraft credit line if the specified predicate is met.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Payments pursuant to a credit line subject to Regulation Z are excluded from the § 17 overdraft-service definition.
Source and pinpoint
S004, § 17(a)(1). Consumer Financial Protection Bureau
Status / limits
R; full credit-law consequences held.
R010-P1-C020 Saved research record

Actual transfer arrangement required; the definition does not simply equate every negative balance with such a transfer.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
A service transferring funds from another account held individually or jointly by the consumer is excluded from the § 17 overdraft-service definition.
Source and pinpoint
S004, § 17(a)(2). Consumer Financial Protection Bureau
Status / limits
R; transfer charges and other laws not decided.
R010-P1-C021 Saved research record

Credit involving securities/commodities accounts extended by the specified SEC/CFTC-registered broker-dealer; a separate loan merely used to buy securities is not enough.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Specified securities/commodities credit exempt under Regulation Z § 1026.3(d) is excluded from § 17.
Source and pinpoint
S004, § 17(a)(3), comment 17(a)-1; S007, § 1026.3(d), comment 1. Consumer Financial Protection Bureau +1
Status / limits
R/O; no registration or entity lookup.
R010-P1-C022 Saved research record

Card capability to access credit during transaction authorization, settlement, or completion, and provision by issuer, affiliate, or qualifying business partner. Noncovered separate credit can independently be subject to Reg Z.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The covered separate-credit-feature exclusion is specific to the qualifying feature accessible by a hybrid prepaid-credit card.
Source and pinpoint
S004, § 17(a)(4); S007, § 1026.61(a)(1)–(2), (5). Consumer Financial Protection Bureau +2
Status / limits
R/O; no blanket exclusion of the entire prepaid account.
R010-P1-C023 Saved research record

No access to issuer/affiliate covered separate credit; required decline policy/practice, with permitted $10 and unsettled-load cushions, which may coexist; no prohibited credit/negative-balance fees or higher fees because of credit. Actual collection costs are excepted only if otherwise lawful, and late fees are not such costs. Ordinary nonprohibited fees can themselves create a negative balance.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The prepaid negative-asset-balance exclusion requires the complete § 1026.61(a)(4) conditions.
Source and pinpoint
S007, § 61(a)(4)(i)–(ii)(A)–(C) and comments. Consumer Financial Protection Bureau +2
Status / limits
R/O; sourced legal cushion, no worked calculation; ordinary checking-account overdrafts cannot borrow this exception.
R010-P1-C024 Saved research record

Traditional open-end non-home-secured card; separately signed/initialized request subject to stated pre-April-1-2019/pre-arrangement treatment; no prohibited conditioning; same prepaid terms/comparable load fees; same specified credit terms across linking and access methods. Network membership alone is insufficient to establish the arrangement.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The business-partner definition has a specific exception for qualifying traditional-credit-card links.
Source and pinpoint
S007, § 61(a)(5)(iii)(A)–(D), related comments. Consumer Financial Protection Bureau +2
Status / limits
R/O; definition only, no full credit-account compliance determination.
R010-P1-C025 Saved research record

Funding mechanism, paid transaction, credit agreement, fee causation, and any asserted debit/setoff authority must be distinguished.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
“Deposit advance,” “negative account,” and “setoff” labels do not establish a § 17 overdraft service or exclusion.
Source and pinpoint
S004, § 17(a), comment 17(b)-2; S003, § 2(f), § 3(c)(5). Consumer Financial Protection Bureau +3
Status / limits
I/U; no lending or setoff authority resolved.
R010-P1-C026 Saved research record

Establish whether the item was actually paid or returned; do not classify by an ambiguous fee label.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
A fee for returning an item unpaid is analytically different from a fee for paying an overdraft.
Source and pinpoint
S004, § 17(a), (b)(1); S003, § 3(b)(3). Consumer Financial Protection Bureau +2
Status / limits
R/I; § 17’s paid-overdraft prohibition does not establish NSF legality.
R010-P1-C027 Saved research record

Notice plus proceeding with the underlying transaction can authorize that particular fee EFT; POS notice/copy conditions apply. Comment 1 excludes the account-holding FI’s own return/pay fee from this particular authorization provision.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Electronic collection of a returned-item fee has its own authorization rule, distinct from overdraft opt-in.
Source and pinpoint
S003, § 3(b)(3)(i)–(ii), comments 1–4. Consumer Financial Protection Bureau +1
Status / limits
R/O; this rule cannot be imported to infer § 17 opt-in from account use.
R010-P1-C028 Saved research record

§ 16 operator does not hold the account; fee notice with amount must precede commitment, and the consumer must elect to continue.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
An ATM operator’s access/balance-inquiry fee is distinct from the account-holding institution’s overdraft fee.
Source and pinpoint
S003, § 1005.16(a)–(d); S001, § 1693b(d)(3). Consumer Financial Protection Bureau +1
Status / limits
R/S; continuing after an ATM fee screen does not itself establish separate overdraft consent.
R010-P1-C029 Saved research record

Notice, reasonable opportunity, affirmative consent, and confirmation with revocation information; historical timing in (c).

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Four cumulative conditions govern charging for a covered paid ATM/one-time debit-card overdraft.
Source and pinpoint
S004, § 17(b)(1)(i)–(iv). ecfr.gov
Status / limits
R; affirmative consent alone is insufficient.
R010-P1-C030 Saved research record

Oral notice does not satisfy the written/electronic disclosure requirement.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The notice must be segregated, written or agreed electronic, clear, understandable, and retainable.
Source and pinpoint
S004, § 17(b)(1)(i); S003, § 4(a); S010, 31667. ecfr.gov +2
Status / limits
R/O/H; actual delivery and retained form unknown.
R010-P1-C031 Saved research record

Includes consent, prescribed information, access demonstration, and relevant exceptions when applicable.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
E-Sign § 7001(c) supplies a general consumer-electronic-record framework when law requires information in writing.
Source and pinpoint
S008, § 7001(b), (c)(1)–(6). uscode.house.gov
Status / limits
S; not automatically imported into § 17.
R010-P1-C032 Saved research record

Consumer agreement to electronic delivery remains required by § 17’s own text.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The § 17 adopting explanation expressly treats electronic disclosures under that section as outside E-Sign’s consumer-consent requirements, while retaining clarity and retainability.
Source and pinpoint
S009, footnote 32, 59041–59042, indices 8–9; current § 17(b)(1)(i), (iv). govinfo.gov +2
Status / limits
H explaining R; not a withdrawn CFPB circular; other documents’ E-Sign treatment held.
R010-P1-C033 Saved research record

Mail form, readily available telephone line, electronic choice/affirmation, and in-person form are examples; not a mandate to offer all four.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Reasonable opportunity includes reasonable means of communicating consent.
Source and pinpoint
S004, comment 17(b)-4.i–iv. Consumer Financial Protection Bureau
Status / limits
O; actual opportunity unknown.
R010-P1-C034 Saved research record

Includes separation from electronic-delivery consent. General preprinted account language and preselected opt-in boxes do not satisfy it.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Overdraft consent must be obtained separately from other consents and acknowledgments.
Source and pinpoint
S004, comment 17(b)-6. Consumer Financial Protection Bureau
Status / limits
O; actual consent evidence held.
R010-P1-C035 Saved research record

Different statutory/regulatory forms of acceptance must not be conflated.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Account use or acceptance of an access device cannot, without an authorized separate basis, be substituted for affirmative overdraft consent.
Source and pinpoint
S004, § 17(b)(1)(iii), comments 17(b)-5–6; S003, § 2(a). Consumer Financial Protection Bureau +1
Status / limits
I from R/O; no implied-consent finding.
R010-P1-C036 Saved research record

No selected box/signature means no opt-in; offered accounts must comply with (b)(2)–(3).

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
An institution may require an account-opening yes/no choice, but silence is not opt-in.
Source and pinpoint
S004, comment 17(b)-5. Consumer Financial Protection Bureau
Status / limits
O; not permission to require the “yes” answer.
R010-P1-C037 Saved research record

Writing, or electronic if agreed; oral confirmation does not satisfy the disclosure requirement.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Confirmation must record the consent and include the right to revoke; a completed notice copy or acknowledgment letter can suffice.
Source and pinpoint
S004, § 17(b)(1)(iv), comment 17(b)-7. Consumer Financial Protection Bureau
Status / limits
R/O; actual content and delivery unknown.
R010-P1-C038 Saved research record

Comment recognizes compliance through reasonable procedures designed to ensure that timing. Consumer receipt is not required before a fee; later fee posting alone does not cure the payment-timing issue.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The confirmation timing standard concerns transactions paid after confirmation is mailed or delivered.
Source and pinpoint
S004, comment 17(b)-7; S010, 31667–31668. Consumer Financial Protection Bureau +1
Status / limits
O/H; actual procedures and any error remain unresolved.
R010-P1-C039 Saved research record

Later consent does not retrospectively validate fees for earlier paid transactions.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Covered overdraft fees may concern only overdrafts paid on or after receipt of affirmative consent, subject also to confirmation requirements.
Source and pinpoint
S004, comment 17(c)-1. Consumer Financial Protection Bureau
Status / limits
O; event times unknown.
R010-P1-C040 Saved research record

Specific § 17 rules govern permissible content and format.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The opt-in notice must be substantially similar to A-9, include every applicable required item, and contain only specified or permitted information.
Source and pinpoint
S004, § 17(d). Consumer Financial Protection Bureau
Status / limits
R; no current form visual-comparison conclusion.
R010-P1-C041 Saved research record

Include discretion/possible decline explanation as applicable.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The notice must explain the service and relevant transaction types; other-transaction policies must not overshadow the opt-in right.
Source and pinpoint
S004, § 17(d)(1), comment 17(d)-1. Consumer Financial Protection Bureau
Status / limits
R/O; actual policy and accuracy unknown.
R010-P1-C042 Saved research record

Amount can vary by number of overdrafts, overdraft size, or other factors.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
All applicable overdraft fees must be disclosed, including daily, sustained, and negative-balance fees; a variable fee requires its maximum.
Source and pinpoint
S004, § 17(d)(2), comment 17(d)-2. Consumer Financial Protection Bureau
Status / limits
R/O; no actual fee amount supplied or calculated.
R010-P1-C043 Saved research record

This is a disclosure requirement; it is not a national numerical fee cap or blanket permission under other law.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The notice must disclose the maximum number of fees per day, or disclose that there is no limit.
Source and pinpoint
S004, § 17(d)(3). Consumer Financial Protection Bureau
Status / limits
R/I.
R010-P1-C044 Saved research record

Methods must match what the institution actually offers.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The notice must explain the right to opt in and the means available for doing so.
Source and pinpoint
S004, § 17(d)(4), comment 17(d)-3. Consumer Financial Protection Bureau
Status / limits
R/O.
R010-P1-C045 Saved research record

Both offered means disclose both; one means disclose that one; neither means omit that reference. Other alternatives may be listed.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Offered linked-credit and same-institution account-transfer alternatives must be disclosed as applicable.
Source and pinpoint
S004, § 17(d)(5), comment 17(d)-5. Consumer Financial Protection Bureau
Status / limits
R/O; offering an alternative is not established here.
R010-P1-C046 Saved research record

Only as applicable; optional initial revocation wording does not eliminate mandatory revocation information in confirmation.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Section 17(d)(6) permits specified additional content concerning other-transaction choices, associated returned-item/merchant fees, revocation, and historical existing-account wording.
Source and pinpoint
S004, § 17(d)(6). Consumer Financial Protection Bureau
Status / limits
R.
R010-P1-C047 Saved research record

Reasonable account-identification methods are permitted; no identifiers are entered in this pass.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
A-9 can be tailored to offered consent methods; a tear-off form and a decline box are not invariably required.
Source and pinpoint
S004, comments 17(d)-3–4. Consumer Financial Protection Bureau
Status / limits
O; no specific form approved.
R010-P1-C048 Saved research record

Accurate use of appropriate model language concerns proper disclosure form; specific § 17 content limits remain.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Appendix A comments do not give blanket approval of institutional forms or every fee charged under them.
Source and pinpoint
S005, Appendix A comments 1–3; S004, § 17(d). Consumer Financial Protection Bureau +1
Status / limits
O/I; no individualized safe-harbor or liability decision.
R010-P1-C049 Saved research record

The 2011 text-continuity statement supports historical comparison, not an assertion of current visual inspection.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Historical A-9 text was fully read; current A-9 pixels were not.
Source and pinpoint
S005–S006; S011, 81021. federalreserve.gov +1
Status / limits
H/U; current visual/read completeness remains partial.
R010-P1-C050 Saved research record

Other material may be in the same mailing while the opt-in notice remains segregated.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Section 4’s general permission to combine disclosures does not override § 17’s specific segregation and content restrictions.
Source and pinpoint
S003, § 4(b); S004, § 17(b)(1)(i), (d); S010, 31671. Consumer Financial Protection Bureau +2
Status / limits
R/H/I.
R010-P1-C051 Saved research record

Applies alongside the required content and clarity standards.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Regulation E permits another disclosure language if English is available on request.
Source and pinpoint
S003, § 4(a)(2), comment 4(a)-2. Consumer Financial Protection Bureau
Status / limits
R/O; actual language/accessibility facts unknown.
R010-P1-C052 Saved research record

Separate § 17(e) governs whose consent or revocation binds the account.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
For joint accounts, one set of required disclosures may be provided to any account holder.
Source and pinpoint
S003, § 4(c)(2). Consumer Financial Protection Bureau
Status / limits
R; disclosure delivery is not itself consent.
R010-P1-C053 Saved research record

Does not itself create a § 17 exception for the account-holding institution.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Institutions offering EFT services jointly may allocate compliance by agreement, but § 4(d)’s knowledge limitation expressly concerns §§ 7 and 8.
Source and pinpoint
S003, § 4(d). Consumer Financial Protection Bureau
Status / limits
R/I; actual actor allocation unknown.
R010-P1-C054 Saved research record

Apply the same payment criteria consistently; this does not compel payment of every check or ACH item.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
An institution cannot condition paying check/ACH/other overdrafts on ATM/debit opt-in or decline them because opt-in was refused.
Source and pinpoint
S004, § 17(b)(2), comment 17(b)(2)-1. ecfr.gov +1
Status / limits
R/O.
R010-P1-C055 Saved research record

Includes interest paid, fees, card capabilities, minimum balance, and online bill pay; exception is the protected overdraft service itself.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Consumers declining opt-in must receive the same other account terms, conditions, and features.
Source and pinpoint
S004, § 17(b)(3), comment 17(b)(3)-1. Consumer Financial Protection Bureau
Status / limits
R/O.
R010-P1-C056 Saved research record

Actual eligibility and account terms required.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Independently justified limited-feature accounts remain possible, but refusal to opt in cannot be used to divert an otherwise eligible consumer to them.
Source and pinpoint
S004, comment 17(b)(3)-2. Consumer Financial Protection Bureau
Status / limits
O; no creditworthiness decision.
R010-P1-C057 Saved research record

Debit of principal is preserved only if permitted under other applicable law.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Without opt-in, the institution may pay the covered transaction but cannot charge for paying it.
Source and pinpoint
S004, comment 17(b)-2. Consumer Financial Protection Bureau
Status / limits
O; no debt-validity, collection, or setoff conclusion.
R010-P1-C058 Saved research record

Contractual or other obligations are not adjudicated here.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Opt-in does not guarantee authorization or payment of an overdraft.
Source and pinpoint
S004, comment 17(b)-3. Consumer Financial Protection Bureau
Status / limits
O.
R010-P1-C059 Saved research record

Third-party issuance without the “on behalf of” relationship is outside that stated scope.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Section 17(b) covers the relevant debit card only when issued by or on behalf of the account-holding institution.
Source and pinpoint
S004, comment 17(b)-1.i. Consumer Financial Protection Bureau
Status / limits
O; actual issuance/funding relationship unknown.
R010-P1-C060 Saved research record

Channel location does not substitute for recurring/one-time classification.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
A one-time debit-card transaction can qualify whether conducted at POS, online, or by telephone.
Source and pinpoint
S004, comment 17(b)-1.iii. Consumer Financial Protection Bureau
Status / limits
O.
R010-P1-C061 Saved research record

After that condition is met, merchant/institution/third-party coding may be relied upon.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The coding reliance rule requires systems adapted to identify one-time versus recurring transactions.
Source and pinpoint
S004, comment 17(b)-1.ii. Consumer Financial Protection Bureau
Status / limits
O; coding accuracy, system adaptation, and actual reliance not established.
R010-P1-C062 Saved research record

An institution charging no fees for these paid overdrafts need not perform the § 17(b)(1)(i)–(iv) notice/opt-in process for that fee-free service.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The fee prohibition applies to all otherwise covered institutions, including those with a general decline policy.
Source and pinpoint
S004, comment 17(b)-1.iv. Consumer Financial Protection Bureau
Status / limits
O; no general policy-based fee exception.
R010-P1-C063 Saved research record

Commentary’s express example includes intervening transactions reducing funds before settlement.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Positive authorization followed by negative settlement does not excuse a covered fee where the required opt-in was absent.
Source and pinpoint
S004, comment 17(b)-1.iv. Consumer Financial Protection Bureau
Status / limits
O; other timing configurations and actual balances held.
R010-P1-C064 Saved research record

Requires fee classification and sole attribution.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
With no opt-in, a fee based on negative-balance amount is prohibited when that balance is solely attributable to protected ATM/one-time debit transactions.
Source and pinpoint
S004, comment 17(b)-8. Consumer Financial Protection Bureau
Status / limits
O.
R010-P1-C065 Saved research record

Does not validate a separate per-item fee for an unconsented protected card transaction.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Section 17 does not prohibit that amount-based fee when the negative balance is wholly or partly attributable to a check, ACH, or another nonprotected transaction.
Source and pinpoint
S004, comment 17(b)-8. Consumer Financial Protection Bureau
Status / limits
O; other law/contract held.
R010-P1-C066 Saved research record

Fee substance and causation govern; a new fee label does not answer causation.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
With no opt-in, daily/sustained/negative-balance/similar fees are prohibited when the negative balance is solely attributable to protected transactions.
Source and pinpoint
S004, comment 17(b)-9.i. Consumer Financial Protection Bureau
Status / limits
O/I.
R010-P1-C067 Saved research record

Subject to the timing rule in C068 and actual remaining balance attribution.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Section 17 does not prohibit those ongoing fees where a negative balance is wholly or partly attributable to nonprotected transactions.
Source and pinpoint
S004, comment 17(b)-9.i. Consumer Financial Protection Bureau
Status / limits
O; no all-law fee authorization.
R010-P1-C068 Saved research record

An earlier protected card overdraft does not supply that start date.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
For a mixed negative balance, the ongoing-fee timing anchor is when the nonprotected transaction was paid into overdraft.
Source and pinpoint
S004, comment 17(b)-9.i, -9.ii.C. Consumer Financial Protection Bureau
Status / limits
O; contractual period, units, calendar, and events unknown.
R010-P1-C069 Saved research record

Later deposits can alter which debit component remains; associated fees matter in the examples. Their sample amounts and periods are not national legal thresholds.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The official mixed-balance examples depend on expressly stipulated posting and deposit-allocation assumptions.
Source and pinpoint
S004, comment 17(b)-9.ii, examples A–C. Consumer Financial Protection Bureau
Status / limits
O/I; no mandatory universal allocation method or actual calculation inferred.
R010-P1-C070 Saved research record

This alternative avoids calculating allocation of partial deposits; it is an alternative, not the only required method.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
A conservative alternative permits avoiding ongoing fees unless the outstanding negative balance is solely attributable to nonprotected transactions.
Source and pinpoint
S004, comment 17(b)-9.iii. Consumer Financial Protection Bureau
Status / limits
O.
R010-P1-C071 Saved research record

Joint relationship must actually exist.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Any joint consumer’s affirmative consent binds the account; any joint consumer’s revocation likewise revokes account consent.
Source and pinpoint
S004, § 17(e). Consumer Financial Protection Bureau
Status / limits
R; no requirement that every joint holder separately opt in or revoke.
R010-P1-C072 Saved research record

Opt-in follows the notice’s manner; revocation access must reflect available consent methods.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
A consumer may opt in at any time and revoke at any time through the means made available for consent.
Source and pinpoint
S004, § 17(f). Consumer Financial Protection Bureau
Status / limits
R.
R010-P1-C073 Saved research record

The section supplies no fixed number of days for this implementation.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Revocation must be implemented as soon as reasonably practicable.
Source and pinpoint
S004, § 17(f). Consumer Financial Protection Bureau
Status / limits
R; actual elapsed time and practicability unknown.
R010-P1-C074 Saved research record

Does not establish that earlier fees were lawful or excuse unreasonable implementation delay.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Revocation alone does not require reversal of fees assessed before implementation of the revocation request.
Source and pinpoint
S004, comment 17(f)-1. Consumer Financial Protection Bureau
Status / limits
O/I; separate grounds remain held.
R010-P1-C075 Saved research record

Termination is possible; excessive use is the comment’s example.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Consent continues until revoked by the consumer or the institution terminates the service.
Source and pinpoint
S004, § 17(g), comment 17(g)-1. Consumer Financial Protection Bureau
Status / limits
R/O; no actual termination or reconsent finding.
R010-P1-C076 Saved research record

Effective January 19, 2010; mandatory compliance July 1, 2010, with the specific existing-account transition.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The original final rule distinguished its effective date from its mandatory compliance date.
Source and pinpoint
S009, 74 FR 59033, index 0. govinfo.gov
Status / limits
H; historical regulatory dates, not individual deadlines.
R010-P1-C077 Saved research record

The 2010 clarification removed former (b)(4); its correction preserved the four subparagraph requirements by specifying amendment of the introductory text.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Source and pinpoint
S010, 75 FR 31671–31672; correction 33681. govinfo.gov +1
Trigger, conditions, exceptions
Both effective July 6, 2010.
Status / limits
H; former (b)(4) is not a current fee exception.
R010-P1-C078 Saved research record

Effective December 30, 2011; transfer of relevant rulemaking authority described as July 21, 2011.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The 2011 rule recodified Regulation E into Part 1005 without new substantive obligations.
Source and pinpoint
S011, 76 FR 81020–81021. govinfo.gov
Status / limits
H; current duties come from current text.
R010-P1-C079 Saved research record

Covered fees assessed on or after August 15, 2010 require § 17(b)(1) compliance and affirmative consent.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Accounts opened before July 1, 2010 were not permanently grandfathered out of opt-in.
Source and pinpoint
S004, § 17(c)(1). Consumer Financial Protection Bureau
Status / limits
R; opening date/fee facts unknown.
R010-P1-C080 Saved research record

Also apply consent/payment and confirmation timing.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Accounts opened on or after July 1, 2010 require compliance and consent before covered fees are assessed.
Source and pinpoint
S004, § 17(c)(2), comment 17(c)-1. Consumer Financial Protection Bureau
Status / limits
R/O; no actual event-date calculation.
R010-P1-C081 Saved research record

Statute preserves greater protection and expressly excepts a waiver given in settlement of a dispute or action.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Opt-in is not a waiver of all EFTA protections or every other fee limitation.
Source and pinpoint
S002, § 1693l; S004, § 17. uscode.house.gov +1
Status / limits
S/I; no settlement, enforceability, or remedy decision.
R010-P1-C082 Saved research record

It was a final rule with a future effective date when issued.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The 2024 overdraft final rule originally stated an October 1, 2025 effective date.
Source and pinpoint
S012, 89 FR 106768 and § V. govinfo.gov +1
Status / limits
H/D; that planned date is not treated as having activated the disapproved rule.
R010-P1-C083 Saved research record

Approved May 9, 2025; identifies 89 FR 106768, December 30, 2024.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Public Law 119-10 disapproved the specifically identified 2024 final rule and gave it no force or effect.
Source and pinpoint
S013, 139 Stat. 53, entire operative sentence. govinfo.gov
Status / limits
S; exact enacted effect read.
R010-P1-C084 Saved research record

The preexisting Regulation Z-line exclusion still exists on its own terms.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The disapproved rule’s added comment 17(a)-2 and new covered-overdraft framework cannot be used here as current requirements or exclusions.
Source and pinpoint
S012, 106837, index 69; S013; current S004. govinfo.gov +2
Status / limits
D/R/I; no new fee cap inferred from the disapproved rule.
R010-P1-C085 Saved research record

This report uses May 9, 2025 for enactment/approval.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The CFPB resource page’s May 12 signing date conflicts with the enacted public law’s May 9 approval date.
Source and pinpoint
S014 featured paragraph; S013 heading and approval line. Consumer Financial Protection Bureau +1
Status / limits
Verified source discrepancy; resource date not substituted for statute.
R010-P1-C086 Saved research record

Circulars 2022-06 and 2024-05 are withdrawn guidance under the inspected official status materials.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Source and pinpoint
S015 register and 90 FR 20084–20086; S016 publisher pages. Consumer Financial Protection Bureau +4
Trigger, conditions, exceptions
Withdrawal applicable May 12, 2025.
Status / limits
W; historical analyses not current-rule substitutes.
R010-P1-C087 Saved research record

Distinguish guidance status from the continued text and scope of statutes/regulations.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
Withdrawal of those circulars does not itself repeal the statute/regulation or affirmatively validate all fees discussed in them.
Source and pinpoint
S015’s specified withdrawal action; S002–S004. federalregister.gov +2
Status / limits
I from S/R/W; other legal grounds remain open.
R010-P1-C088 Saved research record

Other applicable statutory, contract, disclosure, balance-method, and judicial questions need their own authority and facts.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
A stipulated compliant opt-in does not settle the full legality of an authorization-positive/settlement-negative fee.
Source and pinpoint
S004, § 17 and comment 17(b)-1.iv; C081, C086–C087. Consumer Financial Protection Bureau +2
Status / limits
U; no current broader liability theory asserted.
R010-P1-C089 Saved research record

All actual identity, account, balance, timing, agreement, and transaction facts remain blank.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The generic rules cannot determine actual consent, causation, coding, contract compliance, liability, eligibility, or relief without facts not supplied and not searched.
Source and pinpoint
Analytical limit of C002–C088; user scope.
Status / limits
U; no individual or class-action determination.
R010-P1-C090 Saved research record

eCFR title currency through October 23; selected OLRC labels through October 20; older statutory recoveries; unread current image.

Recorded check status: conditional framework reviewed source currentness form actualfact limits retained

Precise claim / area
The checked current-resource labels and retrieved bodies support this bounded report, but do not certify all intervening legislation, publications, litigation, or current form pixels.
Source and pinpoint
S001–S018 and failure log. ecfr.gov +2
Status / limits
U / methodological qualification; no component or parent closure.

Sources, pinpoints and access limits

Keep the source version, actual read extent and jurisdiction with the proposition. A link or researcher access claim is not a substitute for an operative primary passage.

R010-P1-S001 Saved research record

Congress; GPO, EFTA definitions and rulemaking authority. https://www.govinfo.gov/content/pkg/USCODE-2024-title15/html/USCODE-2024-title15-chap41-subchapVI-sec1693a.htm ; https://www.govinfo.gov/content/pkg/USCODE-2024-title15/pdf/USCODE-2024-title15-chap41-subchapVI-sec1693b.pdf

Recorded check status: fresh selected historical body

Exact provisions; printed page / PDF index
§ 1693a operative definitions, especially (2), (6)–(11); § 1693b(a)–(e), particularly (a)–(d). PDF pp. 1645–1648, indices 0–3; its first page also contains the end of § 1693a.
Version, effective predicate, status
Official 2024 Edition bodies. Statutory authority and definitions; not a representation of a fully audited October 2026 statutory edition.
Fresh-read extent and currentness limits
Fresh, body read. Current OLRC versions of §§ 1693a–b failed; recovery was the official 2024 edition. 2025–2026 statutory lag remains open. COMMERCE AND TRADE +2
Direct source URLs
https://www.govinfo.gov/content/pkg/USCODE-2024-title15/html/USCODE-2024-title15-chap41-subchapVI-sec1693a.htm
https://www.govinfo.gov/content/pkg/USCODE-2024-title15/pdf/USCODE-2024-title15-chap41-subchapVI-sec1693b.pdf
https://www.govinfo.gov/content/pkg/USCODE-2024-title15/html/USCODE-2024-title15-chap41-subchapVI-sec1693a.htm?utm_source=chatgpt.com
https://www.govinfo.gov/content/pkg/USCODE-2024-title15/pdf/USCODE-2024-title15-chap41-subchapVI-sec1693b.pdf?utm_source=chatgpt.com
R010-P1-S002 Saved research record

Congress; OLRC, 15 USC 1693l—Waiver of rights. https://uscode.house.gov/us/usc/119-134/t15/s1693l/

Recorded check status: fresh selected historical body and current route failure

Exact provisions; printed page / PDF index
Entire operative paragraph and source credit; HTML, page/index N/A.
Version, effective predicate, status
Header states laws in effect through PL 119-134, October 20, 2026. Applies to agreements waiving EFTA rights, with express exceptions.
Fresh-read extent and currentness limits
Fresh, complete operative paragraph read. A direct repeat retrieval failed; reopening the previously retrieved reference recovered the body. Compilation label is not a session-law lag audit. uscode.house.gov
Direct source URLs
https://uscode.house.gov/us/usc/119-134/t15/s1693l/
https://uscode.house.gov/us/usc/119-134/t15/s1693l/?utm_source=chatgpt.com
R010-P1-S003 Saved research record

CFPB, Regulation E gateway, general disclosures, and ATM-operator distinction. https://www.consumerfinance.gov/rules-policy/regulations/1005/1/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/2/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/3/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/4/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/16/

Recorded check status: fresh selected partial group

Exact provisions; printed page / PDF index
§ 1(a)–(b); necessary § 2 definitions, including (a), (b), (e), (f), (h), (i), (k), (l), with relevant comments; § 3(a)–(c) and embedded interpretations; § 4(a)–(d) and comments; § 16(a)–(d). HTML, page/index N/A.
Version, effective predicate, status
Agency pages labeled current regulation. Scope and exceptions depend on the account, actor, agreement, transfer, and product.
Fresh-read extent and currentness limits
Fresh bodies read. Full § 2(b)(3) text was read, but its remote tax, benefits, and gift-card cross-references were not comprehensively followed. Full error-resolution, unauthorized-transfer, remittance, and broader disclosure regimes were not examined. Same Part 1005 as S004–S005, not independent corroboration. Consumer Financial Protection Bureau +6
Direct source URLs
https://www.consumerfinance.gov/rules-policy/regulations/1005/1/
https://www.consumerfinance.gov/rules-policy/regulations/1005/2/
https://www.consumerfinance.gov/rules-policy/regulations/1005/3/
https://www.consumerfinance.gov/rules-policy/regulations/1005/4/
https://www.consumerfinance.gov/rules-policy/regulations/1005/16/
https://www.consumerfinance.gov/rules-policy/regulations/1005/1/?utm_source=chatgpt.com
https://www.consumerfinance.gov/rules-policy/regulations/1005/2/?utm_source=chatgpt.com
https://www.consumerfinance.gov/rules-policy/regulations/1005/3/?utm_source=chatgpt.com
https://www.consumerfinance.gov/rules-policy/regulations/1005/4/?utm_source=chatgpt.com
https://www.consumerfinance.gov/rules-policy/regulations/1005/16/?utm_source=chatgpt.com
R010-P1-S004 Saved research record

CFPB/OFR/GPO, 12 CFR 1005.17—Requirements for overdraft services, and official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1005/17/ ; https://www.ecfr.gov/current/title-12/chapter-X/part-1005/subpart-A/section-1005.17 ; https://www.govinfo.gov/link/cfr/12/1005?link-type=pdf&sectionnum=17&year=mostrecent

Recorded check status: fresh selected body

Exact provisions; printed page / PDF index
Entire § 17(a)–(g) and all embedded § 17 official comments, including 17(b)-9.ii.A–C and -9.iii. Annual PDF pp. 204–206, indices 0–2, § 17 only.
Version, effective predicate, status
CFPB current label; latest eCFR read displayed Title 12 through 2026-10-23 and described eCFR as authoritative but unofficial. PDF resolves to 1-1-26 Edition, source note 76 FR 81023, amended 81 FR 84328. Historical § 17(c) triggers remain printed in current text.
Fresh-read extent and currentness limits
Fresh, complete necessary operative section and interpretations read. Annual PDF parsed text read; screenshots did not yield inspectable pixels. No full post-October-23 publication-lag audit. These are reproductions of one regulatory instrument. ecfr.gov +5
Direct source URLs
https://www.consumerfinance.gov/rules-policy/regulations/1005/17/
https://www.ecfr.gov/current/title-12/chapter-X/part-1005/subpart-A/section-1005.17
https://www.govinfo.gov/link/cfr/12/1005?link-type=pdf&sectionnum=17&year=mostrecent
https://www.consumerfinance.gov/rules-policy/regulations/1005/17/?utm_source=chatgpt.com
https://www.ecfr.gov/current/title-12/chapter-X/part-1005/subpart-A/section-1005.17?utm_source=chatgpt.com
https://www.govinfo.gov/link/cfr/12/1005?link-type=pdf&sectionnum=17&year=mostrecent&utm_source=chatgpt.com
R010-P1-S005 Saved research record

CFPB/OFR, Current Appendix A, Model A-9, and Appendix A interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1005/a/ ; https://www.consumerfinance.gov/rules-policy/regulations/1005/interp-a/ ; https://files.consumerfinance.gov/f/ER27DE11.000.png ; https://www.ecfr.gov/current/title-12/chapter-X/part-1005/appendix-Appendix%20A%20to%20Part%201005

Recorded check status: fresh selected partial group

Exact provisions; printed page / PDF index
A-9 heading and linked graphic; Appendix A comments 1–3; complete A-9-specific instructions in § 17(d) and comments 17(d)-1–5, S004. HTML/PNG; printed page/index N/A.
Version, effective predicate, status
Current agency appendix presentation; eCFR appendix currency label through 2026-10-23.
Fresh-read extent and currentness limits
Fresh, partial form read. Current instructions and appendix comments read. Current graphic returned an image placeholder, not visible pixels or complete extracted form text. Current visual form comparison remains unresolved. Consumer Financial Protection Bureau +3
Direct source URLs
https://www.consumerfinance.gov/rules-policy/regulations/1005/a/
https://www.consumerfinance.gov/rules-policy/regulations/1005/interp-a/
https://files.consumerfinance.gov/f/ER27DE11.000.png
https://www.ecfr.gov/current/title-12/chapter-X/part-1005/appendix-Appendix%20A%20to%20Part%201005
https://www.consumerfinance.gov/rules-policy/regulations/1005/a/?utm_source=chatgpt.com
https://www.consumerfinance.gov/rules-policy/regulations/1005/interp-a/?utm_source=chatgpt.com
https://www.ecfr.gov/current/title-12/chapter-X/part-1005/appendix-Appendix%20A%20to%20Part%201005?utm_source=chatgpt.com
https://www.consumerfinance.gov/rules-policy/regulations/1005/A/?utm_source=chatgpt.com
R010-P1-S006 Saved research record

Federal Reserve, generic Model A-9 distributed with the 2009 final rule. https://www.federalreserve.gov/newsevents/pressreleases/files/bcreg20091112a3.pdf ; discovery page: https://www.federalreserve.gov/newsevents/pressreleases/bcreg20091112a.htm

Recorded check status: fresh selected historical body

Exact provisions; printed page / PDF index
Complete one-page form body, parsed lines 0–35; unpaginated, PDF index 0.
Version, effective predicate, status
Historical November 12, 2009 distribution. S011 expressly describes the 2011 A-9 as substantively identical except “website” spelling.
Fresh-read extent and currentness limits
Fresh, complete parsed historical form text read; pixels not read. PDF metadata labels it an opt-out form, but the actual body and publisher link identify the relevant A-9 consent form; metadata was not substituted for the body. Illustrative fees and periods are not legal limits. Press release used for discovery, not operative dates. federalreserve.gov +2
Direct source URLs
https://www.federalreserve.gov/newsevents/pressreleases/files/bcreg20091112a3.pdf
https://www.federalreserve.gov/newsevents/pressreleases/bcreg20091112a.htm
https://www.federalreserve.gov/newsevents/pressreleases/files/bcreg20091112a3.pdf?utm_source=chatgpt.com
https://www.federalreserve.gov/newsevents/pressreleases/bcreg20091112a.htm?utm_source=chatgpt.com
R010-P1-S007 Saved research record

CFPB, Regulation Z cross-references necessary to § 17(a). https://www.consumerfinance.gov/rules-policy/regulations/1026/3/ ; https://www.consumerfinance.gov/rules-policy/regulations/1026/61/

Recorded check status: fresh selected partial group

Exact provisions; printed page / PDF index
§ 1026.3(d), comment 3(d)-1; § 1026.61(a)(1)–(5), especially (a)(2), (a)(4), (a)(5)(iii)(D), and necessary embedded comments. HTML, page/index N/A.
Version, effective predicate, status
Agency current-regulation presentation. Applied only to the exclusions expressly incorporated by § 17(a).
Fresh-read extent and currentness limits
Fresh, necessary definition/exception bodies read. Full Reg Z lending, APR, origination, repayment, security, and remedy regimes remain held. Historical prepaid-effective-date chain was not comprehensively audited; no historical product application is made. Consumer Financial Protection Bureau +7
Direct source URLs
https://www.consumerfinance.gov/rules-policy/regulations/1026/3/
https://www.consumerfinance.gov/rules-policy/regulations/1026/61/
https://www.consumerfinance.gov/rules-policy/regulations/1026/3/?utm_source=chatgpt.com
https://www.consumerfinance.gov/rules-policy/regulations/1026/61/?utm_source=chatgpt.com
R010-P1-S008 Saved research record

Congress; OLRC, 15 USC 7001—E-Sign general rule. https://uscode.house.gov/us/usc/119-134/t15/s7001/

Recorded check status: fresh selected body

Exact provisions; printed page / PDF index
§ 7001(a), (b), (c)(1)–(6); additional text and effective-date notes also returned. HTML, page/index N/A.
Version, effective predicate, status
Header through PL 119-134, October 20, 2026. § 7001(c) concerns information legally required in writing; see S009 for the § 17-specific adopting explanation.
Fresh-read extent and currentness limits
Fresh, complete relevant subsections read. Used to distinguish the general statute from the special overdraft disclosure treatment, not to create an extra § 17 consent condition. Compilation-lag qualification retained. uscode.house.gov
Direct source URLs
https://uscode.house.gov/us/usc/119-134/t15/s7001/
https://uscode.house.gov/us/usc/119-134/t15/s7001/?utm_source=chatgpt.com
R010-P1-S009 Saved research record

Federal Reserve, Electronic Fund Transfers—2009 final rule and official staff commentary. https://www.federalregister.gov/documents/2009/11/17/E9-27474/electronic-fund-transfers ; https://www.govinfo.gov/content/pkg/FR-2009-11-17/pdf/E9-27474.pdf

Recorded check status: fresh selected historical partial group

Exact provisions; printed page / PDF index
74 FR 59033–59056, 24-page PDF, indices 0–23. Relevant read: dates at 59033 / 0; notice discussion and complete footnote 32 at 59041–59042 / 8–9; confirmation discussion 59043 / 10.
Version, effective predicate, status
Published 2009-11-17; effective 2010-01-19; mandatory compliance 2010-07-01, with existing-account treatment in § 17(c). Historical adopting rule; subsequently clarified and recodified.
Fresh-read extent and currentness limits
Fresh, selected necessary body passages read, not a claimed full 24-page read. Official PDF verified the electronic-delivery explanation. Original former § 205.17(b)(4) is not used as current text. govinfo.gov +3
Direct source URLs
https://www.federalregister.gov/documents/2009/11/17/E9-27474/electronic-fund-transfers
https://www.govinfo.gov/content/pkg/FR-2009-11-17/pdf/E9-27474.pdf
https://www.federalregister.gov/documents/2009/11/17/E9-27474/electronic-fund-transfers?utm_source=chatgpt.com
https://www.govinfo.gov/content/pkg/FR-2009-11-17/pdf/E9-27474.pdf?utm_source=chatgpt.com
R010-P1-S010 Saved research record

Federal Reserve, 2010 clarification and correction. https://www.federalregister.gov/documents/2010/06/04/2010-13280/electronic-fund-transfers ; https://www.govinfo.gov/content/pkg/FR-2010-06-04/pdf/2010-13280.pdf ; https://www.federalregister.gov/documents/2010/06/15/2010-14353/electronic-fund-transfers ; https://www.govinfo.gov/content/pkg/FR-2010-06-15/pdf/2010-14353.pdf

Recorded check status: fresh selected historical partial group

Exact provisions; printed page / PDF index
75 FR 31665–31673, indices 0–8: scope/confirmation discussion, balance-fee discussion, content instructions, and amendatory text. Correction at 33681 / index 0, operative correction fully read.
Version, effective predicate, status
Both effective 2010-07-06. Clarification removes former (b)(4); correction specifies revision of the (b)(1) introductory text, preserving the subparagraph requirements.
Fresh-read extent and currentness limits
Fresh, selected relevant clarification passages and complete correction read. Current complete comments are independently read as the same regulation in S004. Historical PDF’s final page also contains another rule, which is not adopted as a foundation. federalregister.gov +4
Direct source URLs
https://www.federalregister.gov/documents/2010/06/04/2010-13280/electronic-fund-transfers
https://www.govinfo.gov/content/pkg/FR-2010-06-04/pdf/2010-13280.pdf
https://www.federalregister.gov/documents/2010/06/15/2010-14353/electronic-fund-transfers
https://www.govinfo.gov/content/pkg/FR-2010-06-15/pdf/2010-14353.pdf
https://www.federalregister.gov/documents/2010/06/04/2010-13280/electronic-fund-transfers?utm_source=chatgpt.com
https://www.govinfo.gov/content/pkg/FR-2010-06-04/pdf/2010-13280.pdf?utm_source=chatgpt.com
https://www.federalregister.gov/documents/2010/06/15/2010-14353/electronic-fund-transfers?utm_source=chatgpt.com
https://www.govinfo.gov/content/pkg/FR-2010-06-15/pdf/2010-14353.pdf?utm_source=chatgpt.com
R010-P1-S011 Saved research record

CFPB, Electronic Fund Transfers—2011 recodification. https://www.govinfo.gov/content/pkg/FR-2011-12-27/pdf/2011-31725.pdf

Recorded check status: fresh selected historical partial group

Exact provisions; printed page / PDF index
76 FR 81020–81058, 39 pages. Necessary read at 81020–81021 / indices 0–1: transfer, recodification, effective date, A-9 change.
Version, effective predicate, status
Interim final rule; effective 2011-12-30. Rulemaking transfer described as effective 2011-07-21. No new substantive obligations asserted by this recodification.
Fresh-read extent and currentness limits
Fresh, selected body read. A-9 continuity passage fully read. The embedded A-9 graphic was not visually inspected; its exact graphic-page location is not asserted. Not merely a proposal. govinfo.gov
Direct source URLs
https://www.govinfo.gov/content/pkg/FR-2011-12-27/pdf/2011-31725.pdf
https://www.govinfo.gov/content/pkg/FR-2011-12-27/pdf/2011-31725.pdf?utm_source=chatgpt.com
R010-P1-S012 Saved research record

CFPB, Overdraft Lending: Very Large Financial Institutions. https://www.federalregister.gov/documents/2024/12/30/2024-29699/overdraft-lending-very-large-financial-institutions ; https://www.govinfo.gov/content/pkg/FR-2024-12-30/pdf/2024-29699.pdf

Recorded check status: fresh selected historical partial group

Exact provisions; printed page / PDF index
89 FR 106768–106845, 78 pages. Dates 106768 / 0; § IV discussion and § V timing 106816 / 48; complete added comment 17(a)-2 at 106837 / 69.
Version, effective predicate, status
Published 2024-12-30, stated effective 2025-10-01; disapproved before that date by S013.
Fresh-read extent and currentness limits
Fresh, selected provisions read, not all 78 pages. Used only to identify the exact disapproved change and original trigger. No proposed or disapproved framework is used as current authority. govinfo.gov +2
Direct source URLs
https://www.federalregister.gov/documents/2024/12/30/2024-29699/overdraft-lending-very-large-financial-institutions
https://www.govinfo.gov/content/pkg/FR-2024-12-30/pdf/2024-29699.pdf
https://www.federalregister.gov/documents/2024/12/30/2024-29699/overdraft-lending-very-large-financial-institutions?utm_source=chatgpt.com
https://www.govinfo.gov/content/pkg/FR-2024-12-30/pdf/2024-29699.pdf?utm_source=chatgpt.com
R010-P1-S013 Saved research record

Congress, Public Law 119-10, S.J. Res. 18. https://www.govinfo.gov/content/pkg/PLAW-119publ10/pdf/PLAW-119publ10.pdf

Recorded check status: fresh selected body

Exact provisions; printed page / PDF index
139 Stat. 53 / PDF index 0, entire one-page law.
Version, effective predicate, status
Approved 2025-05-09. Disapproves the specifically named 89 FR 106768 final rule and gives it no force or effect.
Fresh-read extent and currentness limits
Fresh, complete parsed law read. Screenshot yielded no inspectable pixels; the text body was fully available. No docket or litigation-status inference. govinfo.gov
Direct source URLs
https://www.govinfo.gov/content/pkg/PLAW-119publ10/pdf/PLAW-119publ10.pdf
https://www.govinfo.gov/content/pkg/PLAW-119publ10/pdf/PLAW-119publ10.pdf?utm_source=chatgpt.com
R010-P1-S014 Saved research record

CFPB, Overdraft Lending compliance resource/status page. https://www.consumerfinance.gov/compliance/compliance-resources/deposit-accounts-resources/overdraft-lending-very-large-financial-institutions/

Recorded check status: fresh selected status body

Exact provisions; printed page / PDF index
“Featured topic” paragraph; HTML, page/index N/A.
Version, effective predicate, status
Page modified 2025-07-01. Says the final rule has no force/effect and remaining Reg E/Z remain unchanged.
Fresh-read extent and currentness limits
Fresh status paragraph read. Its statement that signing occurred May 12 conflicts with S013’s May 9 approval date. Public-law date controls this report. Resource label does not replace operative text. Consumer Financial Protection Bureau
Direct source URLs
https://www.consumerfinance.gov/compliance/compliance-resources/deposit-accounts-resources/overdraft-lending-very-large-financial-institutions/
https://www.consumerfinance.gov/compliance/compliance-resources/deposit-accounts-resources/overdraft-lending-very-large-financial-institutions/?utm_source=chatgpt.com
R010-P1-S015 Saved research record

CFPB, Withdrawn Guidance register and withdrawal notice. https://www.consumerfinance.gov/compliance/guidance/withdrawn-guidance/ ; https://www.federalregister.gov/documents/2025/05/12/2025-08286/interpretive-rules-policy-statements-and-advisory-opinions-withdrawal ; https://www.govinfo.gov/content/pkg/FR-2025-05-12/pdf/2025-08286.pdf

Recorded check status: fresh selected status body

Exact provisions; printed page / PDF index
Register’s Circulars & Supervisory Guidance entries for 2024-05 and 2022-06; notice parts I–III and relevant entries. 90 FR 20084–20087, indices 0–3; applicability at 20084 / 0, operative withdrawal discussion 20085 / 1, relevant list 20086 / 2.
Version, effective predicate, status
Withdrawals applicable 2025-05-12. Register last-modified label 2026-07-22.
Fresh-read extent and currentness limits
Fresh register and necessary notice bodies read. Register and notice are one publisher’s status chain, not independent corroboration. Withdrawal is not treated as statutory repeal or a universal fee validation. Consumer Financial Protection Bureau +3
Direct source URLs
https://www.consumerfinance.gov/compliance/guidance/withdrawn-guidance/
https://www.federalregister.gov/documents/2025/05/12/2025-08286/interpretive-rules-policy-statements-and-advisory-opinions-withdrawal
https://www.govinfo.gov/content/pkg/FR-2025-05-12/pdf/2025-08286.pdf
https://www.consumerfinance.gov/compliance/guidance/withdrawn-guidance/?utm_source=chatgpt.com
https://www.federalregister.gov/documents/2025/05/12/2025-08286/interpretive-rules-policy-statements-and-advisory-opinions-withdrawal?utm_source=chatgpt.com
https://www.govinfo.gov/content/pkg/FR-2025-05-12/pdf/2025-08286.pdf?utm_source=chatgpt.com
R010-P1-S016 Saved research record

CFPB, historical circular publisher pages. https://www.consumerfinance.gov/compliance/circulars/consumer-financial-protection-circular-2022-06-unanticipated-overdraft-fee-assessment-practices/ ; https://www.consumerfinance.gov/compliance/circulars/consumer-financial-protection-circular-2024-05/

Recorded check status: unreopened historical publisher pages

Exact provisions; printed page / PDF index
Titles, questions/answers and relevant scope passages; HTML, page/index N/A. Register cites 87 FR 66935, Nov. 7, 2022, and 89 FR 80075, Oct. 2, 2024.
Version, effective predicate, status
Withdrawn, as verified against S015.
Fresh-read extent and currentness limits
Fresh, limited publisher-page read and status check. Not a full read of every cited authority. No historical enforcement/evidence theory is adopted as current operative law. Continued page availability is not currentness. Consumer Financial Protection Bureau +4
Direct source URLs
https://www.consumerfinance.gov/compliance/circulars/consumer-financial-protection-circular-2022-06-unanticipated-overdraft-fee-assessment-practices/
https://www.consumerfinance.gov/compliance/circulars/consumer-financial-protection-circular-2024-05/
https://www.consumerfinance.gov/compliance/circulars/consumer-financial-protection-circular-2022-06-unanticipated-overdraft-fee-assessment-practices/?utm_source=chatgpt.com
https://www.consumerfinance.gov/compliance/circulars/consumer-financial-protection-circular-2024-05/?utm_source=chatgpt.com
R010-P1-S017 Saved research record

Congress; GPO, 12 USC 5519—Exclusion for auto dealers. https://www.govinfo.gov/content/pkg/USCODE-2024-title12/html/USCODE-2024-title12-chap53-subchapV-partB-sec5519.htm

Recorded check status: fresh selected historical body

Exact provisions; printed page / PDF index
Entire operative (a)–(f), particularly jurisdictional exclusion, exceptions, preserved authorities, and definitions. HTML, page/index N/A.
Version, effective predicate, status
Official 2024 Edition recovery. Cross-reference in §§ 1005.2(i), 1005.3(a), and 1693b(a)(2).
Fresh-read extent and currentness limits
Fresh body read. Current OLRC retrieval failed. No dealer, license, entity, or business-line classification was attempted. Statutory lag remains held. BANKS AND BANKING
Direct source URLs
https://www.govinfo.gov/content/pkg/USCODE-2024-title12/html/USCODE-2024-title12-chap53-subchapV-partB-sec5519.htm
https://www.govinfo.gov/content/pkg/USCODE-2024-title12/html/USCODE-2024-title12-chap53-subchapV-partB-sec5519.htm?utm_source=chatgpt.com
R010-P1-S018 Saved research record

GPO, full Part 1005 recovery attempts. https://www.govinfo.gov/content/pkg/CFR-2025-title12-vol8/pdf/CFR-2025-title12-vol8-part1005.pdf ; https://www.govinfo.gov/content/pkg/CFR-2026-title12-vol8/pdf/CFR-2026-title12-vol8-part1005.pdf ; https://www.govinfo.gov/link/cfr/12/1005?link-type=pdf&year=mostrecent

Recorded check status: unreopened recovery attempt history

Exact provisions; printed page / PDF index
2025 A-9 location: printed 245 / index 60, heading but missing form-body extraction. 2026 full-part header/initial text retrieved; subsequent targeted retrievals timed out.
Version, effective predicate, status
Annual editions, not October 2026 complete currency guarantees.
Fresh-read extent and currentness limits
Fresh, partial/discovery/failure. No whole-part read claimed. Used to attempt form/text recovery, not independent authority beyond S003–S005.
Direct source URLs
https://www.govinfo.gov/content/pkg/CFR-2025-title12-vol8/pdf/CFR-2025-title12-vol8-part1005.pdf
https://www.govinfo.gov/content/pkg/CFR-2026-title12-vol8/pdf/CFR-2026-title12-vol8-part1005.pdf
https://www.govinfo.gov/link/cfr/12/1005?link-type=pdf&year=mostrecent
https://www.govinfo.gov/content/pkg/CFR-2025-title12-vol8/pdf/CFR-2025-title12-vol8-part1005.pdf?utm_source=chatgpt.com
https://www.govinfo.gov/content/pkg/CFR-2026-title12-vol8/pdf/CFR-2026-title12-vol8-part1005.pdf?utm_source=chatgpt.com
https://www.govinfo.gov/link/cfr/12/1005?link-type=pdf&year=mostrecent&utm_source=chatgpt.com

What was examined—and what is still missing

The saved component-level coverage record keeps answered, partial, blank and unresolved branches distinct. A coverage label is not acceptance of a whole subject or jurisdiction.

coverage-1 Saved research record

1.a Enabling EFTA authority

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Partial: substantive text read; currentness gap
Claim / example links
C001; S001, S003, S011
Exact missing authority or facts
Current OLRC §§ 1693a–b bodies and complete later session-law lag audit.
Next bounded permissible investigation
Recover current official statutory text and check only relevant published amendments.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-2 Saved research record

1.b Consumer versus business account

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C002–C003
Exact missing authority or facts
Actual primary purpose and account arrangement.
Next bounded permissible investigation
No actual-record inquiry authorized; maintain fact hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-3 Saved research record

1.c Bank/credit-union/other FI coverage

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C004–C005, C053, C059
Exact missing authority or facts
Actual account-holder/issuer roles and any statutory excluded-person predicates.
Next bounded permissible investigation
Published definition clarification only; no institution/license search.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-4 Saved research record

1.d EFT-service agreement gateway

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C006–C009
Exact missing authority or facts
Actual agreement, notice of third-party arrangement, transfer initiation.
Next bounded permissible investigation
Maintain fact hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-5 Saved research record

1.e Necessary EFT exclusions

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered within relevant clauses
Claim / example links
C008, C010–C014
Exact missing authority or facts
Actual rail, purpose, within-institution relationship, qualifying assets/plan.
Next bounded permissible investigation
Narrow public authority follow-up only if a specific legal ambiguity becomes material.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-6 Saved research record

1.f Geographic scope

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered at federal gateway; broader scope held
Claim / example links
C015
Exact missing authority or facts
Actual account location/residence; non-U.S. law.
Next bounded permissible investigation
No country-wide or international closure; separate bounded law review only.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-7 Saved research record

1.g Covered paid overdraft definition

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C018
Exact missing authority or facts
Paid status, insufficient/unavailable funds, fee cause, account-holding actor.
Next bounded permissible investigation
Maintain fact hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-8 Saved research record

1.h Linked credit/own-account transfer/securities exclusions

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C019–C021; E07
Exact missing authority or facts
Actual mechanism and agreement.
Next bounded permissible investigation
No credit-product or provider search.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-9 Saved research record

1.i Prepaid exclusion

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered as conditional gate; product taxonomy partial
Claim / example links
C017, C022–C024; E14
Exact missing authority or facts
Product facts; remote incorporated benefits/gift/tax definitions; historical prepaid-date chain.
Next bounded permissible investigation
Follow only a material published cross-reference; no full prepaid/credit closure.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-10 Saved research record

1.j Actual coding/classification

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Unresolved facts
Claim / example links
C016, C059–C061; E03
Exact missing authority or facts
Actual coding, adapted systems, reliance, recurring authorization.
Next bounded permissible investigation
No actual transaction search authorized.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-11 Saved research record

2.a Complete § 17 notice/consent/confirmation/revocation text

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered; full section/comments read
Claim / example links
C029–C047, C071–C080; S004
Exact missing authority or facts
Actual compliance facts only.
Next bounded permissible investigation
No additional generic authority needed for the stated text.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-12 Saved research record

2.b Segregated notice and separate choice

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C030, C034–C036, C050; E12
Exact missing authority or facts
Actual presentation, dedicated choice, preselection.
Next bounded permissible investigation
Maintain fact hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-13 Saved research record

2.c Reasonable opportunity and methods

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C033, C036, C044
Exact missing authority or facts
Actual opportunity and available methods.
Next bounded permissible investigation
Maintain fact hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-14 Saved research record

2.d Electronic delivery and retainability

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered with authority-type distinction
Claim / example links
C030–C032, C037
Exact missing authority or facts
Actual delivery agreement/retention; independent requirements for other documents.
Next bounded permissible investigation
Any further E-Sign work must identify the distinct legally required disclosure.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-15 Saved research record

2.e Confirmation timing

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C037–C039; E02
Exact missing authority or facts
Mailing/delivery, consent receipt, transaction payment, reasonable procedures.
Next bounded permissible investigation
Maintain fact hold; no invented receipt deadline.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-16 Saved research record

2.f Complete required notice content

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C040–C047
Exact missing authority or facts
Actual fees, service policies, alternatives, tailored text.
Next bounded permissible investigation
Compare only a permissible generic blank form if later needed.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-17 Saved research record

2.g Current A-9 body/image

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Partial source retrieval
Claim / example links
C049; S005–S006, S011
Exact missing authority or facts
Current image pixels and complete current image transcription not obtained.
Next bounded permissible investigation
Obtain readable official current form through permitted public tools; no access workaround.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-18 Saved research record

2.h Historical A-9 and current instructions

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered within read bounds
Claim / example links
C040–C049
Exact missing authority or facts
Historical-to-current visual comparison remains unverified.
Next bounded permissible investigation
Preserve distinction between historical parsed text and current image.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-19 Saved research record

2.i Revocation, joint holders, duration

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C071–C075; E06, E13
Exact missing authority or facts
Actual joint status and event chronology.
Next bounded permissible investigation
Maintain fact hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-20 Saved research record

2.j Effective dates and existing accounts

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered for § 17 transition/recodification
Claim / example links
C076–C080
Exact missing authority or facts
Actual opening and payment dates.
Next bounded permissible investigation
No individual calendar calculation.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-21 Saved research record

3.a Complete fee prerequisite

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C029, C057–C063
Exact missing authority or facts
Actual satisfaction of coverage and four conditions.
Next bounded permissible investigation
Maintain fact hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-22 Saved research record

3.b No conditioning of other overdrafts

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C054
Exact missing authority or facts
Actual payment criteria and reason for decline.
Next bounded permissible investigation
No institutional practice investigation.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-23 Saved research record

3.c Same terms/features

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C055–C056
Exact missing authority or facts
Actual comparative terms and independent eligibility.
Next bounded permissible investigation
No creditworthiness or account-eligibility decision.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-24 Saved research record

3.d Payment discretion versus fee authority

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C057–C058; E01
Exact missing authority or facts
Applicable principal-debit law and contract remain unknown.
Next bounded permissible investigation
Preserve setoff/collection/contract holds.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-25 Saved research record

3.e Checks/ACH/recurring versus one-time card

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically; classification facts unresolved
Claim / example links
C008–C016, C059–C061; E03–E04
Exact missing authority or facts
Actual channel and recurring predicates.
Next bounded permissible investigation
Maintain fact hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-26 Saved research record

3.f Balance-amount fees

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C064–C065; E05, E08
Exact missing authority or facts
Actual balance components and fee basis.
Next bounded permissible investigation
No ledger reconstruction authorized.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-27 Saved research record

3.g Daily/sustained/negative-balance fees

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C066–C070
Exact missing authority or facts
Actual continuing attribution, contractual period, deposits and allocations.
Next bounded permissible investigation
Maintain fact hold; no universal period inferred.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-28 Saved research record

3.h Mixed-balance timing

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered generically
Claim / example links
C068–C070; E08
Exact missing authority or facts
Nonprotected payment date, period units, residual source.
Next bounded permissible investigation
Only generic further interpretation; no individual deadline.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-29 Saved research record

3.i Opt-in and other limits

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered as limitation
Claim / example links
C081, C088
Exact missing authority or facts
Broader governing law/contract and any settlement context.
Next bounded permissible investigation
Preserve parent holds.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-30 Saved research record

4.a Authorization-positive/settlement-negative without opt-in

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered by current comment
Claim / example links
C062–C063; E09
Exact missing authority or facts
Actual predicates, if any.
Next bounded permissible investigation
No withdrawn guidance needed.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-31 Saved research record

4.b Authorization-positive/settlement-negative with compliant opt-in

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Unresolved broader legal basis
Claim / example links
C088; E10
Exact missing authority or facts
Independently applicable law, balance/disclosure/contract facts.
Next bounded permissible investigation
If later necessary, inspect only material published primary authority; no docket query.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-32 Saved research record

4.c Withdrawn-guidance checks

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered for every circular used for status
Claim / example links
C086–C087; S015–S016
Exact missing authority or facts
No broader guidance-universe audit asserted.
Next bounded permissible investigation
Recheck official register only if another guidance item becomes necessary.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-33 Saved research record

4.d 2024/2025 final-rule disapproval

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered for authority actually implicated
Claim / example links
C082–C085; S012–S014
Exact missing authority or facts
Full unrelated provisions of disapproved rule not examined.
Next bounded permissible investigation
No need to revive its framework; retain exact statutory effect.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-34 Saved research record

4.e Paid versus returned/unpaid, NSF

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Answered as distinction; broader law excluded
Claim / example links
C026–C027; E11
Exact missing authority or facts
Actual disposition, actor and collection method; substantive NSF law.
Next bounded permissible investigation
Separate generic NSF component if later assigned.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-35 Saved research record

4.f Deposit advance, linked credit, setoff

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Partial by intentional scope
Claim / example links
C019–C025; E07
Exact missing authority or facts
Credit/security/setoff contracts and broader legal authority.
Next bounded permissible investigation
Preserve separate lending/setoff dimensions.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-36 Saved research record

4.g Published opinions/later litigation status

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Excluded from conclusions; no case holding needed here
Claim / example links
C088–C090
Exact missing authority or facts
No majority-opinion holding or later-history audit performed.
Next bounded permissible investigation
Only material published opinions if later strictly necessary; no case-record/docket-status query.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-37 Saved research record

5.a Blank audit worksheet

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Delivered
Claim / example links
W01–W27
Exact missing authority or facts
All entries intentionally blank.
Next bounded permissible investigation
No records request or identifier entry.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-38 Saved research record

5.b No-opt-in paid one-time branch

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Delivered
Claim / example links
E01; C029, C057
Exact missing authority or facts
Actual facts not supplied.
Next bounded permissible investigation
None within this published-source pass.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-39 Saved research record

5.c Affirmative consent, other conditions unknown

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Delivered
Claim / example links
E02; C029–C039
Exact missing authority or facts
Notice/opportunity/confirmation/timing facts.
Next bounded permissible investigation
Maintain hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-40 Saved research record

5.d Recurring classification branch

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Delivered
Claim / example links
E03; C016, C061
Exact missing authority or facts
Classification/coding/system facts.
Next bounded permissible investigation
Maintain hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-41 Saved research record

5.e Check or ACH branch

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Delivered
Claim / example links
E04; C008–C009, C054
Exact missing authority or facts
Channel and contract facts.
Next bounded permissible investigation
Maintain hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-42 Saved research record

5.f No consent, other negative source

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Delivered
Claim / example links
E05; C064–C068
Exact missing authority or facts
Causation and fee trigger.
Next bounded permissible investigation
Maintain hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-43 Saved research record

5.g Revoked-consent branch

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Delivered
Claim / example links
E06; C072–C075
Exact missing authority or facts
Receipt/implementation/payment chronology.
Next bounded permissible investigation
Maintain hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-44 Saved research record

5.h Linked-credit exclusion branch

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Delivered
Claim / example links
E07; C019
Exact missing authority or facts
Actual Reg Z credit arrangement.
Next bounded permissible investigation
Preserve credit-law holds.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-45 Saved research record

5.i Mixed-transactions branch

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Delivered
Claim / example links
E08; C064–C070
Exact missing authority or facts
Complete component allocation and timing.
Next bounded permissible investigation
Maintain hold.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-46 Saved research record

5.j Authorization/settlement branch

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Delivered in two distinct forms
Claim / example links
E09–E10; C063, C088
Exact missing authority or facts
With-opt-in broader legal basis remains unresolved.
Next bounded permissible investigation
No universal APSN conclusion.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-47 Saved research record

Standards: current statutory/body/edition completeness

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Partial
Claim / example links
C090; failure log
Exact missing authority or facts
Current bodies for identified statutes; complete intervening-publication audit.
Next bounded permissible investigation
Public primary-source recovery only.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-48 Saved research record

Standards: UI/model provenance

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Unverified beyond session identity
Claim / example links
Opening provenance statement
Exact missing authority or facts
Frontend and selector evidence unavailable.
Next bounded permissible investigation
No claim of unseen UI verification.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds
coverage-49 Saved research record

Parent/operational/publication acceptance

Recorded check status: recorded; no individual primary acceptance inferred

Coverage
Excluded
Claim / example links
Parent holds below
Exact missing authority or facts
No authority or factual basis for acceptance/closure requested.
Next bounded permissible investigation
Preserve all holds; no operational action.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_with_explicit_source_form_actualfact_and_parent_holds

Corrections, review and scope

Read the evidence with its boundaries. These are saved research components, including revisions. A scoped coordinator review checks selected evidence; it does not certify every claim, a complete jurisdiction, current law or individual applicability. Dates and access limits remain attached to the records.

How to read the research →

No currently queued material correction is mapped to this component. This does not remove its currentness, access, jurisdiction or application limits.

Recorded review disposition

accepted with limits

Other components in this research series

Record integrity

Original saved Markdown SHA-256: 104f35aa30d1780d527b933e66920e2f1c6155f509fe453ef744fdb5b5e91d9e. Public formatting, private-reference removal and correction annotations are separate from that immutable original.

Get debt settlement help