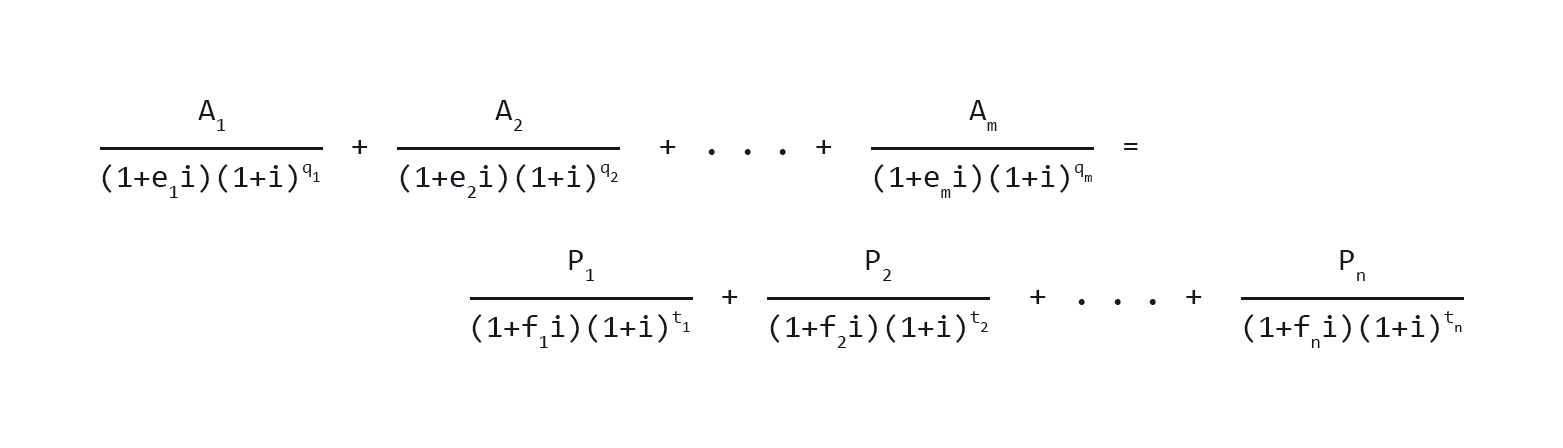SettleADebt.

FIND THE EXPLANATION

Where your loan payment goes: interest, fees, and principal

Follow a payment through interest, fees, and principal to understand why the balance changes.

Read the complete guide →

This address preserves a dated source document behind the guide. The complete explanation covers the questions, comparisons and next steps for this subject.

If you came here to check a specific citation, open the original archive below. It includes its source dates and recorded qualifications.

Original source archive (optional)Original working documents, complete tables and revision history
About this archive

The explanation above is written for readers. These original working documents preserve the evidence trail, including technical language, dated passages and known corrections. They have not all received independent professional review. Use the marked limits before relying on a particular rule or figure.

DETAILED RESEARCH · EVIDENCE & LIMITS INCLUDED

US consumer closed-end simple interest, amortization, and APR comparison

R004 · pass-01Captured 2026-10-2722 tables · 56 claim records · 14 source recordsScoped coordinator review completed

Read the evidence with its boundaries. These are saved research components, including revisions. A scoped coordinator review checks selected evidence; it does not certify every claim, a complete jurisdiction, current law or individual applicability. Dates and access limits remain attached to the records.

How to read the research →

SettleADebt R004 PASS-01 — A004

US consumer closed-end simple interest, amortization, and APR comparison

Disposition: The bounded investigation and six worked examples are complete. The legal APR calculation remains on hold because several operative Appendix J equations and example panels were unavailable as readable content. E05 therefore supplies a separately labeled numerical cash-flow calculation, not a compliant or legally determined APR.

Actual check date: October 27, 2026, America/Los_Angeles. Observed research-session clock readings ran from 12:39 PDT to 12:57 PDT on that date, corresponding to 19:39–19:57 UTC. Publication and compilation dates are separately recorded below.

This report treats the R004/A004 assignment as supplied. No prior R004 report, other chat, or dependent foundation was used. No external registry status was checked. No borrower, account, provider-status, property, license, or case-record investigation was performed. No files, subagents, contacts, applications, or publication actions were used. I do not claim independently verified UI model provenance or a separate independent review.

Principal findings

  • Under the expressly defined monthly model, a hypothetical $10,000 loan at a 12% nominal annual rate over 12 months produces $661.86 of interest with cent posting and an adjusted final payment.
  • Under the same original principal, rate, payment convention, and allocation assumptions, an additional $2,000 principal payment immediately after installment 3 reduces modeled interest to $491.29, saving $170.57 and producing a final partial payment in model month 10.
  • Thirty days of hypothetical simple accrual on $10,000 at 12% produces $98.63 on a 365 denominator and $100.00 on a 360 denominator, when interest is rounded once at the end. That comparison establishes arithmetic, not which denominator a creditor may use.
  • A hypothetical $300 upfront charge can leave the note balance at $10,000 while reducing amount financed to $9,700, if it is legally a prepaid finance charge. The corresponding numerical annualized cash-flow rate is approximately 17.8250%. This report does not label that result a legal APR.

All rates, fees, balances, and payment paths below are hypothetical parameters, not offers or actual borrower facts.

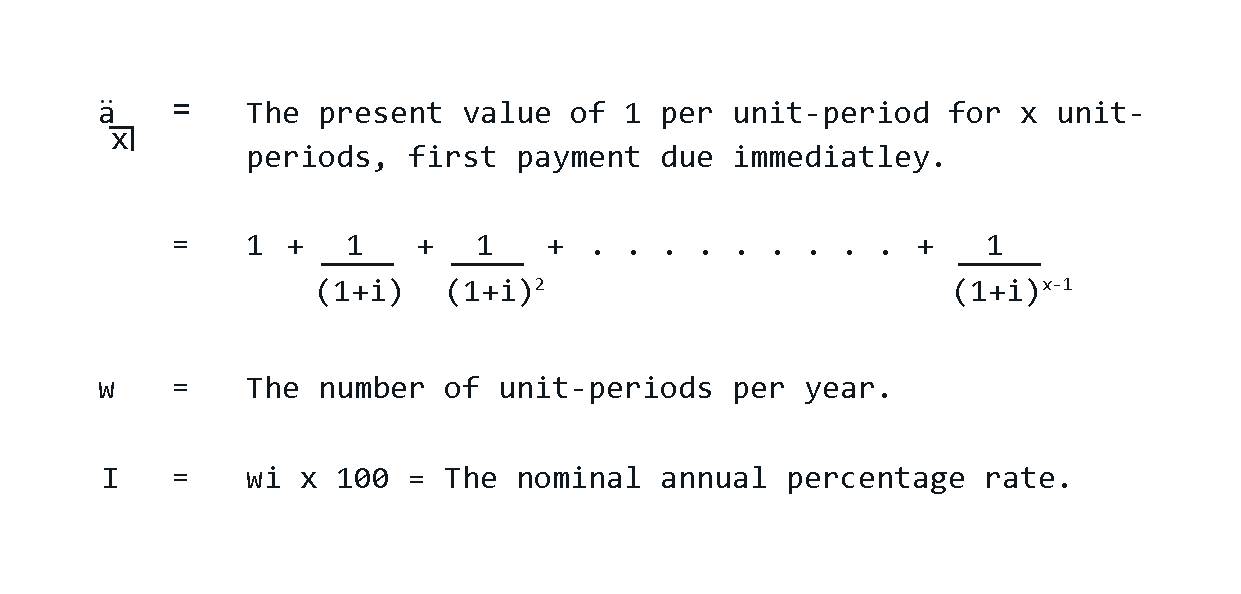
Reference convention: S001 means R004-P1-S001; C001 means R004-P1-C001. Every claim in the claim register belongs to A004.

1. The quantities that must remain distinct

Quantity Meaning in this investigation Important boundary
Principal balance The model’s outstanding interest-bearing principal, denoted B. It is not automatically the cash the consumer received or the Regulation Z amount financed. Whether financed charges or capitalized interest belong in an actual interest-bearing balance requires applicable terms and law. C006, C020–C021.
Interest rate / note rate The rate used under the stipulated accrual convention. For E02, 12% nominal annually is expressly defined as 1% per model month. A stated annual rate does not establish its denominator, compounding convention, fee treatment, or legally disclosed APR. C007, C038.
Finance charge The legally classified dollar cost of consumer credit under TILA and Regulation Z. It can include interest and certain fees, but not every charge or every upfront payment. Classification requires the applicable inclusion and exclusion provisions. C008–C018.
Amount financed A disclosure measure of credit provided to the consumer or on the consumer’s behalf, calculated under §1026.18(b). It can differ from the note’s face amount, principal balance, gross disbursement, and net cash received. C019–C021.
Payment A cash payment at a specified time. A disclosed payment schedule states the number, amounts, and timing of scheduled payments. Its allocation among interest, principal, fees, and other items is not established merely by knowing the payment amount. C022.
Total of payments Under the relevant Regulation Z commentary, the sum of the payments disclosed in the repayment schedule. It is not invariably every dollar paid at origination and afterward. A prepaid finance charge is not separately listed as a repayment-schedule payment. C022–C023.
Total interest The sum of interest accrued in a defined model and period. It differs from finance charge when other included charges exist; accrued interest also differs from interest actually paid when arrears remain. C024, E06.
Legal APR The annual percentage rate determined under the applicable TILA/Regulation Z method, amounts, timing rules, and accuracy provisions. It is not generally interchangeable with the note rate, an effective annual rate, or any software-produced IRR. C025–C030.
Effective annual yield/rate Here, a mathematical annual equivalent: y = (1 + r)^m - 1 for m identical compounding periods per year. This is a mathematical convention, not a claim that this is the required closed-end APR disclosure or that unpaid loan interest may legally compound. C031.
Numerical IRR estimate A numerical rate equating specified advances or net proceeds with discounted specified payments. Its legal significance depends on correct inputs and the legally applicable calculation convention. Numerical convergence alone does not establish compliance. C032.

The disclosure distinctions come from TILA §§1605, 1606, and 1638, Regulation Z §§1026.2, .4, .18, and .22, and their relevant official interpretations. uscode.house.gov+4

Fee classification comes before a legal APR calculation

A charge’s label, recipient, or timing is insufficient by itself. For example, the rule treats a qualifying application fee charged to all applicants differently from a loan fee charged only when credit is extended. Third-party charges require their own analysis, and specified insurance and security-related charges have conditional exclusions. “Mandatory” does not mean universally included, and “optional” does not mean universally excluded. The precise conditions are recorded in C009–C018. ecfr.gov+1

Disclosure rules also do not, by themselves, authorize a rate, fee, capitalization event, payment-allocation practice, or prepayment penalty. The legal obligation and applicable law remain controlling inputs. Consumer Financial Protection Bureau+1

2. Two separate interest models

2.1 Daily simple-interest model

For a period in which the interest-bearing balance and annual rate remain unchanged:

Plain text

interest = balance * annual_rate_decimal * accrual_days / day_count_denominator

Units are:

Plain text

dollars * annual decimal rate * days / days-per-rate-year = dollars

If balances, rates, or applicable denominators change, the stipulated simple-accrual model is segmented:

Plain text

total_interest = sum(balance_j * annual_rate_j * days_j / denominator_j)

This formula does not decide:

  • Which event establishes the credited payment date: receipt, posting, value date, or another legally applicable event.
  • Which endpoint is included.
  • Whether a partial payment is immediately applied.
  • Whether accrued interest is carried separately or validly capitalized.
  • How a year boundary is handled.
  • Whether interest is rounded daily, at payment, or only when posted.
  • Whether an extra payment advances a due date or changes the required installment.

Those are unresolved contractual and legal inputs, not missing algebra.

The official commentary expressly distinguishes using a 360-day calculation tool from actually applying an annual rate divided by 360 across 365 accrual days. Its disclosure simplifications do not make those practices economically identical. A public generic creditor instruction also states a 365/366 convention, but only for the convention described in that document. Consumer Financial Protection Bureau+1

2.2 Fixed-payment monthly model

For E02 and E04, the model expressly uses equal monthly periods and a monthly rate.

Let:

Plain text

P = original principal in dollars
r = interest rate per model month, as a decimal
n = number of end-of-month installments
M = equal theoretical installment
B_k = principal immediately after installment k

With no fees, arrears, or capitalization complications:

Plain text

B_0 = P
I_k = r * B_(k-1)
principal_paid_k = M - I_k
B_k = B_(k-1) * (1 + r) - M

Repeated substitution gives, for r > 0:

Plain text

B_n = P * (1 + r)^n - M * [((1 + r)^n - 1) / r]

Setting the final balance to zero and solving for M:

Plain text

M = P * r / [1 - (1 + r)^(-n)]

This is a derivation from the stated recurrence, not a statutory formula for permissible interest.

For r = 0, use a separate equation:

Plain text

M = P / n
B_k = P - cumulative_principal_payments_through_k

Do not evaluate the positive-rate expression by dividing by zero.

When annual rate divided by 12 is appropriate

For this investigation:

Plain text

r = nominal_annual_rate / 12

is appropriate because the monthly model expressly defines the nominal annual rate that way.

It is not a general conversion for:

  • An effective annual rate: the corresponding mathematical monthly rate would be (1 + y)^(1/12) - 1.
  • A fee-inclusive legal APR used as though it were the note’s accrual rate.
  • Daily simple interest merely because payments occur monthly.
  • Irregular periods, variable rates, or a contract using another accrual convention.

For a 1% monthly rate:

Plain text

nominal annual rate = 12 * 1% = 12%
effective annual rate = 100 * [(1.01)^12 - 1]
                      = 12.6825030132%

That effective annual equivalent does not mean the E02 loan capitalizes unpaid interest monthly. E02 pays each month’s interest in full.

3. Worked-example register

Example Hypothetical question Principal result Status
E01 Same principal/rate, 30 days, alternative denominators $98.63 on 365; $100.00 on 360; $1.37 rounded difference Arithmetic answered; actual denominator and rounding authority held
E02 Positive-rate fixed monthly amortization $888.49 ordinary installment; $888.47 final; $661.86 interest Complete stated cent-posting schedule
E03 Same principal and term, zero interest Eleven payments of $833.33 and one of $833.37 Complete zero-rate handling
E04 E02 plus $2,000 principal after installment 3 Final $494.88 at month 10; $491.29 interest; $170.57 saved Controlled comparison; real allocation/prepayment rights held
E05 $300 upfront fee and cash-flow rate comparison Conditional amount financed $9,700; numerical annualized rate about 17.8250% Legal APR held; numerical estimate and classification branches supplied
E06 Payment below accruing interest After three $5 payments: $1,015.00 without capitalization; $1,015.15 with stipulated capitalization Separate mathematical branches; capitalization permission held

E01 — Thirty days of simple accrual

Hypothetical inputs

Plain text

principal = $10,000
annual rate = 12% = 0.12
elapsed accrual units = exactly 30 days
principal unchanged throughout

The example stipulates 30 nonoverlapping accrual-day units. It does not assign real calendar dates, holidays, or a receipt/posting rule.

Assumed denominator Calculation before rounding Interest rounded once at the end
365 10000 * 0.12 * 30 / 365 = 98.6301369863 $98.63
360 10000 * 0.12 * 30 / 360 = 100.0000000000 $100.00
366, only as a separately stipulated leap-year branch 10000 * 0.12 * 30 / 366 = 98.3606557377 $98.36

The required 365-versus-360 comparison is:

Plain text

unrounded difference = 100 - 98.6301369863
                     = $1.3698630137

difference between rounded end-of-period amounts = $1.37
Rounding changes the result
Denominator Round only the final period charge Round each daily amount to cents, then sum 30 days Difference
365 $98.63 $3.29 * 30 = $98.70 Daily cent posting is $0.07 higher
360 $100.00 $3.33 * 30 = $99.90 Daily cent posting is $0.10 lower

These are two different posting assumptions. Displaying a rounded per diem does not establish that a ledger rounds each day.

Authority boundary: Current official commentary discusses 360/365 differences. The generic creditor instruction in S013 explicitly states 365, or 366 in a leap year, but is dated December 17, 2010. It is not proof of a current universal practice or an agreed contract. A denominator of 360 also does not, by itself, establish a complete “30/360” date-counting convention. No complete Actual/Actual convention across year boundaries is established here. C033–C037, C045. Consumer Financial Protection Bureau+2

E02 — Fixed monthly amortization at a positive rate

Hypothetical inputs

Plain text

P = $10,000
nominal annual note rate = 12%
r = 0.12 / 12 = 0.01 per model month
n = 12 end-of-month installments
advance at t = 0
first installment at t = 1 month
original final installment at t = 12 months

Additional assumptions:

  • No fees, changing rates, existing unpaid interest, or prepayment charges.
  • Every scheduled payment is timely.
  • Current interest is paid first; the remainder reduces principal.
  • Interest is posted monthly to cents using nearest-cent, half-up rounding for these positive amounts.
  • The ordinary payment is rounded to $888.49.
  • The final payment is adjusted to the exact remaining cent balance plus that month’s posted interest.

These are model assumptions, not a finding about any real payment-allocation clause.

Step 1: Calculate the theoretical payment

Plain text

M = 10000 * 0.01 / [1 - (1.01)^(-12)]
  = $888.487886783416...

In an ideal calculation with fractional-cent payments and no intermediate rounding:

Plain text

12 * M = $10,661.854641400994...
total interest = $661.854641400994...

The analytic final balance is zero. Floating-point evaluation produced a residual of approximately 0.0000000000108 dollars, which is numerical evaluation noise, not a collectible residual.

The following schedule uses the separately identified cent-posting model, not fractional-cent cash payments.

Step 2: Calculate the first two installments

Plain text

Month 1 interest = round_cent(10000.00 * 0.01) = $100.00
Month 1 principal = 888.49 - 100.00 = $788.49
Month 1 ending balance = 10000.00 - 788.49 = $9,211.51

Month 2 unrounded interest = 9211.51 * 0.01 = $92.1151
Month 2 posted interest = $92.12
Month 2 principal = 888.49 - 92.12 = $796.37
Month 2 ending balance = 9211.51 - 796.37 = $8,415.14
Complete cent-posting schedule
Month Opening principal Posted interest Cash payment Principal paid Ending principal
1 $10,000.00 $100.00 $888.49 $788.49 $9,211.51
2 9,211.51 92.12 888.49 796.37 8,415.14
3 8,415.14 84.15 888.49 804.34 7,610.80
4 7,610.80 76.11 888.49 812.38 6,798.42
5 6,798.42 67.98 888.49 820.51 5,977.91
6 5,977.91 59.78 888.49 828.71 5,149.20
7 5,149.20 51.49 888.49 837.00 4,312.20
8 4,312.20 43.12 888.49 845.37 3,466.83
9 3,466.83 34.67 888.49 853.82 2,613.01
10 2,613.01 26.13 888.49 862.36 1,750.65
11 1,750.65 17.51 888.49 870.98 879.67
12 879.67 8.80 888.47 879.67 0.00
Total — $661.86 $10,661.86 $10,000.00 $0.00
Conservation and final-payment check

Plain text

11 * 888.49 + 888.47 = $10,661.86

principal repaid + interest paid
= 10000.00 + 661.86
= $10,661.86

final payment = 879.67 + 8.80 = $888.47

Blindly collecting twelve payments of $888.49 would collect $0.02 too much under this ledger. That difference is handled explicitly rather than silently erasing a balance.

The regulation’s commentary recognizes that collecting whole cents may require adjustment of the final installment. That disclosure observation does not prescribe this example’s particular ledger-rounding policy. C037–C040, C042, C046. Consumer Financial Protection Bureau

E03 — Zero-interest version of E02

Keep the same $10,000 principal, 12 monthly periods, and payment dates. Change only the interest rate to zero. There are no fees.

Plain text

M = P / n
  = 10000 / 12
  = $833.333333...

Choose eleven ordinary payments of $833.33, then adjust the final payment.

Month or group Payment Interest Result
Month 1 $833.33 $0.00 Ending principal $9,166.67
Month 2 $833.33 $0.00 Ending principal $8,333.34
Months 1–11 combined $9,166.63 $0.00 Principal remaining $833.37
Month 12 $833.37 $0.00 Ending principal $0.00
Total $10,000.00 $0.00 Principal repaid $10,000.00

Plain text

11 * 833.33 = $9,166.63
10000 - 9166.63 = $833.37

Twelve payments of $833.33 would leave $0.04 unpaid. No division by the interest rate is used.

Zero interest does not by itself establish that a transaction is outside Regulation Z; the coverage rule also addresses written agreements payable in more than four installments, subject to the other coverage conditions and exemptions. Nor would a zero note rate establish zero credit cost if separately classified charges existed. They do not exist in E03. C002, C041, C047. Consumer Financial Protection Bureau

E04 — Same E02 loan, with extra principal after installment 3

Everything from E02 remains unchanged except this specified action:

Immediately after the regular third installment, apply an additional $2,000 directly to principal.

The model assumes that this application is permitted, immediate, and free of a penalty or other charge. It does not establish those rights for an actual loan.

There is no recast. The ordinary installment remains $888.49 on the original monthly sequence until a smaller final payoff payment.

The recurrence becomes:

Plain text

I_k = round_cent(0.01 * B_(k-1))
B_k = B_(k-1) + I_k - regular_payment_k - extra_principal_k

At month 3:

Plain text

balance after regular payment = 8415.14 + 84.15 - 888.49
                              = $7,610.80

balance after extra principal = 7610.80 - 2000.00
                              = $5,610.80
Complete accelerated schedule
Month Opening principal Interest Regular/final payment Extra principal Total principal paid Ending principal
1 $10,000.00 $100.00 $888.49 $0.00 $788.49 $9,211.51
2 9,211.51 92.12 888.49 0.00 796.37 8,415.14
3 8,415.14 84.15 888.49 2,000.00 2,804.34 5,610.80
4 5,610.80 56.11 888.49 0.00 832.38 4,778.42
5 4,778.42 47.78 888.49 0.00 840.71 3,937.71
6 3,937.71 39.38 888.49 0.00 849.11 3,088.60
7 3,088.60 30.89 888.49 0.00 857.60 2,231.00
8 2,231.00 22.31 888.49 0.00 866.18 1,364.82
9 1,364.82 13.65 888.49 0.00 874.84 489.98
10 489.98 4.90 494.88 0.00 489.98 0.00
Total — $491.29 $8,491.29 $2,000.00 $10,000.00 $0.00
Controlled comparison
Item E02 scheduled path E04 extra-principal path Difference
Original principal $10,000.00 $10,000.00 $0.00
Nominal annual / monthly rate 12% / 1% 12% / 1% None
Posting and allocation convention Same defined model Same defined model None
Extra principal $0.00 $2,000.00 at month 3 Earlier principal repayment
Final payment $888.47 at month 12 $494.88 at month 10 Earlier mathematical payoff
Total interest $661.86 $491.29 $170.57 saved
Total cash paid, including extra principal $10,661.86 $10,491.29 $170.57 less
Principal repaid $10,000.00 $10,000.00 $0.00
Ending balance $0.00 $0.00 $0.00

Plain text

9 * 888.49 + 2000.00 + 494.88 = $10,491.29
10000.00 + 491.29 = $10,491.29

interest saved = 661.86 - 491.29 = $170.57
cash difference = 10661.86 - 10491.29 = $170.57

The $2,000 is included in total cash paid. It is accelerated principal, not itself an interest saving.

Neither this calculation nor the disclosure rules establish automatic advancement of due dates, an automatic recast, a prepayment right, or the absence of a penalty. Regulation Z’s prepayment disclosure distinguishes unpaid-balance finance charges from other finance-charge structures; it does not supply the entire substantive prepayment law. C043–C044, C048. Consumer Financial Protection Bureau+2

E05 — Upfront fee, amount financed, and numerical rate comparison

A. Legal-method status

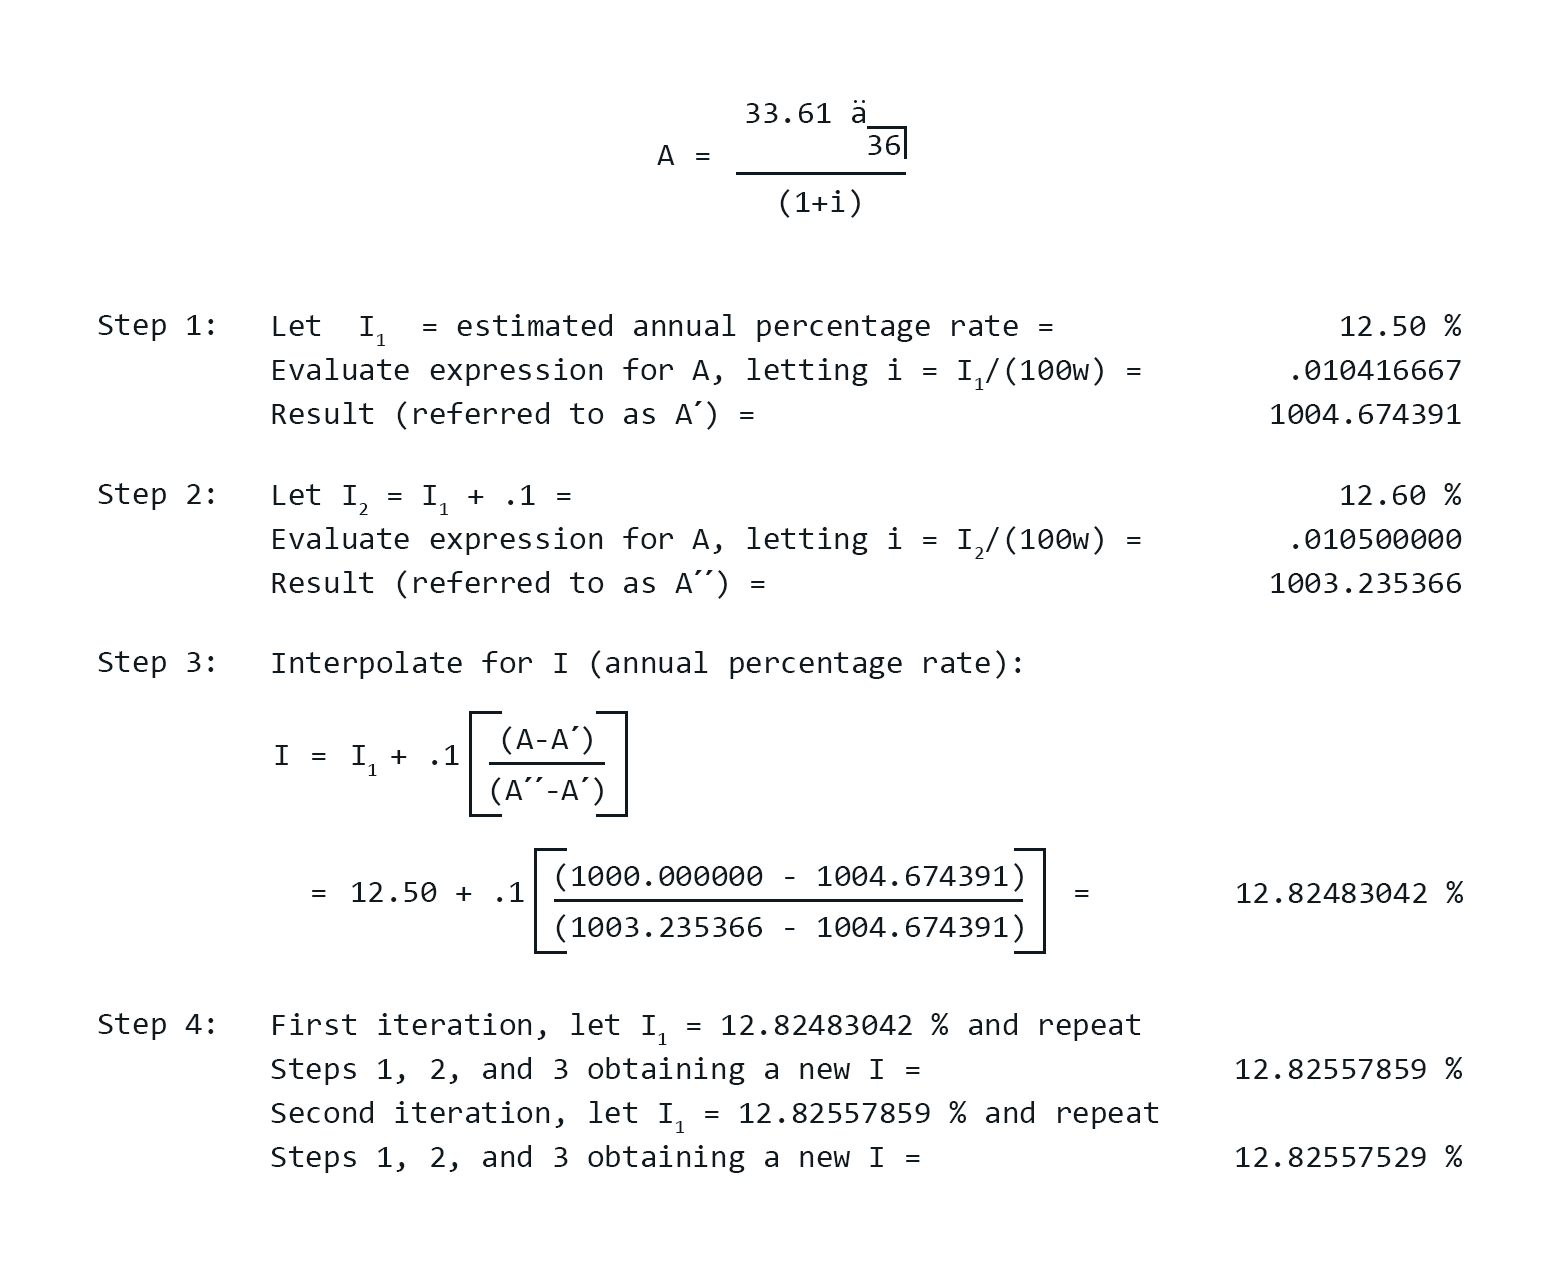
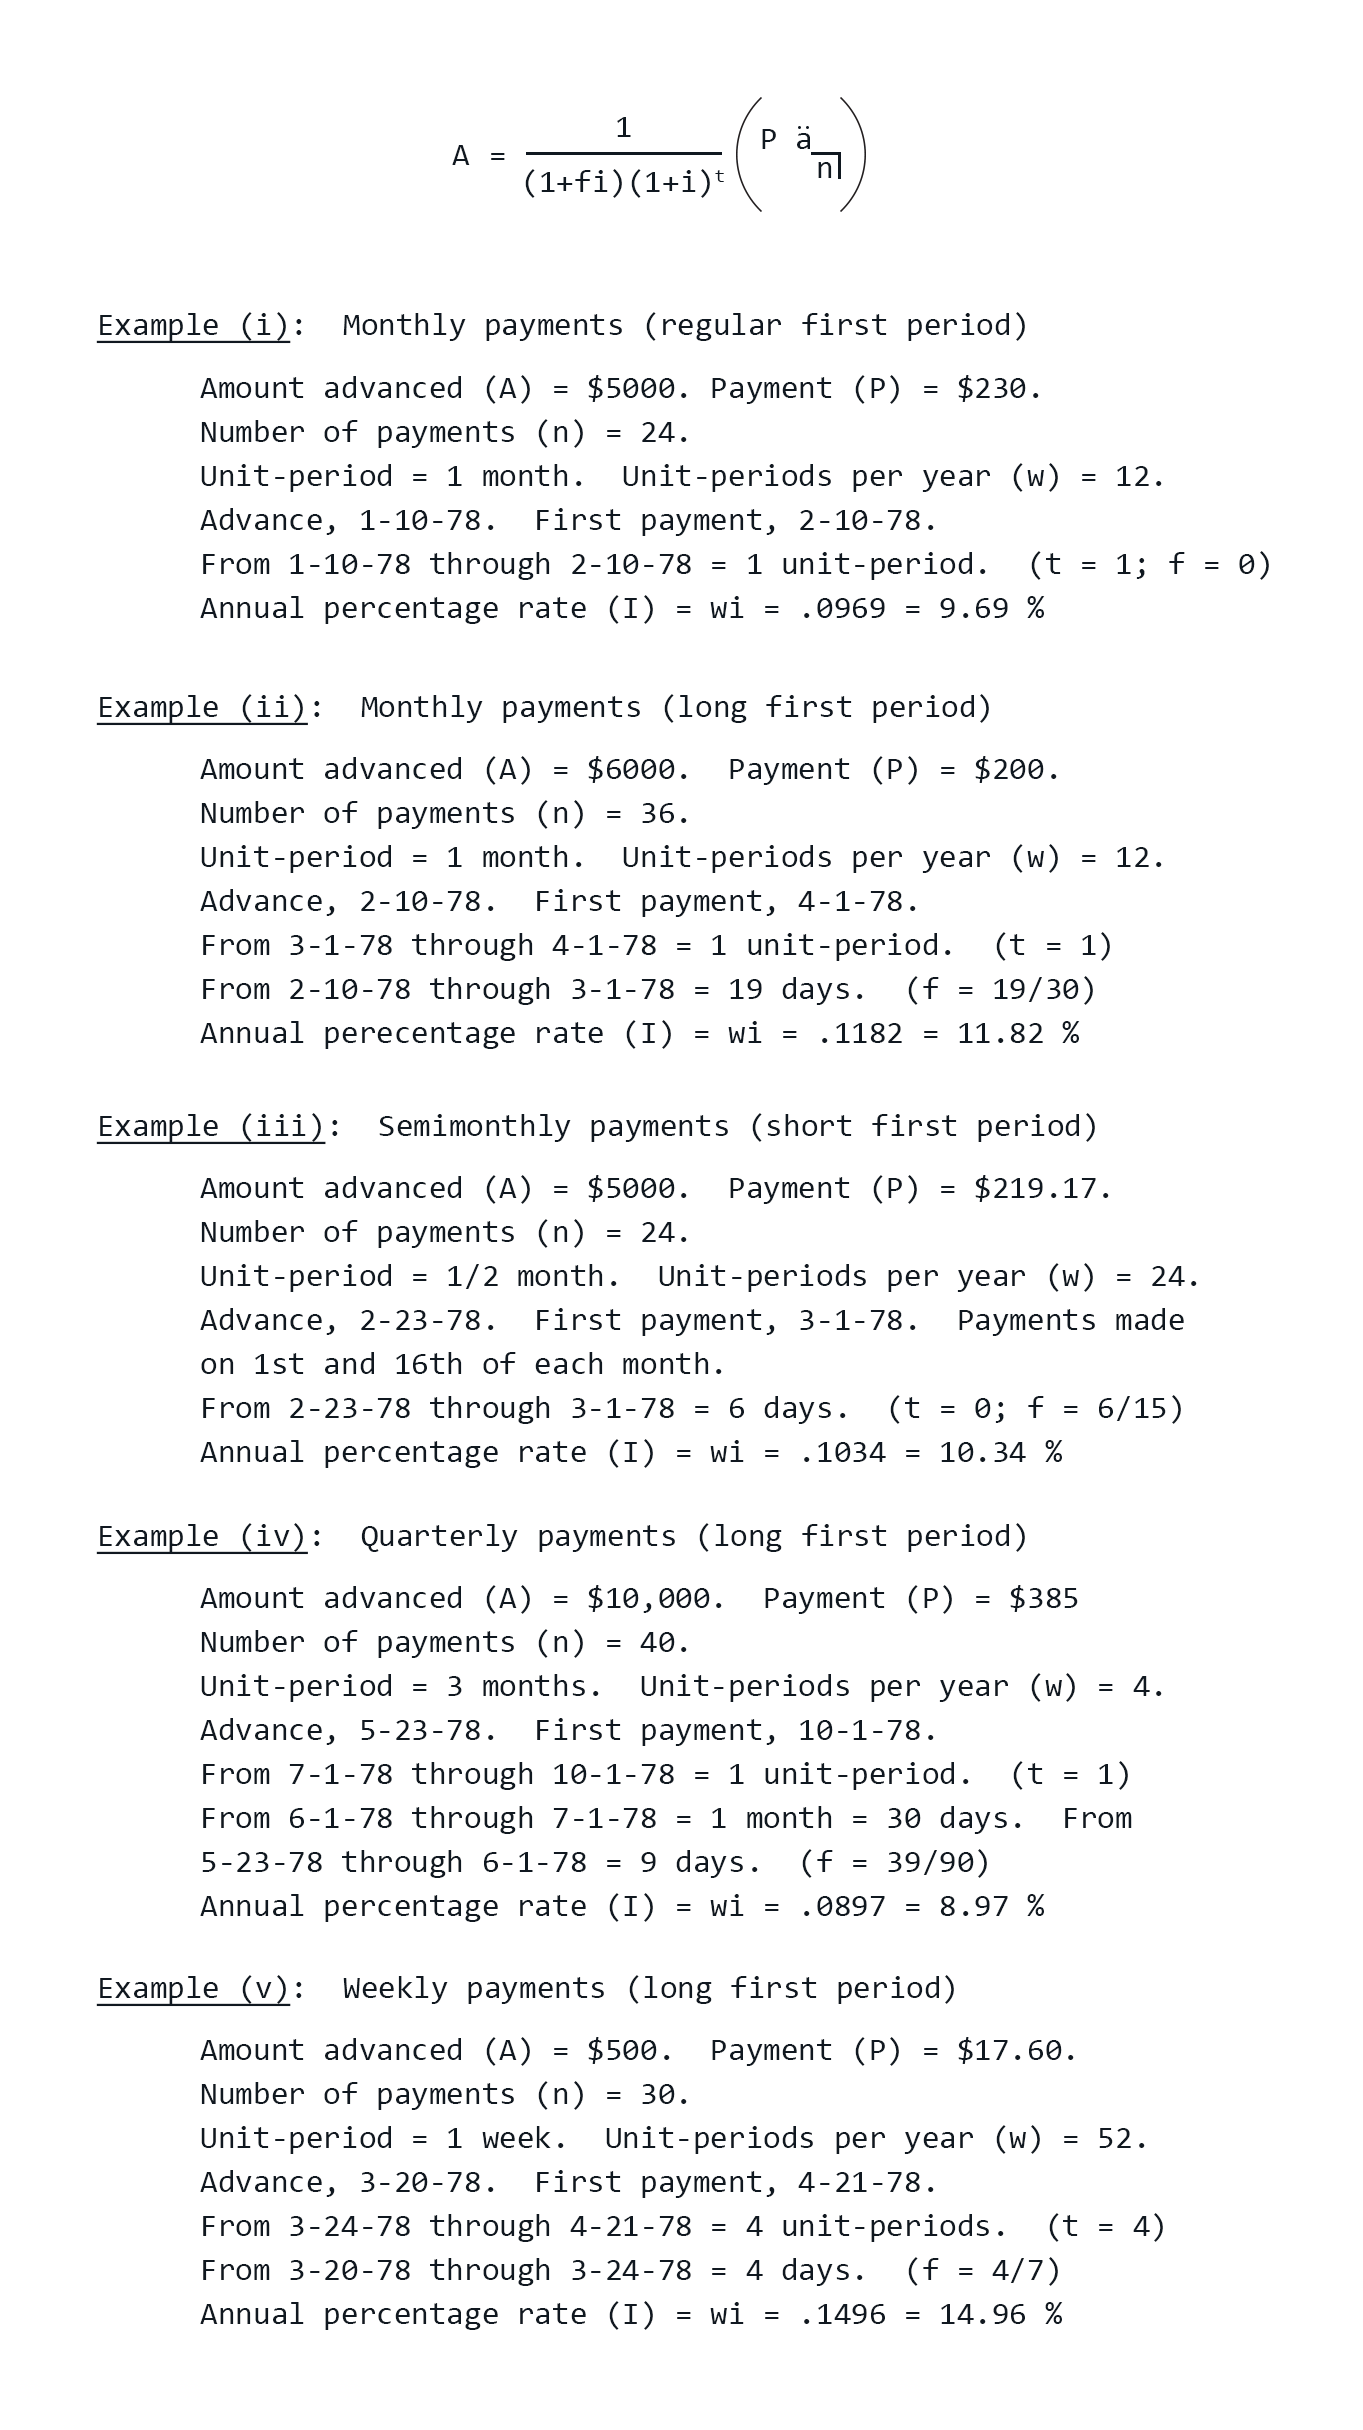
The readable sources establish that the closed-end APR analysis concerns both amounts and timing; Regulation Z permits the actuarial method or the United States Rule. Appendix J’s readable prose describes nominal annualization and unit periods.

However, the retrieved current Appendix J page did not expose several necessary equation and example images as readable content. Direct image retrieval and the official annual-CFR PDF backup did not resolve that limitation. No result below is represented as a legal APR, a disclosed APR verified against Appendix J, or a compliance certification. C025–C030, C056. Consumer Financial Protection Bureau+3

B. Cash-flow assumptions

Use the E02 repayment stream:

Plain text

t = 0: gross loan advance of $10,000
t = 1 through 11 model months: payments of $888.49
t = 12 model months: payment of $888.47

Add a hypothetical $300 fee paid separately at t = 0. The note balance remains $10,000.

The two classification branches are conditional:

  1. Included branch: the $300 is legally a finance charge and, because paid separately at consummation, a prepaid finance charge.
  2. Excluded branch: the $300 actually satisfies an applicable exclusion—for example, a qualifying application fee charged to all applicants whether credit is extended or not.

These are alternative factual/legal conditions. The label is not an election available merely to obtain a preferred APR.

C. Accounting comparison
Measure No-fee reference $300 included prepaid finance charge $300 legally excluded, paid separately
Interest-bearing note principal $10,000.00 $10,000.00 $10,000.00
Gross cash received at t = 0 $10,000.00 $10,000.00 $10,000.00
Separate t = 0 fee payment $0.00 $300.00 $300.00
Net t = 0 cash position $10,000.00 $9,700.00 $9,700.00
Conditional amount financed $10,000.00 $9,700.00 $10,000.00
Scheduled interest $661.86 $661.86 $661.86
Conditional finance charge $661.86 $961.86 $661.86
Scheduled total of payments $10,661.86 $10,661.86 $10,661.86
All consumer cash outflows, including separate origination fee $10,661.86 $10,961.86 $10,961.86
Legal APR calculated in this report Held Held Held

The included branch reconciles as follows:

Plain text

amount financed = 10000 - 300 = $9,700.00
finance charge = 661.86 + 300 = $961.86

amount financed + finance charge
= 9700.00 + 961.86
= $10,661.86 scheduled total of payments

all cash outflows
= 300.00 + 10661.86
= $10,961.86

The amount-financed treatment follows the structure of the official §18(b)(3) examples, including the need to avoid subtracting a charge twice. The treatment of the repayment schedule follows comment 18(g)-1. Consumer Financial Protection Bureau+1

Withheld-fee variation: If the included $300 were withheld from a $10,000 note instead, the consumer would receive $9,700 and later pay $10,661.86. Do not also add a fictitious second $300 cash payment.

Financed-on-top variation: If a $300 charge were added to a $10,000 advance, producing a $10,300 interest-bearing note, a new repayment schedule would be needed. The E02 $888.49 payment cannot be reused unchanged. If that $300 is a finance charge, the amount-financed calculation must exclude it without double subtraction; if it is a financed non-finance-charge item, its treatment differs. Actual classification remains unresolved.

D. Separately labeled numerical IRR calculation

Define:

Plain text

C_1 through C_11 = 888.49 dollars
C_12 = 888.47 dollars
q = numerical rate per equal model month
V = specified initial comparison value

Solve:

Plain text

F(q) = sum[C_k / (1 + q)^k, for k = 1 through 12] - V = 0

This is the present-value equation for the stated cash flows. It can also be derived by setting the terminal balance of a hypothetical accumulation recurrence to zero. It is presented here as finance mathematics, not as a verified implementation of Appendix J.

Convert the numerical monthly root as follows:

Plain text

nominal annualized percentage = 1200 * q
effective annualized percentage = 100 * [(1 + q)^12 - 1]
Comparison input Monthly numerical root q Nominal annualized numerical rate Effective annualized numerical rate
V = $10,000 0.010000095523607588 12.0001146283% 12.6826309005%
V = $9,700 0.014854202297695518 17.8250427572% 19.3558891893%

The very small difference between 12% and the first numerical annualized rate reflects the chosen cent-posted payment stream. It does not change the stipulated note rate.

In the excluded-fee branch, the consumer’s economic cash-flow calculation still starts with net $9,700 and therefore produces the same approximately 17.8250% annualized numerical rate. A conditional calculation using the $10,000 amount-financed input produces the other root. That difference illustrates why economic cash cost and legally defined disclosure inputs must not be conflated.

E. Numerical convergence and legal tolerances are different checks

The numerical computation used bisection on:

Plain text

0 <= q <= 0.05 per month

For V = $9,700:

Plain text

F(0) = +$961.86
F(0.05) = approximately -$1,825.10069028

For V = $10,000:

Plain text

F(0) = +$661.86
F(0.05) = approximately -$2,125.10069028

After 60 bisection iterations in ordinary floating-point arithmetic, the evaluated present-value residuals at the reported roots were approximately:

Plain text

V = 9700:  -$0.00000000000909
V = 10000: +$0.00000000001091

Both are below the stated numerical residual target of $0.00000001. This is an arithmetic check for these inputs, not general tool validation.

The relevant regulatory accuracy provisions are separate:

Provision Rule relevant to this bounded comparison Limitation
§1026.22(a)(2) Regular-transaction APR tolerance: ±0.125 percentage point, or 12.5 basis points Not a relative 0.125% error; does not cure incorrect fee classification
§1026.22(a)(3) Specified irregular transactions: ±0.25 percentage point An irregular first period or first/final payment alone is excluded from that irregularity definition
§1026.18(d)(2) For the non-real-property/non-dwelling category addressed there: finance-charge tolerance is ±$5 when amount financed is $1,000 or less and ±$10 when it exceeds $1,000 A dollar finance-charge tolerance is not an APR tolerance or charging authorization
Appendix J(b)(9)(ii), readable prose Sufficient numerical precision and iteration are required to obtain the stated rounded result The unreadable operative equations prevent legal-method verification here

These rules do not convert the numerical outputs into compliant APRs. C027–C029, C049–C051. Consumer Financial Protection Bureau+3

E06 — Payment below accruing interest

Hypothetical inputs

Plain text

initial principal = $1,000
monthly rate = 1%
payment at each month-end = $5
observation period = 3 months
no fees

For both branches, payments are assumed to pay accrued interest before principal. The legal and contractual allocation rule is not established.

Branch A: Unpaid interest remains separate; no capitalization

Let U be accrued unpaid interest. Interest is calculated only on the unchanged $1,000 principal.

Month Opening principal New interest Cash payment to interest Ending principal Ending unpaid interest U Principal + unpaid interest
1 $1,000.00 $10.00 $5.00 $1,000.00 $5.00 $1,005.00
2 1,000.00 10.00 5.00 1,000.00 10.00 1,010.00
3 1,000.00 10.00 5.00 1,000.00 15.00 1,015.00

Plain text

new interest over three months = $30.00
cash paid = $15.00
unpaid interest = $15.00

ending principal + unpaid interest
= 1000.00 + 30.00 - 15.00
= $1,015.00

A general no-capitalization accounting recurrence, under the stipulated interest-first allocation, is:

Plain text

interest_paid = min(payment, old_unpaid_interest + new_interest)
principal_paid = min(principal, max(payment - old_unpaid_interest - new_interest, 0))
new_unpaid_interest = old_unpaid_interest + new_interest - interest_paid
new_principal = principal - principal_paid
Branch B: Unpaid interest is capitalized after each payment, only if legally and contractually permitted

This branch assumes permission solely to illustrate the mathematics. No source here establishes that permission for an actual loan.

Month Opening interest-bearing balance New posted interest Cash payment Interest capitalized after payment Ending interest-bearing balance
1 $1,000.00 $10.00 $5.00 $5.00 $1,005.00
2 1,005.00 10.05 5.00 5.05 1,010.05
3 1,010.05 10.10 5.00 5.10 1,015.15

Month 3’s unrounded interest is $10.1005, posted as $10.10 under this branch’s cent convention.

Plain text

total new interest = 10.00 + 10.05 + 10.10 = $30.15
cash paid = $15.00

ending balance
= 1000.00 + 30.15 - 15.00
= $1,015.15

The capitalized component is not new cash advanced to the consumer. There is no principal reduction in either branch.

Regulation Z’s discussion of actuarial and United States Rule APR computations distinguishes treatment of unpaid finance charges. Those calculation descriptions do not independently authorize servicing capitalization. C036, C052–C053. Consumer Financial Protection Bureau+1

4. Failure branches and gateways

Failure or gateway What fails or remains uncertain Required bounded correction Related claims/examples
Monthly-versus-daily mismatch A 1% monthly charge on $10,000 is $100; 30 days at 12%/365 is about $98.63. Monthly payment frequency does not make them identical. Select the actual permitted accrual convention and keep it throughout the schedule. C033–C040; E01–E02
Irregular payment date or amount The equal-period annuity formula does not determine the effect of an early, late, partial, or irregularly timed payment. Establish credited date, endpoint rule, allocation, and applicable legal APR timing convention; then rebuild the cash flows. C035, C039, C056
Variable rate A single constant r cannot represent an unspecified future rate path. Obtain the published contractual reset/index/margin/cap and payment-adjustment terms; investigate the applicable disclosure rules separately. C038–C040; S007 §18(f)
Balloon or residual balance A schedule ending with B_n > 0 has not amortized the balance to zero. Identify the maturity payment or other authorized residual treatment; do not silently write the remainder off. C042
Late fee A separate fee is neither automatically interest nor automatically a lawful charge. Exclusion from finance charge does not erase cash cost. Read the actual charge trigger, amount, applicable law, and §4(c)(2) classification conditions. Keep the fee separate from ordinary interest. C018, C035
Insufficient payment Using payment - interest as a negative principal reduction without explanation hides whether unpaid interest remains separate or is capitalized. Track principal and unpaid interest separately unless a permitted capitalization rule is established. C036; E06
Precomputed/add-on interest or Rule of 78s E04’s declining-balance savings cannot be transferred mechanically. Separate packet for complete current rebate/prepayment authorities, including examination of 15 U.S.C. §1615, relevant jurisdictional law, and published contract terms. No Rule-of-78s result is asserted here. C019, C044
Disputed or uncertain fee A numerical rate cannot resolve whether a fee belongs in finance charge. Preserve included/excluded branches until the relevant §4 test and transaction facts are established. C008–C021; E05
Consumer versus business credit Personal/family/household purpose and applicable exemptions are threshold questions. A product label is insufficient. Apply the complete relevant coverage and purpose provisions to an authorized factual setting; no borrower determination here. C001–C003
Secured versus unsecured credit Real-property/dwelling transactions can have different disclosure provisions and fee rules. Identify the security and product gateway before choosing the disclosure framework. Mortgage-specialized analysis remains outside this pass. C004, C016

5. Source register — R004-P1-S001 onward

Read-status convention: “Fresh” means content actually retrieved and read in this investigation. HTML sources are unpaginated unless otherwise stated. Multiple URLs for the same statute, regulation, commentary, or appendix are grouped as the same document family; they are not presented as independent corroboration.

Currentness limit: The official current pages were checked on October 27, 2026, but their displayed compilation dates differ. The eCFR captures displayed Title 12 as updated through October 23, 2026. The CFPB index stated that Part 1026 was most recently amended April 8, 2026; that is not an amendment date for every section. The statutory pages displayed the currency specified below. No claim is made that a separate comprehensive Federal Register and session-law audit closed every possible publication-to-compilation lag. ecfr.gov+3

Source ID Issuer/title and complete literal URL(s) Exact relevant location Version, effective trigger, or status Actual check date and fresh read extent Jurisdiction and contract limits
R004-P1-S001 U.S. House, U.S. Code, 15 U.S.C. §1605 — Determination of finance charge. https://uscode.house.gov/us/usc/119-121/t15/s1605/ §1605(a)–(f), especially (a) general definition and third-party closing charges; (b)–(e) conditional exclusions Body displayed currency through P.L. 119-121, October 9, 2026. Source credits include enactment May 29, 1968 and later amendments; effective-date history was not independently reconstructed. 2026-10-27 PDT. Fresh: operative (a)–(f) and selected notes. Recovered after failed alternate routes. Federal TILA classification; does not establish coverage or charging authority for a particular loan. uscode.house.gov
R004-P1-S002 U.S. House, U.S. Code, 15 U.S.C. §1606 — Determination of annual percentage rate. https://uscode.house.gov/us/usc/119-121/t15/s1606/ §1606(a)–(e), especially (a)(1) and (c) Body displayed currency through P.L. 119-121, October 9, 2026. Original 1968 provision with later amendments; no independent effective-history audit. 2026-10-27 PDT. Fresh: complete operative (a)–(e). Statutory APR computation authority; its computational allocation is not a universal servicing waterfall. uscode.house.gov
R004-P1-S003 U.S. House, U.S. Code, 15 U.S.C. §1638 — Requirements for certain mortgages and other consumer credit transactions. https://uscode.house.gov/us/usc/119-118/t15/s1638/ Relevant complete §1638(a)(1)–(12) Page body stated currency through P.L. 119-120, October 7, 2026, despite the different number in its URL. That displayed body currency is recorded; no inference from the URL alone. 2026-10-27 PDT. Fresh: relevant (a)(1)–(12); later mortgage material encountered but not fully investigated. Federal closed-end disclosures; mortgage-specialized provisions excluded from full analysis. uscode.house.gov
R004-P1-S004 CFPB, Regulation Z index; §§1026.1, .2, .3 and embedded official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/; https://www.consumerfinance.gov/rules-policy/regulations/1026/1/; https://www.consumerfinance.gov/rules-policy/regulations/1026/2/; https://www.consumerfinance.gov/rules-policy/regulations/1026/3/ §1(a)–(c); §2(a)(10)–(14), (20)–(23), (b); relevant definition comments; §3(a) and comments, selected §3(b) Current-page designation. Index: Part 1026 most recently amended April 8, 2026. This is part-wide metadata, not individual-section effective dating. 2026-10-27 PDT. Fresh: identified operative paragraphs and relevant comments; index read for metadata/discovery, not as substantive body evidence. Consumer/closed-end/creditor/exemption gateway only; no transaction-specific coverage determination. Consumer Financial Protection Bureau+3
R004-P1-S005 CFPB and eCFR, §1026.4 — Finance charge; official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/4/; https://www.consumerfinance.gov/rules-policy/regulations/1026/interp-4/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-A/section-1026.4 Relevant complete rules in (a)–(f); comments on comparable cash charges, application fees, third parties, insurance, security charges, and late charges CFPB current text; eCFR Title 12 displayed through October 23, 2026. No claim that date is this section’s amendment date. 2026-10-27 PDT. Fresh: CFPB operative clauses and relevant embedded commentary; separate interpretation page’s opening definition; eCFR visible body through (d)(3)(ii). Unrelated open-end material was not a separate investigation. Conditional federal classification rules. Real-estate and mortgage exceptions are not generalized to unsecured credit. ecfr.gov+2
R004-P1-S006 CFPB and eCFR, §1026.17 — General disclosure requirements; official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/17/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.17 §17(c)(1)–(3); comments 17(c)(1)-1–2, 17(c)(2)(i)-3, 17(c)(3)-1–2; selected (c)(4) material Current agency text; eCFR displayed through October 23, 2026. Disclosure inputs reflect the legal obligation. 2026-10-27 PDT. Fresh: complete relevant clauses/comments above; odd-first-period material only to identify the gateway, not apply the full method. Disclosure assumptions are not universal accrual, receipt-date, capitalization, or holiday-servicing rules. Consumer Financial Protection Bureau+2
R004-P1-S007 CFPB and eCFR, §1026.18 — Content of disclosures; official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/18/; https://www.consumerfinance.gov/rules-policy/regulations/1026/interp-18/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.18 Introductory scope; (b), (c), (d), (e), (g), (h), (k), (l), (p); relevant comments including 18(b)(3)-1–2, 18(g)-1, -4, 18(h)-2 Current agency text; eCFR displayed through October 23, 2026. Underlying section-specific effective history not fully audited. 2026-10-27 PDT. Fresh: relevant complete rules and associated comments; §18(c)(1)–(3) and its relevant itemization material recovered in fresh reads. Mortgage tables not fully investigated. Examples use the non-mortgage framework. Prepayment disclosures do not resolve substantive prepayment rights. ecfr.gov+3
R004-P1-S008 CFPB and eCFR, §1026.22 — Determination of APR; official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/22/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.22 Entire operative section and embedded commentary; especially (a)(1)–(3), (b)(2), comments 22(a)(1)-1–5 Current text; eCFR displayed through October 23, 2026. Section history cited 76 FR 79772, Dec. 22, 2011; 78 FR 80112, Dec. 31, 2013; 80 FR 80229, Dec. 24, 2015. Underlying rulemaking effective dates not separately read. 2026-10-27 PDT. Fresh: full section and embedded comments. Mortgage tolerances and add-on shortcut provisions were read but not applied. Provides APR methods/accuracy framework; does not validate the present numerical routine or authorize contract charges. Consumer Financial Protection Bureau+1
R004-P1-S009 CFPB/eCFR, Appendix J — APR computations for closed-end credit; official interpretation. https://www.consumerfinance.gov/rules-policy/regulations/1026/j/; https://www.consumerfinance.gov/rules-policy/regulations/1026/interp-j/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/appendix-Appendix%20J%20to%20Part%201026 Readable (a), (b)(1)–(6), textual (b)(9), example headings/introductions; complete official comment J-1–2 Linked from current Regulation Z. The current display did not make all equation assets readable. 2026-10-27 PDT. Fresh partial body: prose read; eCFR extraction stopped before the needed equation content. Not a complete operative-equation read. Supports framework only. Legal calculation held because symbols/equations/examples in (b)(7)–(9) and relevant (c) panels were not readable. Consumer Financial Protection Bureau+3
R004-P1-S010 CFPB, Appendix J equation/image assets, same underlying document as S009. https://files.consumerfinance.gov/eregulations/ER22DE11.062-1.png; https://files.consumerfinance.gov/eregulations/ER22DE11.062-2.png; https://files.consumerfinance.gov/eregulations/ER22DE11.063-1.png; https://files.consumerfinance.gov/eregulations/ER22DE11.063-2.png; https://files.consumerfinance.gov/eregulations/ER22DE11.064-1.png; https://files.consumerfinance.gov/eregulations/ER22DE11.066-1.png Symbol panels, general equation, iteration example, regular-payment example, odd-final-payment example Assets linked by current page. Filename dates are not treated as independently verified adoption/effective dates. 2026-10-27 PDT. Attempted: responses were image placeholders without readable image contents. No equation read or visual verification claimed. Failed recovery, not corroborating substantive evidence.
R004-P1-S011 U.S. Government Publishing Office, 2025 CFR, Title 12, volume 9, Appendix J. https://www.govinfo.gov/content/pkg/CFR-2025-title12-vol9/pdf/CFR-2025-title12-vol9-part1026-appJ.pdf Printed pages 436–447; zero-based PDF indices 0–11 January 1, 2025 edition, historical backup rather than proof of October 2026 currency 2026-10-27 PDT. Fresh extracted text: substantive prose on printed pp. 436–437, indices 0–1. Later pages supplied headers/graphic markers without readable equations. Screenshot attempts at indices 2–3 did not yield inspectable content. No visual inspection claimed. Backup failed to close the Appendix J equation gap. govinfo.gov+1
R004-P1-S012 CFPB, Withdrawn guidance. https://www.consumerfinance.gov/compliance/guidance/withdrawn-guidance/ Register entries and last-modified metadata Displayed last modified July 22, 2026, 12:12 PM EDT 2026-10-27 PDT. Fresh: register body and metadata read. No CFPB circular, bulletin, or advisory was relied on. Withdrawal register not treated as repeal of retrieved statutes, regulations, or Supplement I. Consumer Financial Protection Bureau+1
R004-P1-S013 Bank of America, public generic Explanation of Simple Interest Calculation. https://secure.bankofamerica.com/content/pdf/en_us/Explanation_of_Simple_Interest_Calculation.pdf One unnumbered printed page; zero-based PDF index 0; steps 2–3 Document marked Rev. 12/17/2010 2026-10-27 PDT. Fresh: complete extracted text of the one-page document. Text read, not visual inspection. Establishes only its stated 365/366 convention. Not a current-policy finding, consumer agreement, or universal legal rule. secure.bankofamerica.com
R004-P1-S014 FDIC, Consumer Compliance Examination Manual, TILA section. https://www.fdic.gov/consumer-compliance-examination-manual/v-1-truth-lending-act-tila Search discovery only Body access returned 403 2026-10-27 PDT. Failed body access: no substantive body reliance Search snippet is not evidence of a complete operative read. Current Regulation Z commentary supplied the relied-on denominator discussion instead.

6. Atomic claim register — A004

The mathematical rows identify derivations and model assumptions explicitly. They are not statutory assertions. Schedule-result rows refer to the complete displayed schedules, whose individual entries are reproducible from the stated recurrence.

6.1 Coverage, definitions, charges, and disclosures

Claim ID Area Atomic assertion Source and exact pinpoint Assumptions, conditions, exclusions, and status
R004-P1-C001 A004 Closed-end credit is credit other than open-end credit; consumer credit concerns primarily personal, family, or household purposes. S004, §2(a)(10), (12) Definition established; no transaction-specific purpose finding.
R004-P1-C002 A004 Zero interest alone does not exclude coverage; written repayment in more than four installments is relevant under the general coverage rule. S004, §1(c)(1) Other coverage conditions and exemptions still matter; E03 assumes the relevant consumer setting.
R004-P1-C003 A004 Business/commercial/agricultural purpose and organizational-credit provisions are coverage gateways; mixed-purpose analysis cannot be replaced by a label. S004, §3(a), comments 3(a)-1–10 Gateway answered; actual classification unresolved and outside this pass.
R004-P1-C004 A004 §18 excludes mortgage transactions subject to §19(e) and (f) from its general disclosure framework; security can change applicable provisions. S007, §18 introductory paragraph; §18(s) gateway Examples assume the non-mortgage setting; no mortgage-specialized conclusion.
R004-P1-C005 A004 Disclosures reflect the legal obligation; the disclosure calculation is not independent permission to impose a charge. S004, §1(b); S006, §17(c)(1), comments 1–2 Contract and applicable law remain required.
R004-P1-C006 A004 B is the model’s interest-bearing principal, kept distinct from unpaid accrued interest U. Defined accounting model; S004, §2(b)(3); S006, §17(c)(1) No universal statutory definition of every contract’s principal balance is asserted.
R004-P1-C007 A004 A periodic rate applies to a specified period; an annual note rate requires its stated conversion/accrual convention. S004, §2(a)(21), comment 1 Decimal per period in calculations; fee-inclusive APR is not substituted for the note rate.
R004-P1-C008 A004 Finance charge is the legally classified dollar cost of consumer credit, including direct or indirect qualifying charges. S001, §1605(a); S005, §4(a) Coverage and exclusions required.
R004-P1-C009 A004 Interest and loan fees are listed finance-charge categories, subject to the express exclusions. S005, §4(b)(1), (3), introductory qualification to (b) A fee label does not bypass (c)–(e).
R004-P1-C010 A004 A charge of a type payable in a comparable cash transaction is excluded; a credit-specific excess requires separate treatment. S001, §1605(a); S005, §4(a), comment 4(a)-1 Requires a genuinely comparable cash-charge basis.
R004-P1-C011 A004 Application fees charged to all applicants, whether or not credit is extended, are excluded. S005, §4(c)(1), comment 4(c)(1)-1 E05’s excluded branch is conditional on satisfying this test, not merely naming the fee “application.”
R004-P1-C012 A004 Third-party charges can be included when use is required or to the extent retained by the creditor, unless otherwise excluded. S005, §4(a)(1)(i)–(ii) Consumer choice of provider does not by itself settle inclusion.
R004-P1-C013 A004 Closing-agent charges have a separate test concerning required services, required charges, or retained portions. S001, §1605(a); S005, §4(a)(2) Not a universal rule for all third-party fees; mortgage-broker special rule not generalized.
R004-P1-C014 A004 Specified voluntary credit-insurance premiums can be excluded only with the required optionality, written cost/term disclosures, and affirmative request. S001, §1605(b); S005, §4(d)(1)(i)–(iii) Optionality alone is insufficient. No insurance product is evaluated.
R004-P1-C015 A004 Specified property-insurance premiums can qualify for exclusion under consumer-choice and disclosure conditions, even where insurance is required. S001, §1605(c); S005, §4(d)(2)(i)–(ii) Includes the stated conditions concerning single-interest insurance/subrogation where relevant; no universal “mandatory fee” rule.
R004-P1-C016 A004 The listed bona fide, reasonable real-estate-related fee exclusion has a defined real-property/residential-mortgage scope. S001, §1605(e); S005, §4(c)(7)(i)–(v) Not transferred to all unsecured loans.
R004-P1-C017 A004 Certain security-related public-official charges and substitute insurance require the specified itemization, disclosure, and statutory conditions for exclusion. S001, §1605(d); S005, §4(e) No blanket exclusion for every “government” or third-party charge.
R004-P1-C018 A004 Charges for actual unanticipated late payment/default can be excluded from finance charge under §4(c)(2). S005, §4(c)(2); S007, §18(l) and relevant commentary Exclusion is not authorization, waiver of cash cost, or proof that a disputed fee qualifies.
R004-P1-C019 A004 A prepaid finance charge includes qualifying charges paid separately before/at consummation or withheld from proceeds; precomputed interest is not automatically prepaid merely because precomputed. S004, §2(a)(23), comments 1–3 Classification as finance charge must first be established.
R004-P1-C020 A004 Amount financed follows §18(b)’s calculation and must avoid double subtraction of included finance charges. S003, §1638(a)(2); S007, §18(b)(1)–(3), comment 18(b)(3)-1 Distinguish the regulatory principal-loan input from the note face amount.
R004-P1-C021 A004 Amount financed need not equal cash delivered directly to the consumer. S007, §18(c)(1)(i)–(iv) Amounts credited or paid on the consumer’s behalf may differ from direct proceeds.
R004-P1-C022 A004 The payment schedule addresses number, amounts, and timing; prepaid finance charges are not separately inserted as schedule payments. S007, §18(g), comments 18(g)-1, -4 Other permitted components can appear in scheduled payments; allocation remains a separate question.
R004-P1-C023 A004 Total of payments is the sum of disclosed schedule payments; amount financed + finance charge is valid for the simple E05 streams, not asserted as every possible cash-flow identity. S003, §1638(a)(5); S007, comment 18(h)-2 and 18(g)-1 Optional or other schedule components and separate upfront cash require careful reconciliation.
R004-P1-C024 A004 Total interest is the sum of modeled interest accruals; it need not equal finance charge or interest paid. Defined arithmetic; S005, §4(b); E02, E05, E06 Period and accrual/payment basis must be stated.

6.2 APR, timing, and mathematical models

Claim ID Area Atomic assertion Source and exact pinpoint Assumptions, conditions, exclusions, and status
R004-P1-C025 A004 Closed-end legal APR depends on amount and timing under the applicable actuarial or United States Rule framework. S002, §1606(a); S008, §22(a)(1) Legal method identified; E05 legal result held.
R004-P1-C026 A004 Appendix J describes APR as a nominal annual rate based on the unit-period rate and number of unit periods per year. S009, Appendix J(b)(1), (b)(4)–(5) This legal annualization is distinct from (1+r)^m - 1; full equation implementation unread.
R004-P1-C027 A004 The general regular-transaction APR accuracy allowance is ±1/8 percentage point. S008, §22(a)(2) 0.125 percentage point, not 0.125% relative error.
R004-P1-C028 A004 The specified irregular-transaction allowance is ±1/4 percentage point; an irregular first period or first/final payment alone does not trigger that definition. S008, §22(a)(3), relevant commentary E02’s final cent adjustment alone is not a basis to assume irregular tolerance.
R004-P1-C029 A004 §18(d)(2)’s finance-charge dollar tolerances differ from APR percentage-point tolerances. S007, §18(d)(2) Non-real-property/non-dwelling category: ±$5 at amount financed ≤$1,000; ±$10 above $1,000.
R004-P1-C030 A004 The original amortization method alone does not determine reportable APR. S002, §1606(a); S005, §4; S007, §18(b); S008, §22(a)(1) Also requires correct classification, amount financed, dates, payments, and legal calculation method.
R004-P1-C031 A004 A constant-period mathematical effective annual rate is (1+r)^m - 1. Derived by multiplying one-period growth factors m times Compounding/equivalent-rate assumption; not charging authority or a legally labeled APR.
R004-P1-C032 A004 A numerical IRR is a root of a specified discounted cash-flow equation; convergence alone does not verify legal APR compliance. Derived present-value identity; S008, §22(b)(2), comment 22(a)(1)-5 E05 is expressly an approximate numerical estimate.
R004-P1-C033 A004 Constant-balance simple accrual is Bad/D; segmented accrual sums such terms under the same stated model. S013, steps 2–3; algebraic extension stated in §2.1 Dollar balance, annual decimal rate, counted days, stated denominator; actual application held.
R004-P1-C034 A004 Identified sources discuss 365/360 distinctions and a stated 365/366 convention; none establishes one universal convention. S006, comment 17(c)(3)-1(ii); S004, comment 2(a)(21)-1; S013, step 2 Complete Actual/Actual and 30/360 conventions not established.
R004-P1-C035 A004 Actual payment-crediting dates, inclusivity, partial-payment effects, and due-date changes require the legal obligation and applicable rules. S006, §17(c)(1), comments 1–2; §17(c)(2)(i), comment 3 No receipt/posting/value-date or holiday rule invented.
R004-P1-C036 A004 Accrued unpaid interest and capitalized interest are separate accounting states; APR computational descriptions do not grant capitalization authority. S008, comments 22(a)(1)-2–3; S009, Appendix J(a)(2)–(3); E06 Real capitalization permission unresolved.
R004-P1-C037 A004 Ledger precision, posted-cent rounding, and cash-payment rounding can produce different totals and final installments. Derived E01/E02 calculations; S006, comment 17(c)(3)-1(i) The chosen half-up posting rule is hypothetical, not a universal legal requirement.
R004-P1-C038 A004 r = annual nominal rate / 12 is used only because the monthly convention defines that relationship. Model definition; S004, §2(a)(21); algebraic effective-rate conversion Not substituted for daily accrual or fee-inclusive APR.
R004-P1-C039 A004 Under the equal-period, interest-first, no-fee model, B_k = B_(k-1)*(1+r) - M. Derived balance conservation in §2.2 Requires adequate payment or separate unpaid-interest treatment.
R004-P1-C040 A004 For r>0, equal end-period payments amortizing P over n periods satisfy M=P*r/[1-(1+r)^(-n)]. Derivation in §2.2 from C039 Fixed rate, equal periods, full amortization, no omitted charges.
R004-P1-C041 A004 At zero rate, use M=P/n, then explicitly handle cent rounding in the final installment. Derived E03 No division by zero.
R004-P1-C042 A004 A positive terminal balance requires explicit residual/balloon treatment; it is not a zero ending balance. Balance identity C039; E02/E03 final-payment checks Actual maturity and residual terms required.
R004-P1-C043 A004 Extra principal reduces later model interest only after application to principal; the calculation does not establish due-date advancement or recast rights. Derived E04; S006, §17(c)(1); S007, §18(k), (p) Immediate extra-principal application and no penalty are assumptions.
R004-P1-C044 A004 Declining-balance and precomputed-charge prepayment analyses require separate treatment; E04 savings cannot be mechanically transferred. S007, §18(k)(1)–(2); S004, comment 2(a)(23)-3 Full rebate, penalty, add-on, and Rule-of-78s law remains held.

6.3 Calculated results and evidence status

Claim ID Area Atomic assertion Source and exact pinpoint Assumptions, conditions, exclusions, and status
R004-P1-C045 A004 E01’s 365/360 end-rounded charges are $98.63/$100.00, with a $1.37 difference. E01 displayed inputs, equations, and rounding comparison Derived arithmetic; denominator application not adjudicated.
R004-P1-C046 A004 E02’s posted-cent schedule pays $10,000 principal and $661.86 interest, ending at exactly zero after an $888.47 final payment. E02 complete 12-row schedule Verified within stated monthly and rounding model.
R004-P1-C047 A004 E03’s eleven $833.33 payments plus $833.37 repay exactly $10,000 with no interest. E03 arithmetic Zero rate and no fees only.
R004-P1-C048 A004 E04’s controlled extra-principal path produces $491.29 interest and saves $170.57 relative to E02. E04 complete 10-row schedule and comparison Same original principal/rate/convention; allocation and no-penalty assumptions explicit.
R004-P1-C049 A004 E05’s included-fee branch yields conditional amount financed $9,700 and finance charge $961.86 while preserving the $10,000 note balance. S007, comment 18(b)(3)-1; E05 cash table Separate-at-origination fee; no double counting; legal classification conditional.
R004-P1-C050 A004 E05’s numerical annualized roots are approximately 12.0001146283% for V=10000 and 17.8250427572% for V=9700. E05 equation, bracket, iterations, residuals Decimal monthly roots; not legal APR results.
R004-P1-C051 A004 E05’s corresponding effective annualized numerical rates are approximately 12.6826309005% and 19.3558891893%. Derived from C050 using 100*((1+q)^12-1) Mathematical annual equivalence only.
R004-P1-C052 A004 E06 without capitalization ends with $1,000 principal plus $15 unpaid interest after $15 cash paid. E06 Branch A Interest accrues only on original principal; three-month observation.
R004-P1-C053 A004 E06 with stipulated monthly capitalization ends at $1,015.15 after $30.15 new interest and $15 cash paid. E06 Branch B Cent posting; capitalization legality and contract permission not established.
R004-P1-C054 A004 The CFPB Withdrawn Guidance register was freshly checked; no circular, bulletin, or advisory supports this report’s substantive conclusions. S012, full register and metadata Withdrawal is not treated here as alteration or repeal of the retrieved controlling texts.
R004-P1-C055 A004 Retrieval date and source compilation/effective dates are different; this report preserves the displayed dates and gaps. S001–S004, S006–S009, S011–S013 No complete amendment-lag or section-effective-history certification.
R004-P1-C056 A004 Complete operative Appendix J equation content was not readable; therefore the legal APR calculation is held. S009–S011; failure log below Prose read and numerical math do not substitute for the missing legal-method read.

7. Granular coverage register

“Answered” means answered within the expressly bounded reference/model scope. It does not mean an actual contract or charge has been approved.

Assigned component Status and reason Claim/example links Exact missing authority or term; next bounded action
1 — Closed-end consumer gateway Answered as a gateway C001–C004 Actual creditor/transaction coverage facts absent by design; any later application requires the relevant coverage provisions and authorized facts.
1 — Principal balance Answered as model definition; actual balance composition unresolved C006, C020–C021 Missing interest-bearing-balance clause and lawful treatment of financed charges/capitalization; inspect a published generic contract in a later packet.
1 — Interest/note/periodic rate Answered C007, C038 Actual annual-rate conversion and accrual clause absent; do not infer from payment frequency.
1 — Finance charge Answered, conditional classification framework C008–C018 Actual fee purpose, payee, comparable-cash treatment, and exclusion facts absent.
1 — Amount financed Answered C019–C021; E05 Actual principal-loan input, included charges, and disbursement structure needed for application.
1 — Payment and total of payments Answered C022–C023; E02–E05 Actual schedule and additional components absent; do not equate total of payments with every origination cash outflow.
1 — Total interest Answered C024; E02, E04, E06 Actual accrual period and paid-versus-accrued basis must be specified.
1 — Legal APR versus note rate Answered conceptually; calculation held C025–C030, C056 Missing readable operative Appendix J equations and complete applicable calculation implementation.
1 — Effective annual yield and numerical IRR Answered mathematically C031–C032, C050–C051 No additional authority needed for stated algebra; no statutory APR equivalence asserted.
1 — Fee inclusion/exclusion and timing affect comparison Answered conditionally C008–C023, C030; E05 Actual classification facts and legally applicable dates required before a legal APR.
1 — Open-end, deferred-interest, mortgage-specialized full inquiry Excluded as directed C004; remaining packets Separate product-specific sources and methods required.
2 — Constant-balance daily formula Answered C033; E01 Actual rate, balance base, days, and denominator needed for application.
2 — 365 versus 360 Answered as sourced distinction and hypothetical arithmetic C034–C045; E01 No actual adopted denominator; next read a published generic accrual clause and applicable law.
2 — Leap-year/actual-year alternative Partial C034; E01; S013 Published 365/366 statement read; complete cross-year Actual/Actual rules and current contract adoption not established.
2 — Receipt, posting, value date and endpoint inclusivity Unresolved for actual application C035 Missing credited-date and day-inclusion clause plus applicable legal requirements; later packet must establish both.
2 — Partial payments, prepayments, and residuals Answered as model boundaries C035, C042–C044; E04 Missing partial-payment holding/application, principal-curtailment, and residual terms.
2 — Accrued versus capitalized interest Answered mathematically; permission unresolved C036; E06 Missing capitalization event, base, timing, and applicable authorization/restriction.
2 — Ledger precision versus cash rounding Answered C037; E01–E03 Actual posting/rounding clause or authoritative servicing rule absent.
2 — Late/extra payments and due dates Answered as non-inference C035, C043 Missing any contractual due-date advancement, modification, recast, or deferment provision.
3 — Positive-rate payment formula and recurrence Answered and derived C039–C040; E02 Formula applies only to stated constant-period model.
3 — Number and frequency of payments Answered for equal monthly periods C022, C038–C040 Actual first-payment date and irregular-period terms absent; no real calendar assumed.
3 — First two allocations and last installment Answered with complete schedule C046; E02 No missing mathematical input for the displayed model.
3 — Rounding, balloon, residual cases Answered as arithmetic and gateway C037, C042; E02–E03 Actual balloon/maturity and residual disposition needed beyond the model.
3 — When annual rate/12 applies Answered with explicit condition C038 Actual monthly conversion convention would need contractual support.
3 — Monthly versus daily separation Answered C033–C040; E01–E02 No conversion or equivalence silently imposed.
3 — Zero rate Answered separately C041, C047; E03 No division by zero; final four-cent adjustment shown.
3 — Insufficient payment/negative amortization boundary Answered mathematically; full law deferred C036, C052–C053; E06 Missing capitalization and product-specific negative-amortization/minimum-payment law.
4 — Complete actual Appendix J method Partial; legal calculation held C025–C030, C056; S009–S011 Readable (b)(7)–(9) equation panels and applicable (c) example needed; obtain an accessible official rendering in a later packet.
4 — Actual official calculation conventions Answered to readable extent C026–C029 Unit-period/annualization prose and tolerances read; this does not close the equation gap.
4 — Cash-flow timing/frequency Answered for numerical model E05 Relative times 0–12 equal model months supplied; actual legal dates/odd-day rules unresolved.
4 — Legal APR versus numerical estimate Answered expressly C032, C050, C056 All numerical rates remain non-certified; no computed legal APR reported.
4 — Numerical convergence, tolerance, units Answered C027–C029, C050; E05 Bisection and dollar residual checked; not a general calculator validation.
4 — Mandatory, optional, third-party fees Answered as conditional tests C009–C018 Actual fee facts and compliance with exclusion conditions required.
4 — Prepaid charge, net proceeds, financed principal Answered with branches C019–C021, C049; E05 Actual separate/withheld/financed structure needed; financed-on-top version requires a new schedule.
4 — Original amortization does not determine APR alone Answered C030; E05 Correct legal classification and calculation method remain independent prerequisites.
5 — Same original principal/rate/contract convention Answered within stipulated model C046, C048; E02/E04 Both paths use identical original parameters; no unrelated-loan comparison.
5 — Specified extra principal and allocation order Answered as an assumption C043, C048; E04 Actual waterfall and right to immediate principal application not established.
5 — Interest saved, total cash, final partial payment Answered and reconciled C048; E04 No missing numerical input for the displayed comparison.
5 — Prepayment penalty/rebate/right Unresolved substantively C044 Requires complete current federal/product/jurisdictional prepayment authority and published contractual terms.
5 — Add-on/precomputed/Rule-of-78s transfer Excluded from computation; gateway preserved C019, C044 Separate current-law and contract packet; no mechanical use of E04 savings.
6 — Operative clauses, exceptions, commentary Answered for relied-on propositions; Appendix J partial S001–S009; C056 Missing equation content identified rather than filled from memory or snippets.
6 — Currentness, citation, adoption/version dates Answered with express limits C055; source table Compilation lag and complete section-specific effective histories not fully closed; later targeted official amendment audit if required.
6 — Withdrawn Guidance register Answered C054; S012 No circular/bulletin/advisory reliance requiring further withdrawal analysis.
6 — Public contract/source limits Answered S013; C034–C035 Generic 2010 instruction supplies only its stated convention; no agreement or present provider-policy inference.
6 — Prohibited records/actions Observed Session activity statement; read log No owner-restricted records or actions undertaken; no next action required.
Delivery — Complete visible tables, self-check, remaining dimensions Answered All tables; §§8–9 Self-check is not independent review; parent A004 and calculator/publication acceptance remain open.

8. Source-read and failure log

The successful fresh-read extents are recorded in the source register. The following table preserves the material failed, incomplete, or discovery-only paths.

Attempt Actual result Treatment in this report
House alternate §1605 route: https://uscode.house.gov/view.xhtml?edition=prelim&num=0&req=granuleid%3AUSC-prelim-title15-section1605 404 Not relied on; operative body recovered through S001.
House CDN alternate §1605 route: https://usc-cdn.house.gov/view.xhtml?edition=prelim&num=0&req=granuleid%3AUSC-prelim-title15-section1605 Timeout/error response Not treated as a read; S001 recovery used.
House alternate §1606 route: https://uscode.house.gov/view.xhtml?edition=prelim&num=0&req=granuleid%3AUSC-prelim-title15-section1606 Server error Not relied on; operative body recovered through S002.
Guessed withdrawn-guidance route: https://www.consumerfinance.gov/rules-policy/withdrawn-guidance/ Unavailable Correct compliance/guidance register located and read as S012.
Short eCFR §17 route: https://www.ecfr.gov/current/title-12/chapter-X/part-1026/section-1026.17 Inaccessible Canonical subpart-C route used in S006.
Current Appendix J HTML and direct assets in S009–S010 Prose readable; equation images returned as unreadable placeholders Legal APR hold retained. No memory-based reconstruction represented as an official equation read.
Official 2025 Appendix J PDF, S011 Extracted prose available; equation pages not readable as equations Historical prose backup only; not a complete appendix read.
PDF screenshot attempts, zero-based indices 2 and 3 Returned placeholders rather than inspectable image content No visual-inspection claim.
GovInfo HTML backup: https://www.govinfo.gov/content/pkg/CFR-2025-title12-vol9/html/CFR-2025-title12-vol9-part1026-appJ.htm Inaccessible Did not close legal-method gap.
FDIC body, S014 403 Search discovery only; no substantive reliance.
Search results and regulation index Used to discover relevant primary pages and versions Snippets/index entries were not substituted for operative body reads.
Long multi-page retrievals Some outputs were truncated Only visible content was treated as read; relevant §18 material was recovered in subsequent targeted reads.
Prior research or other chats None supplied or used No reused foundation, unseen review, or independent corroboration claimed.

9. Explicit self-check and remaining gaps

Self-check

Check Result Limit
E01 denominator arithmetic 365, 360, and separately stipulated 366 calculations recomputed; end-rounding and daily-rounding results distinguished Does not select a lawful denominator or posting policy
E02 row conservation Each row satisfies opening + posted interest - cash payment = closing Stated monthly cent-posting model only
E02 lifetime conservation Principal paid $10,000; interest $661.86; cash $10,661.86; ending principal exactly $0.00 Not a daily-accrual schedule
E03 zero-rate handling 11*833.33 + 833.37 = 10000; interest zero; ending balance zero Fees assumed absent
E04 controlled comparison Same original parameters; extra $2,000 included in cash paid; final $494.88; ending balance zero Allocation/prepayment permission assumed
E04 savings Interest difference and cash difference both equal $170.57 No penalty, rebate, or other charge included
E05 cash accounting Included, excluded, separately paid, and withheld structures distinguished; no double-counted fee Actual classification unresolved
E05 numerical solution Opposite-sign starting brackets and small evaluated present-value residuals checked Not a validated legal APR engine or full software test suite
E06 accounting Both branches preserve original balance + new interest - cash paid = remaining accounting balance Capitalization permission unresolved
Citation/read integrity Primary body reads, compilation dates, failed access, historical sources, and unread images separated No complete effective-history audit or independent review
Scope control No borrower/provider-status/account/case investigation; no fees operationally approved; no publication or files Reference research only
Acceptance status This is a self-check by the same assistant No independent review, parent A004 acceptance, calculator acceptance, or publication acceptance

Remaining research packets

The parent A004 dimensions remain open. The following packets preserve their scope without claiming they were completed here.

Further packet Remaining content
Complete compound interest and capitalization Lawful capitalization events, timing, balance composition, compounding frequency, interest-on-interest restrictions, and contractual conditions
Open-end credit and cards Daily periodic rates, balance methods, grace periods, minimum payments, allocation, and negative-amortization law
Variable and penalty rates Reset mechanics, index/margin/caps, payment changes, penalty-rate conditions, and disclosure requirements
Deferred interest Conditional waivers, retroactive accrual, promotional timing, and product-specific rules
Late and collection costs Fee authorization, classification, allocation, interest on charges, collection costs, and jurisdictional restrictions
Loan and jurisdiction-specific rules Mortgage, auto, student, payday, BNPL, commercial, tribal, country, state, and local law, plus individual-contract issues in an appropriately authorized scope
Complete legal APR methods Readable full Appendix J equations; irregular/odd-day periods; multiple advances; balloons; United States Rule implementation; applicable official examples and complete method verification
Prepayment and rebates Rights, penalties, rebates, precomputed/add-on structures, Rule-of-78s restrictions, and contractual application
Tool validation and error handling Independently specified test cases, precision policies, malformed inputs, irregular dates, root failures, and version-controlled validation—none accepted by this pass
Bankruptcy, tax, settlement, and credit intersections Separate substantive authority and factual boundaries; no settlement-fee ratios, tax outcomes, or credit promises inferred here

The immediate unresolved item for this pass is narrowly defined: recover and read the complete relevant official Appendix J equation content before converting E05 from conditional numerical finance mathematics into a legally evaluated APR calculation. Actual contract application would additionally require the permitted balance, accrual, allocation, fee, timing, and prepayment terms identified above.

END R004 PASS-01
Every captured table

Captured cells with original header handling and explicitly labeled bounded correction overlays. Downloaded JSON retains original cells. Tables may contain source limitations, historical examples and identified corrections; the complete reading supplies context.

Read the evidence with its boundaries. These are saved research components, including revisions. A scoped coordinator review checks selected evidence; it does not certify every claim, a complete jurisdiction, current law or individual applicability. Dates and access limits remain attached to the records.

How to read the research →

Captured table 01

Quantity · Meaning in this investigation · Important boundary · 10 data rows

QuantityMeaning in this investigationImportant boundary
Principal balanceThe model’s outstanding interest-bearing principal, denoted B.It is not automatically the cash the consumer received or the Regulation Z amount financed. Whether financed charges or capitalized interest belong in an actual interest-bearing balance requires applicable terms and law. C006, C020–C021.
Interest rate / note rateThe rate used under the stipulated accrual convention. For E02, 12% nominal annually is expressly defined as 1% per model month.A stated annual rate does not establish its denominator, compounding convention, fee treatment, or legally disclosed APR. C007, C038.
Finance chargeThe legally classified dollar cost of consumer credit under TILA and Regulation Z.It can include interest and certain fees, but not every charge or every upfront payment. Classification requires the applicable inclusion and exclusion provisions. C008–C018.
Amount financedA disclosure measure of credit provided to the consumer or on the consumer’s behalf, calculated under §1026.18(b).It can differ from the note’s face amount, principal balance, gross disbursement, and net cash received. C019–C021.
PaymentA cash payment at a specified time. A disclosed payment schedule states the number, amounts, and timing of scheduled payments.Its allocation among interest, principal, fees, and other items is not established merely by knowing the payment amount. C022.
Total of paymentsUnder the relevant Regulation Z commentary, the sum of the payments disclosed in the repayment schedule.It is not invariably every dollar paid at origination and afterward. A prepaid finance charge is not separately listed as a repayment-schedule payment. C022–C023.
Total interestThe sum of interest accrued in a defined model and period.It differs from finance charge when other included charges exist; accrued interest also differs from interest actually paid when arrears remain. C024, E06.
Legal APRThe annual percentage rate determined under the applicable TILA/Regulation Z method, amounts, timing rules, and accuracy provisions.It is not generally interchangeable with the note rate, an effective annual rate, or any software-produced IRR. C025–C030.
Effective annual yield/rateHere, a mathematical annual equivalent: y = (1 + r)^m - 1 for m identical compounding periods per year.This is a mathematical convention, not a claim that this is the required closed-end APR disclosure or that unpaid loan interest may legally compound. C031.
Numerical IRR estimateA numerical rate equating specified advances or net proceeds with discounted specified payments.Its legal significance depends on correct inputs and the legally applicable calculation convention. Numerical convergence alone does not establish compliance. C032.

Captured table 02

Example · Hypothetical question · Principal result · 6 data rows

ExampleHypothetical questionPrincipal resultStatus
E01Same principal/rate, 30 days, alternative denominators$98.63 on 365; $100.00 on 360; $1.37 rounded differenceArithmetic answered; actual denominator and rounding authority held
E02Positive-rate fixed monthly amortization$888.49 ordinary installment; $888.47 final; $661.86 interestComplete stated cent-posting schedule
E03Same principal and term, zero interestEleven payments of $833.33 and one of $833.37Complete zero-rate handling
E04E02 plus $2,000 principal after installment 3Final $494.88 at month 10; $491.29 interest; $170.57 savedControlled comparison; real allocation/prepayment rights held
E05$300 upfront fee and cash-flow rate comparisonConditional amount financed $9,700; numerical annualized rate about 17.8250%Legal APR held; numerical estimate and classification branches supplied
E06Payment below accruing interestAfter three $5 payments: $1,015.00 without capitalization; $1,015.15 with stipulated capitalizationSeparate mathematical branches; capitalization permission held

Captured table 03

Assumed denominator · Calculation before rounding · Interest rounded once at the end · 3 data rows

Assumed denominatorCalculation before roundingInterest rounded once at the end
36510000 * 0.12 * 30 / 365 = 98.6301369863$98.63
36010000 * 0.12 * 30 / 360 = 100.0000000000$100.00
366, only as a separately stipulated leap-year branch10000 * 0.12 * 30 / 366 = 98.3606557377$98.36

Captured table 04

Denominator · Round only the final period charge · Round each daily amount to cents, then sum 30 days · 2 data rows

DenominatorRound only the final period chargeRound each daily amount to cents, then sum 30 daysDifference
365$98.63$3.29 * 30 = $98.70Daily cent posting is $0.07 higher
360$100.00$3.33 * 30 = $99.90Daily cent posting is $0.10 lower

Captured table 05

Month · Opening principal · Posted interest · 13 data rows

MonthOpening principalPosted interestCash paymentPrincipal paidEnding principal
1$10,000.00$100.00$888.49$788.49$9,211.51
29,211.5192.12888.49796.378,415.14
38,415.1484.15888.49804.347,610.80
47,610.8076.11888.49812.386,798.42
56,798.4267.98888.49820.515,977.91
65,977.9159.78888.49828.715,149.20
75,149.2051.49888.49837.004,312.20
84,312.2043.12888.49845.373,466.83
93,466.8334.67888.49853.822,613.01
102,613.0126.13888.49862.361,750.65
111,750.6517.51888.49870.98879.67
12879.678.80888.47879.670.00
Total—$661.86$10,661.86$10,000.00$0.00

Captured table 06

Month or group · Payment · Interest · 5 data rows

Month or groupPaymentInterestResult
Month 1$833.33$0.00Ending principal $9,166.67
Month 2$833.33$0.00Ending principal $8,333.34
Months 1–11 combined$9,166.63$0.00Principal remaining $833.37
Month 12$833.37$0.00Ending principal $0.00
Total$10,000.00$0.00Principal repaid $10,000.00

Captured table 07

Month · Opening principal · Interest · 11 data rows

MonthOpening principalInterestRegular/final paymentExtra principalTotal principal paidEnding principal
1$10,000.00$100.00$888.49$0.00$788.49$9,211.51
29,211.5192.12888.490.00796.378,415.14
38,415.1484.15888.492,000.002,804.345,610.80
45,610.8056.11888.490.00832.384,778.42
54,778.4247.78888.490.00840.713,937.71
63,937.7139.38888.490.00849.113,088.60
73,088.6030.89888.490.00857.602,231.00
82,231.0022.31888.490.00866.181,364.82
91,364.8213.65888.490.00874.84489.98
10489.984.90494.880.00489.980.00
Total—$491.29$8,491.29$2,000.00$10,000.00$0.00

Captured table 08

Item · E02 scheduled path · E04 extra-principal path · 9 data rows

ItemE02 scheduled pathE04 extra-principal pathDifference
Original principal$10,000.00$10,000.00$0.00
Nominal annual / monthly rate12% / 1%12% / 1%None
Posting and allocation conventionSame defined modelSame defined modelNone
Extra principal$0.00$2,000.00 at month 3Earlier principal repayment
Final payment$888.47 at month 12$494.88 at month 10Earlier mathematical payoff
Total interest$661.86$491.29$170.57 saved
Total cash paid, including extra principal$10,661.86$10,491.29$170.57 less
Principal repaid$10,000.00$10,000.00$0.00
Ending balance$0.00$0.00$0.00

Captured table 09

Measure · No-fee reference · $300 included prepaid finance charge · 10 data rows

MeasureNo-fee reference$300 included prepaid finance charge$300 legally excluded, paid separately
Interest-bearing note principal$10,000.00$10,000.00$10,000.00
Gross cash received at t = 0$10,000.00$10,000.00$10,000.00
Separate t = 0 fee payment$0.00$300.00$300.00
Net t = 0 cash position$10,000.00$9,700.00$9,700.00
Conditional amount financed$10,000.00$9,700.00$10,000.00
Scheduled interest$661.86$661.86$661.86
Conditional finance charge$661.86$961.86$661.86
Scheduled total of payments$10,661.86$10,661.86$10,661.86
All consumer cash outflows, including separate origination fee$10,661.86$10,961.86$10,961.86
Legal APR calculated in this reportHeldHeldHeld

Captured table 10

Comparison input · Monthly numerical root q · Nominal annualized numerical rate · 2 data rows

Comparison inputMonthly numerical root qNominal annualized numerical rateEffective annualized numerical rate
V = $10,0000.01000009552360758812.0001146283%12.6826309005%
V = $9,7000.01485420229769551817.8250427572%19.3558891893%

Captured table 11

Provision · Rule relevant to this bounded comparison · Limitation · 4 data rows

ProvisionRule relevant to this bounded comparisonLimitation
§1026.22(a)(2)Regular-transaction APR tolerance: ±0.125 percentage point, or 12.5 basis pointsNot a relative 0.125% error; does not cure incorrect fee classification
§1026.22(a)(3)Specified irregular transactions: ±0.25 percentage pointAn irregular first period or first/final payment alone is excluded from that irregularity definition
§1026.18(d)(2)For the non-real-property/non-dwelling category addressed there: finance-charge tolerance is ±$5 when amount financed is $1,000 or less and ±$10 when it exceeds $1,000A dollar finance-charge tolerance is not an APR tolerance or charging authorization
Appendix J(b)(9)(ii), readable proseSufficient numerical precision and iteration are required to obtain the stated rounded resultThe unreadable operative equations prevent legal-method verification here

Captured table 12

Month · Opening principal · New interest · 3 data rows

MonthOpening principalNew interestCash payment to interestEnding principalEnding unpaid interest UPrincipal + unpaid interest
1$1,000.00$10.00$5.00$1,000.00$5.00$1,005.00
21,000.0010.005.001,000.0010.001,010.00
31,000.0010.005.001,000.0015.001,015.00

Captured table 13

Month · Opening interest-bearing balance · New posted interest · 3 data rows

MonthOpening interest-bearing balanceNew posted interestCash paymentInterest capitalized after paymentEnding interest-bearing balance
1$1,000.00$10.00$5.00$5.00$1,005.00
21,005.0010.055.005.051,010.05
31,010.0510.105.005.101,015.15

Captured table 14

Failure or gateway · What fails or remains uncertain · Required bounded correction · 10 data rows

Failure or gatewayWhat fails or remains uncertainRequired bounded correctionRelated claims/examples
Monthly-versus-daily mismatchA 1% monthly charge on $10,000 is $100; 30 days at 12%/365 is about $98.63. Monthly payment frequency does not make them identical.Select the actual permitted accrual convention and keep it throughout the schedule.C033–C040; E01–E02
Irregular payment date or amountThe equal-period annuity formula does not determine the effect of an early, late, partial, or irregularly timed payment.Establish credited date, endpoint rule, allocation, and applicable legal APR timing convention; then rebuild the cash flows.C035, C039, C056
Variable rateA single constant r cannot represent an unspecified future rate path.Obtain the published contractual reset/index/margin/cap and payment-adjustment terms; investigate the applicable disclosure rules separately.C038–C040; S007 §18(f)
Balloon or residual balanceA schedule ending with B_n > 0 has not amortized the balance to zero.Identify the maturity payment or other authorized residual treatment; do not silently write the remainder off.C042
Late feeA separate fee is neither automatically interest nor automatically a lawful charge. Exclusion from finance charge does not erase cash cost.Read the actual charge trigger, amount, applicable law, and §4(c)(2) classification conditions. Keep the fee separate from ordinary interest.C018, C035
Insufficient paymentUsing payment - interest as a negative principal reduction without explanation hides whether unpaid interest remains separate or is capitalized.Track principal and unpaid interest separately unless a permitted capitalization rule is established.C036; E06
Precomputed/add-on interest or Rule of 78sE04’s declining-balance savings cannot be transferred mechanically.Separate packet for complete current rebate/prepayment authorities, including examination of 15 U.S.C. §1615, relevant jurisdictional law, and published contract terms. No Rule-of-78s result is asserted here.C019, C044
Disputed or uncertain feeA numerical rate cannot resolve whether a fee belongs in finance charge.Preserve included/excluded branches until the relevant §4 test and transaction facts are established.C008–C021; E05
Consumer versus business creditPersonal/family/household purpose and applicable exemptions are threshold questions. A product label is insufficient.Apply the complete relevant coverage and purpose provisions to an authorized factual setting; no borrower determination here.C001–C003
Secured versus unsecured creditReal-property/dwelling transactions can have different disclosure provisions and fee rules.Identify the security and product gateway before choosing the disclosure framework. Mortgage-specialized analysis remains outside this pass.C004, C016

Captured table 15

Source ID · Issuer/title and complete literal URL(s) · Exact relevant location · 14 data rows

Source IDIssuer/title and complete literal URL(s)Exact relevant locationVersion, effective trigger, or statusActual check date and fresh read extentJurisdiction and contract limits
R004-P1-S001U.S. House, U.S. Code, 15 U.S.C. §1605 — Determination of finance charge. https://uscode.house.gov/us/usc/119-121/t15/s1605/§1605(a)–(f), especially (a) general definition and third-party closing charges; (b)–(e) conditional exclusionsBody displayed currency through P.L. 119-121, October 9, 2026. Source credits include enactment May 29, 1968 and later amendments; effective-date history was not independently reconstructed.2026-10-27 PDT. Fresh: operative (a)–(f) and selected notes. Recovered after failed alternate routes.Federal TILA classification; does not establish coverage or charging authority for a particular loan. uscode.house.gov
R004-P1-S002U.S. House, U.S. Code, 15 U.S.C. §1606 — Determination of annual percentage rate. https://uscode.house.gov/us/usc/119-121/t15/s1606/§1606(a)–(e), especially (a)(1) and (c)Body displayed currency through P.L. 119-121, October 9, 2026. Original 1968 provision with later amendments; no independent effective-history audit.2026-10-27 PDT. Fresh: complete operative (a)–(e).Statutory APR computation authority; its computational allocation is not a universal servicing waterfall. uscode.house.gov
R004-P1-S003U.S. House, U.S. Code, 15 U.S.C. §1638 — Requirements for certain mortgages and other consumer credit transactions. https://uscode.house.gov/us/usc/119-118/t15/s1638/Relevant complete §1638(a)(1)–(12)Page body stated currency through P.L. 119-120, October 7, 2026, despite the different number in its URL. That displayed body currency is recorded; no inference from the URL alone.2026-10-27 PDT. Fresh: relevant (a)(1)–(12); later mortgage material encountered but not fully investigated.Federal closed-end disclosures; mortgage-specialized provisions excluded from full analysis. uscode.house.gov
R004-P1-S004CFPB, Regulation Z index; §§1026.1, .2, .3 and embedded official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/; https://www.consumerfinance.gov/rules-policy/regulations/1026/1/; https://www.consumerfinance.gov/rules-policy/regulations/1026/2/; https://www.consumerfinance.gov/rules-policy/regulations/1026/3/§1(a)–(c); §2(a)(10)–(14), (20)–(23), (b); relevant definition comments; §3(a) and comments, selected §3(b)Current-page designation. Index: Part 1026 most recently amended April 8, 2026. This is part-wide metadata, not individual-section effective dating.2026-10-27 PDT. Fresh: identified operative paragraphs and relevant comments; index read for metadata/discovery, not as substantive body evidence.Consumer/closed-end/creditor/exemption gateway only; no transaction-specific coverage determination. Consumer Financial Protection Bureau +3
R004-P1-S005CFPB and eCFR, §1026.4 — Finance charge; official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/4/; https://www.consumerfinance.gov/rules-policy/regulations/1026/interp-4/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-A/section-1026.4Relevant complete rules in (a)–(f); comments on comparable cash charges, application fees, third parties, insurance, security charges, and late chargesCFPB current text; eCFR Title 12 displayed through October 23, 2026. No claim that date is this section’s amendment date.2026-10-27 PDT. Fresh: CFPB operative clauses and relevant embedded commentary; separate interpretation page’s opening definition; eCFR visible body through (d)(3)(ii). Unrelated open-end material was not a separate investigation.Conditional federal classification rules. Real-estate and mortgage exceptions are not generalized to unsecured credit. ecfr.gov +2
R004-P1-S006CFPB and eCFR, §1026.17 — General disclosure requirements; official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/17/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.17§17(c)(1)–(3); comments 17(c)(1)-1–2, 17(c)(2)(i)-3, 17(c)(3)-1–2; selected (c)(4) materialCurrent agency text; eCFR displayed through October 23, 2026. Disclosure inputs reflect the legal obligation.2026-10-27 PDT. Fresh: complete relevant clauses/comments above; odd-first-period material only to identify the gateway, not apply the full method.Disclosure assumptions are not universal accrual, receipt-date, capitalization, or holiday-servicing rules. Consumer Financial Protection Bureau +2
R004-P1-S007CFPB and eCFR, §1026.18 — Content of disclosures; official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/18/; https://www.consumerfinance.gov/rules-policy/regulations/1026/interp-18/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.18Introductory scope; (b), (c), (d), (e), (g), (h), (k), (l), (p); relevant comments including 18(b)(3)-1–2, 18(g)-1, -4, 18(h)-2Current agency text; eCFR displayed through October 23, 2026. Underlying section-specific effective history not fully audited.2026-10-27 PDT. Fresh: relevant complete rules and associated comments; §18(c)(1)–(3) and its relevant itemization material recovered in fresh reads. Mortgage tables not fully investigated.Examples use the non-mortgage framework. Prepayment disclosures do not resolve substantive prepayment rights. ecfr.gov +3
R004-P1-S008CFPB and eCFR, §1026.22 — Determination of APR; official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/22/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.22Entire operative section and embedded commentary; especially (a)(1)–(3), (b)(2), comments 22(a)(1)-1–5Current text; eCFR displayed through October 23, 2026. Section history cited 76 FR 79772, Dec. 22, 2011; 78 FR 80112, Dec. 31, 2013; 80 FR 80229, Dec. 24, 2015. Underlying rulemaking effective dates not separately read.2026-10-27 PDT. Fresh: full section and embedded comments. Mortgage tolerances and add-on shortcut provisions were read but not applied.Provides APR methods/accuracy framework; does not validate the present numerical routine or authorize contract charges. Consumer Financial Protection Bureau +1
R004-P1-S009CFPB/eCFR, Appendix J — APR computations for closed-end credit; official interpretation. https://www.consumerfinance.gov/rules-policy/regulations/1026/j/; https://www.consumerfinance.gov/rules-policy/regulations/1026/interp-j/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/appendix-Appendix%20J%20to%20Part%201026Readable (a), (b)(1)–(6), textual (b)(9), example headings/introductions; complete official comment J-1–2Linked from current Regulation Z. The current display did not make all equation assets readable.2026-10-27 PDT. Fresh partial body: prose read; eCFR extraction stopped before the needed equation content. Not a complete operative-equation read.Supports framework only. Legal calculation held because symbols/equations/examples in (b)(7)–(9) and relevant (c) panels were not readable. Consumer Financial Protection Bureau +3
R004-P1-S010CFPB, Appendix J equation/image assets, same underlying document as S009. https://files.consumerfinance.gov/eregulations/ER22DE11.062-1.png; https://files.consumerfinance.gov/eregulations/ER22DE11.062-2.png; https://files.consumerfinance.gov/eregulations/ER22DE11.063-1.png; https://files.consumerfinance.gov/eregulations/ER22DE11.063-2.png; https://files.consumerfinance.gov/eregulations/ER22DE11.064-1.png; https://files.consumerfinance.gov/eregulations/ER22DE11.066-1.pngSymbol panels, general equation, iteration example, regular-payment example, odd-final-payment exampleAssets linked by current page. Filename dates are not treated as independently verified adoption/effective dates.2026-10-27 PDT. Attempted: responses were image placeholders without readable image contents. No equation read or visual verification claimed.Failed recovery, not corroborating substantive evidence.
R004-P1-S011U.S. Government Publishing Office, 2025 CFR, Title 12, volume 9, Appendix J. https://www.govinfo.gov/content/pkg/CFR-2025-title12-vol9/pdf/CFR-2025-title12-vol9-part1026-appJ.pdfPrinted pages 436–447; zero-based PDF indices 0–11January 1, 2025 edition, historical backup rather than proof of October 2026 currency2026-10-27 PDT. Fresh extracted text: substantive prose on printed pp. 436–437, indices 0–1. Later pages supplied headers/graphic markers without readable equations. Screenshot attempts at indices 2–3 did not yield inspectable content. No visual inspection claimed.Backup failed to close the Appendix J equation gap. govinfo.gov +1
R004-P1-S012CFPB, Withdrawn guidance. https://www.consumerfinance.gov/compliance/guidance/withdrawn-guidance/Register entries and last-modified metadataDisplayed last modified July 22, 2026, 12:12 PM EDT2026-10-27 PDT. Fresh: register body and metadata read.No CFPB circular, bulletin, or advisory was relied on. Withdrawal register not treated as repeal of retrieved statutes, regulations, or Supplement I. Consumer Financial Protection Bureau +1
R004-P1-S013Bank of America, public generic Explanation of Simple Interest Calculation. https://secure.bankofamerica.com/content/pdf/en_us/Explanation_of_Simple_Interest_Calculation.pdfOne unnumbered printed page; zero-based PDF index 0; steps 2–3Document marked Rev. 12/17/20102026-10-27 PDT. Fresh: complete extracted text of the one-page document. Text read, not visual inspection.Establishes only its stated 365/366 convention. Not a current-policy finding, consumer agreement, or universal legal rule. secure.bankofamerica.com
R004-P1-S014FDIC, Consumer Compliance Examination Manual, TILA section. https://www.fdic.gov/consumer-compliance-examination-manual/v-1-truth-lending-act-tilaSearch discovery onlyBody access returned 4032026-10-27 PDT. Failed body access: no substantive body relianceSearch snippet is not evidence of a complete operative read. Current Regulation Z commentary supplied the relied-on denominator discussion instead.
Source links captured in this table

Captured table 16

Claim ID · Area · Atomic assertion · 24 data rows

Claim IDAreaAtomic assertionSource and exact pinpointAssumptions, conditions, exclusions, and status
R004-P1-C001A004Closed-end credit is credit other than open-end credit; consumer credit concerns primarily personal, family, or household purposes.S004, §2(a)(10), (12)Definition established; no transaction-specific purpose finding.
R004-P1-C002A004Zero interest alone does not exclude coverage; written repayment in more than four installments is relevant under the general coverage rule.S004, §1(c)(1)Other coverage conditions and exemptions still matter; E03 assumes the relevant consumer setting.
R004-P1-C003A004Business/commercial/agricultural purpose and organizational-credit provisions are coverage gateways; mixed-purpose analysis cannot be replaced by a label.S004, §3(a), comments 3(a)-1–10Gateway answered; actual classification unresolved and outside this pass.
R004-P1-C004A004§18 excludes mortgage transactions subject to §19(e) and (f) from its general disclosure framework; security can change applicable provisions.S007, §18 introductory paragraph; §18(s) gatewayExamples assume the non-mortgage setting; no mortgage-specialized conclusion.
R004-P1-C005A004Disclosures reflect the legal obligation; the disclosure calculation is not independent permission to impose a charge.S004, §1(b); S006, §17(c)(1), comments 1–2Contract and applicable law remain required.
R004-P1-C006A004B is the model’s interest-bearing principal, kept distinct from unpaid accrued interest U.Defined accounting model; S004, §2(b)(3); S006, §17(c)(1)No universal statutory definition of every contract’s principal balance is asserted.
R004-P1-C007A004A periodic rate applies to a specified period; an annual note rate requires its stated conversion/accrual convention.S004, §2(a)(21), comment 1Decimal per period in calculations; fee-inclusive APR is not substituted for the note rate.
R004-P1-C008A004Finance charge is the legally classified dollar cost of consumer credit, including direct or indirect qualifying charges.S001, §1605(a); S005, §4(a)Coverage and exclusions required.
R004-P1-C009A004Interest and loan fees are listed finance-charge categories, subject to the express exclusions.S005, §4(b)(1), (3), introductory qualification to (b)A fee label does not bypass (c)–(e).
R004-P1-C010A004A charge of a type payable in a comparable cash transaction is excluded; a credit-specific excess requires separate treatment.S001, §1605(a); S005, §4(a), comment 4(a)-1Requires a genuinely comparable cash-charge basis.
R004-P1-C011A004Application fees charged to all applicants, whether or not credit is extended, are excluded.S005, §4(c)(1), comment 4(c)(1)-1E05’s excluded branch is conditional on satisfying this test, not merely naming the fee “application.”
R004-P1-C012A004Third-party charges can be included when use is required or to the extent retained by the creditor, unless otherwise excluded.S005, §4(a)(1)(i)–(ii)Consumer choice of provider does not by itself settle inclusion.
R004-P1-C013A004Closing-agent charges have a separate test concerning required services, required charges, or retained portions.S001, §1605(a); S005, §4(a)(2)Not a universal rule for all third-party fees; mortgage-broker special rule not generalized.
R004-P1-C014A004Specified voluntary credit-insurance premiums can be excluded only with the required optionality, written cost/term disclosures, and affirmative request.S001, §1605(b); S005, §4(d)(1)(i)–(iii)Optionality alone is insufficient. No insurance product is evaluated.
R004-P1-C015A004Specified property-insurance premiums can qualify for exclusion under consumer-choice and disclosure conditions, even where insurance is required.S001, §1605(c); S005, §4(d)(2)(i)–(ii)Includes the stated conditions concerning single-interest insurance/subrogation where relevant; no universal “mandatory fee” rule.
R004-P1-C016A004The listed bona fide, reasonable real-estate-related fee exclusion has a defined real-property/residential-mortgage scope.S001, §1605(e); S005, §4(c)(7)(i)–(v)Not transferred to all unsecured loans.
R004-P1-C017A004Certain security-related public-official charges and substitute insurance require the specified itemization, disclosure, and statutory conditions for exclusion.S001, §1605(d); S005, §4(e)No blanket exclusion for every “government” or third-party charge.
R004-P1-C018A004Charges for actual unanticipated late payment/default can be excluded from finance charge under §4(c)(2).S005, §4(c)(2); S007, §18(l) and relevant commentaryExclusion is not authorization, waiver of cash cost, or proof that a disputed fee qualifies.
R004-P1-C019A004A prepaid finance charge includes qualifying charges paid separately before/at consummation or withheld from proceeds; precomputed interest is not automatically prepaid merely because precomputed.S004, §2(a)(23), comments 1–3Classification as finance charge must first be established.
R004-P1-C020A004Amount financed follows §18(b)’s calculation and must avoid double subtraction of included finance charges.S003, §1638(a)(2); S007, §18(b)(1)–(3), comment 18(b)(3)-1Distinguish the regulatory principal-loan input from the note face amount.
R004-P1-C021A004Amount financed need not equal cash delivered directly to the consumer.S007, §18(c)(1)(i)–(iv)Amounts credited or paid on the consumer’s behalf may differ from direct proceeds.
R004-P1-C022A004The payment schedule addresses number, amounts, and timing; prepaid finance charges are not separately inserted as schedule payments.S007, §18(g), comments 18(g)-1, -4Other permitted components can appear in scheduled payments; allocation remains a separate question.
R004-P1-C023A004Total of payments is the sum of disclosed schedule payments; amount financed + finance charge is valid for the simple E05 streams, not asserted as every possible cash-flow identity.S003, §1638(a)(5); S007, comment 18(h)-2 and 18(g)-1Optional or other schedule components and separate upfront cash require careful reconciliation.
R004-P1-C024A004Total interest is the sum of modeled interest accruals; it need not equal finance charge or interest paid.Defined arithmetic; S005, §4(b); E02, E05, E06Period and accrual/payment basis must be stated.

Captured table 17

Claim ID · Area · Atomic assertion · 20 data rows

Claim IDAreaAtomic assertionSource and exact pinpointAssumptions, conditions, exclusions, and status
R004-P1-C025A004Closed-end legal APR depends on amount and timing under the applicable actuarial or United States Rule framework.S002, §1606(a); S008, §22(a)(1)Legal method identified; E05 legal result held.
R004-P1-C026A004Appendix J describes APR as a nominal annual rate based on the unit-period rate and number of unit periods per year.S009, Appendix J(b)(1), (b)(4)–(5)This legal annualization is distinct from (1+r)^m - 1; full equation implementation unread.
R004-P1-C027A004The general regular-transaction APR accuracy allowance is ±1/8 percentage point.S008, §22(a)(2)0.125 percentage point, not 0.125% relative error.
R004-P1-C028A004The specified irregular-transaction allowance is ±1/4 percentage point; an irregular first period or first/final payment alone does not trigger that definition.S008, §22(a)(3), relevant commentaryE02’s final cent adjustment alone is not a basis to assume irregular tolerance.
R004-P1-C029A004§18(d)(2)’s finance-charge dollar tolerances differ from APR percentage-point tolerances.S007, §18(d)(2)Non-real-property/non-dwelling category: ±$5 at amount financed ≤$1,000; ±$10 above $1,000.
R004-P1-C030A004The original amortization method alone does not determine reportable APR.S002, §1606(a); S005, §4; S007, §18(b); S008, §22(a)(1)Also requires correct classification, amount financed, dates, payments, and legal calculation method.
R004-P1-C031A004A constant-period mathematical effective annual rate is (1+r)^m - 1.Derived by multiplying one-period growth factors m timesCompounding/equivalent-rate assumption; not charging authority or a legally labeled APR.
R004-P1-C032A004A numerical IRR is a root of a specified discounted cash-flow equation; convergence alone does not verify legal APR compliance.Derived present-value identity; S008, §22(b)(2), comment 22(a)(1)-5E05 is expressly an approximate numerical estimate.
R004-P1-C033A004Constant-balance simple accrual is B*a*d/D; segmented accrual sums such terms under the same stated model.S013, steps 2–3; algebraic extension stated in §2.1Dollar balance, annual decimal rate, counted days, stated denominator; actual application held.
R004-P1-C034A004Identified sources discuss 365/360 distinctions and a stated 365/366 convention; none establishes one universal convention.S006, comment 17(c)(3)-1(ii); S004, comment 2(a)(21)-1; S013, step 2Complete Actual/Actual and 30/360 conventions not established.
R004-P1-C035A004Actual payment-crediting dates, inclusivity, partial-payment effects, and due-date changes require the legal obligation and applicable rules.S006, §17(c)(1), comments 1–2; §17(c)(2)(i), comment 3No receipt/posting/value-date or holiday rule invented.
R004-P1-C036A004Accrued unpaid interest and capitalized interest are separate accounting states; APR computational descriptions do not grant capitalization authority.S008, comments 22(a)(1)-2–3; S009, Appendix J(a)(2)–(3); E06Real capitalization permission unresolved.
R004-P1-C037A004Ledger precision, posted-cent rounding, and cash-payment rounding can produce different totals and final installments.Derived E01/E02 calculations; S006, comment 17(c)(3)-1(i)The chosen half-up posting rule is hypothetical, not a universal legal requirement.
R004-P1-C038A004r = annual nominal rate / 12 is used only because the monthly convention defines that relationship.Model definition; S004, §2(a)(21); algebraic effective-rate conversionNot substituted for daily accrual or fee-inclusive APR.
R004-P1-C039A004Under the equal-period, interest-first, no-fee model, B_k = B_(k-1)*(1+r) - M.Derived balance conservation in §2.2Requires adequate payment or separate unpaid-interest treatment.
R004-P1-C040A004For r>0, equal end-period payments amortizing P over n periods satisfy M=P*r/[1-(1+r)^(-n)].Derivation in §2.2 from C039Fixed rate, equal periods, full amortization, no omitted charges.
R004-P1-C041A004At zero rate, use M=P/n, then explicitly handle cent rounding in the final installment.Derived E03No division by zero.
R004-P1-C042A004A positive terminal balance requires explicit residual/balloon treatment; it is not a zero ending balance.Balance identity C039; E02/E03 final-payment checksActual maturity and residual terms required.
R004-P1-C043A004Extra principal reduces later model interest only after application to principal; the calculation does not establish due-date advancement or recast rights.Derived E04; S006, §17(c)(1); S007, §18(k), (p)Immediate extra-principal application and no penalty are assumptions.
R004-P1-C044A004Declining-balance and precomputed-charge prepayment analyses require separate treatment; E04 savings cannot be mechanically transferred.S007, §18(k)(1)–(2); S004, comment 2(a)(23)-3Full rebate, penalty, add-on, and Rule-of-78s law remains held.

Captured table 18

Claim ID · Area · Atomic assertion · 12 data rows

Claim IDAreaAtomic assertionSource and exact pinpointAssumptions, conditions, exclusions, and status
R004-P1-C045A004E01’s 365/360 end-rounded charges are $98.63/$100.00, with a $1.37 difference.E01 displayed inputs, equations, and rounding comparisonDerived arithmetic; denominator application not adjudicated.
R004-P1-C046A004E02’s posted-cent schedule pays $10,000 principal and $661.86 interest, ending at exactly zero after an $888.47 final payment.E02 complete 12-row scheduleVerified within stated monthly and rounding model.
R004-P1-C047A004E03’s eleven $833.33 payments plus $833.37 repay exactly $10,000 with no interest.E03 arithmeticZero rate and no fees only.
R004-P1-C048A004E04’s controlled extra-principal path produces $491.29 interest and saves $170.57 relative to E02.E04 complete 10-row schedule and comparisonSame original principal/rate/convention; allocation and no-penalty assumptions explicit.
R004-P1-C049A004E05’s included-fee branch yields conditional amount financed $9,700 and finance charge $961.86 while preserving the $10,000 note balance.S007, comment 18(b)(3)-1; E05 cash tableSeparate-at-origination fee; no double counting; legal classification conditional.
R004-P1-C050A004E05’s numerical annualized roots are approximately 12.0001146283% for V=10000 and 17.8250427572% for V=9700.E05 equation, bracket, iterations, residualsDecimal monthly roots; not legal APR results.
R004-P1-C051A004E05’s corresponding effective annualized numerical rates are approximately 12.6826309005% and 19.3558891893%.Derived from C050 using 100*((1+q)^12-1)Mathematical annual equivalence only.
R004-P1-C052A004E06 without capitalization ends with $1,000 principal plus $15 unpaid interest after $15 cash paid.E06 Branch AInterest accrues only on original principal; three-month observation.
R004-P1-C053A004E06 with stipulated monthly capitalization ends at $1,015.15 after $30.15 new interest and $15 cash paid.E06 Branch BCent posting; capitalization legality and contract permission not established.
R004-P1-C054A004The CFPB Withdrawn Guidance register was freshly checked; no circular, bulletin, or advisory supports this report’s substantive conclusions.S012, full register and metadataWithdrawal is not treated here as alteration or repeal of the retrieved controlling texts.
R004-P1-C055A004Retrieval date and source compilation/effective dates are different; this report preserves the displayed dates and gaps.S001–S004, S006–S009, S011–S013No complete amendment-lag or section-effective-history certification.
R004-P1-C056A004Complete operative Appendix J equation content was not readable; therefore the legal APR calculation is held.S009–S011; failure log belowProse read and numerical math do not substitute for the missing legal-method read.

Captured table 19

Assigned component · Status and reason · Claim/example links · 46 data rows

Assigned componentStatus and reasonClaim/example linksExact missing authority or term; next bounded action
1 — Closed-end consumer gatewayAnswered as a gatewayC001–C004Actual creditor/transaction coverage facts absent by design; any later application requires the relevant coverage provisions and authorized facts.
1 — Principal balanceAnswered as model definition; actual balance composition unresolvedC006, C020–C021Missing interest-bearing-balance clause and lawful treatment of financed charges/capitalization; inspect a published generic contract in a later packet.
1 — Interest/note/periodic rateAnsweredC007, C038Actual annual-rate conversion and accrual clause absent; do not infer from payment frequency.
1 — Finance chargeAnswered, conditional classification frameworkC008–C018Actual fee purpose, payee, comparable-cash treatment, and exclusion facts absent.
1 — Amount financedAnsweredC019–C021; E05Actual principal-loan input, included charges, and disbursement structure needed for application.
1 — Payment and total of paymentsAnsweredC022–C023; E02–E05Actual schedule and additional components absent; do not equate total of payments with every origination cash outflow.
1 — Total interestAnsweredC024; E02, E04, E06Actual accrual period and paid-versus-accrued basis must be specified.
1 — Legal APR versus note rateAnswered conceptually; calculation heldC025–C030, C056Missing readable operative Appendix J equations and complete applicable calculation implementation.
1 — Effective annual yield and numerical IRRAnswered mathematicallyC031–C032, C050–C051No additional authority needed for stated algebra; no statutory APR equivalence asserted.
1 — Fee inclusion/exclusion and timing affect comparisonAnswered conditionallyC008–C023, C030; E05Actual classification facts and legally applicable dates required before a legal APR.
1 — Open-end, deferred-interest, mortgage-specialized full inquiryExcluded as directedC004; remaining packetsSeparate product-specific sources and methods required.
2 — Constant-balance daily formulaAnsweredC033; E01Actual rate, balance base, days, and denominator needed for application.
2 — 365 versus 360Answered as sourced distinction and hypothetical arithmeticC034–C045; E01No actual adopted denominator; next read a published generic accrual clause and applicable law.
2 — Leap-year/actual-year alternativePartialC034; E01; S013Published 365/366 statement read; complete cross-year Actual/Actual rules and current contract adoption not established.
2 — Receipt, posting, value date and endpoint inclusivityUnresolved for actual applicationC035Missing credited-date and day-inclusion clause plus applicable legal requirements; later packet must establish both.
2 — Partial payments, prepayments, and residualsAnswered as model boundariesC035, C042–C044; E04Missing partial-payment holding/application, principal-curtailment, and residual terms.
2 — Accrued versus capitalized interestAnswered mathematically; permission unresolvedC036; E06Missing capitalization event, base, timing, and applicable authorization/restriction.
2 — Ledger precision versus cash roundingAnsweredC037; E01–E03Actual posting/rounding clause or authoritative servicing rule absent.
2 — Late/extra payments and due datesAnswered as non-inferenceC035, C043Missing any contractual due-date advancement, modification, recast, or deferment provision.
3 — Positive-rate payment formula and recurrenceAnswered and derivedC039–C040; E02Formula applies only to stated constant-period model.
3 — Number and frequency of paymentsAnswered for equal monthly periodsC022, C038–C040Actual first-payment date and irregular-period terms absent; no real calendar assumed.
3 — First two allocations and last installmentAnswered with complete scheduleC046; E02No missing mathematical input for the displayed model.
3 — Rounding, balloon, residual casesAnswered as arithmetic and gatewayC037, C042; E02–E03Actual balloon/maturity and residual disposition needed beyond the model.
3 — When annual rate/12 appliesAnswered with explicit conditionC038Actual monthly conversion convention would need contractual support.
3 — Monthly versus daily separationAnsweredC033–C040; E01–E02No conversion or equivalence silently imposed.
3 — Zero rateAnswered separatelyC041, C047; E03No division by zero; final four-cent adjustment shown.
3 — Insufficient payment/negative amortization boundaryAnswered mathematically; full law deferredC036, C052–C053; E06Missing capitalization and product-specific negative-amortization/minimum-payment law.
4 — Complete actual Appendix J methodPartial; legal calculation heldC025–C030, C056; S009–S011Readable (b)(7)–(9) equation panels and applicable (c) example needed; obtain an accessible official rendering in a later packet.
4 — Actual official calculation conventionsAnswered to readable extentC026–C029Unit-period/annualization prose and tolerances read; this does not close the equation gap.
4 — Cash-flow timing/frequencyAnswered for numerical modelE05Relative times 0–12 equal model months supplied; actual legal dates/odd-day rules unresolved.
4 — Legal APR versus numerical estimateAnswered expresslyC032, C050, C056All numerical rates remain non-certified; no computed legal APR reported.
4 — Numerical convergence, tolerance, unitsAnsweredC027–C029, C050; E05Bisection and dollar residual checked; not a general calculator validation.
4 — Mandatory, optional, third-party feesAnswered as conditional testsC009–C018Actual fee facts and compliance with exclusion conditions required.
4 — Prepaid charge, net proceeds, financed principalAnswered with branchesC019–C021, C049; E05Actual separate/withheld/financed structure needed; financed-on-top version requires a new schedule.
4 — Original amortization does not determine APR aloneAnsweredC030; E05Correct legal classification and calculation method remain independent prerequisites.
5 — Same original principal/rate/contract conventionAnswered within stipulated modelC046, C048; E02/E04Both paths use identical original parameters; no unrelated-loan comparison.
5 — Specified extra principal and allocation orderAnswered as an assumptionC043, C048; E04Actual waterfall and right to immediate principal application not established.
5 — Interest saved, total cash, final partial paymentAnswered and reconciledC048; E04No missing numerical input for the displayed comparison.
5 — Prepayment penalty/rebate/rightUnresolved substantivelyC044Requires complete current federal/product/jurisdictional prepayment authority and published contractual terms.
5 — Add-on/precomputed/Rule-of-78s transferExcluded from computation; gateway preservedC019, C044Separate current-law and contract packet; no mechanical use of E04 savings.
6 — Operative clauses, exceptions, commentaryAnswered for relied-on propositions; Appendix J partialS001–S009; C056Missing equation content identified rather than filled from memory or snippets.
6 — Currentness, citation, adoption/version datesAnswered with express limitsC055; source tableCompilation lag and complete section-specific effective histories not fully closed; later targeted official amendment audit if required.
6 — Withdrawn Guidance registerAnsweredC054; S012No circular/bulletin/advisory reliance requiring further withdrawal analysis.
6 — Public contract/source limitsAnsweredS013; C034–C035Generic 2010 instruction supplies only its stated convention; no agreement or present provider-policy inference.
6 — Prohibited records/actionsObservedSession activity statement; read logNo owner-restricted records or actions undertaken; no next action required.
Delivery — Complete visible tables, self-check, remaining dimensionsAnsweredAll tables; §§8–9Self-check is not independent review; parent A004 and calculator/publication acceptance remain open.

Captured table 20

Attempt · Actual result · Treatment in this report · 13 data rows

AttemptActual resultTreatment in this report
House alternate §1605 route: https://uscode.house.gov/view.xhtml?edition=prelim&num=0&req=granuleid%3AUSC-prelim-title15-section1605404Not relied on; operative body recovered through S001.
House CDN alternate §1605 route: https://usc-cdn.house.gov/view.xhtml?edition=prelim&num=0&req=granuleid%3AUSC-prelim-title15-section1605Timeout/error responseNot treated as a read; S001 recovery used.
House alternate §1606 route: https://uscode.house.gov/view.xhtml?edition=prelim&num=0&req=granuleid%3AUSC-prelim-title15-section1606Server errorNot relied on; operative body recovered through S002.
Guessed withdrawn-guidance route: https://www.consumerfinance.gov/rules-policy/withdrawn-guidance/UnavailableCorrect compliance/guidance register located and read as S012.
Short eCFR §17 route: https://www.ecfr.gov/current/title-12/chapter-X/part-1026/section-1026.17InaccessibleCanonical subpart-C route used in S006.
Current Appendix J HTML and direct assets in S009–S010Prose readable; equation images returned as unreadable placeholdersLegal APR hold retained. No memory-based reconstruction represented as an official equation read.
Official 2025 Appendix J PDF, S011Extracted prose available; equation pages not readable as equationsHistorical prose backup only; not a complete appendix read.
PDF screenshot attempts, zero-based indices 2 and 3Returned placeholders rather than inspectable image contentNo visual-inspection claim.
GovInfo HTML backup: https://www.govinfo.gov/content/pkg/CFR-2025-title12-vol9/html/CFR-2025-title12-vol9-part1026-appJ.htmInaccessibleDid not close legal-method gap.
FDIC body, S014403Search discovery only; no substantive reliance.
Search results and regulation indexUsed to discover relevant primary pages and versionsSnippets/index entries were not substituted for operative body reads.
Long multi-page retrievalsSome outputs were truncatedOnly visible content was treated as read; relevant §18 material was recovered in subsequent targeted reads.
Prior research or other chatsNone supplied or usedNo reused foundation, unseen review, or independent corroboration claimed.
Source links captured in this table

Captured table 21

Check · Result · Limit · 12 data rows

CheckResultLimit
E01 denominator arithmetic365, 360, and separately stipulated 366 calculations recomputed; end-rounding and daily-rounding results distinguishedDoes not select a lawful denominator or posting policy
E02 row conservationEach row satisfies opening + posted interest - cash payment = closingStated monthly cent-posting model only
E02 lifetime conservationPrincipal paid $10,000; interest $661.86; cash $10,661.86; ending principal exactly $0.00Not a daily-accrual schedule
E03 zero-rate handling11*833.33 + 833.37 = 10000; interest zero; ending balance zeroFees assumed absent
E04 controlled comparisonSame original parameters; extra $2,000 included in cash paid; final $494.88; ending balance zeroAllocation/prepayment permission assumed
E04 savingsInterest difference and cash difference both equal $170.57No penalty, rebate, or other charge included
E05 cash accountingIncluded, excluded, separately paid, and withheld structures distinguished; no double-counted feeActual classification unresolved
E05 numerical solutionOpposite-sign starting brackets and small evaluated present-value residuals checkedNot a validated legal APR engine or full software test suite
E06 accountingBoth branches preserve original balance + new interest - cash paid = remaining accounting balanceCapitalization permission unresolved
Citation/read integrityPrimary body reads, compilation dates, failed access, historical sources, and unread images separatedNo complete effective-history audit or independent review
Scope controlNo borrower/provider-status/account/case investigation; no fees operationally approved; no publication or filesReference research only
Acceptance statusThis is a self-check by the same assistantNo independent review, parent A004 acceptance, calculator acceptance, or publication acceptance

Captured table 22

Further packet · Remaining content · 10 data rows

Further packetRemaining content
Complete compound interest and capitalizationLawful capitalization events, timing, balance composition, compounding frequency, interest-on-interest restrictions, and contractual conditions
Open-end credit and cardsDaily periodic rates, balance methods, grace periods, minimum payments, allocation, and negative-amortization law
Variable and penalty ratesReset mechanics, index/margin/caps, payment changes, penalty-rate conditions, and disclosure requirements
Deferred interestConditional waivers, retroactive accrual, promotional timing, and product-specific rules
Late and collection costsFee authorization, classification, allocation, interest on charges, collection costs, and jurisdictional restrictions
Loan and jurisdiction-specific rulesMortgage, auto, student, payday, BNPL, commercial, tribal, country, state, and local law, plus individual-contract issues in an appropriately authorized scope
Complete legal APR methodsReadable full Appendix J equations; irregular/odd-day periods; multiple advances; balloons; United States Rule implementation; applicable official examples and complete method verification
Prepayment and rebatesRights, penalties, rebates, precomputed/add-on structures, Rule-of-78s restrictions, and contractual application
Tool validation and error handlingIndependently specified test cases, precision policies, malformed inputs, irregular dates, root failures, and version-controlled validation—none accepted by this pass
Bankruptcy, tax, settlement, and credit intersectionsSeparate substantive authority and factual boundaries; no settlement-fee ratios, tax outcomes, or credit promises inferred here

Find the assertion and its boundaries

Read the evidence with its boundaries. These are saved research components, including revisions. A scoped coordinator review checks selected evidence; it does not certify every claim, a complete jurisdiction, current law or individual applicability. Dates and access limits remain attached to the records.

How to read the research →

R004-P1-C001 Saved research record

Closed-end credit is credit other than open-end credit; consumer credit concerns primarily personal, family, or household purposes.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S004, §2(a)(10), (12)
Assumptions, conditions, exclusions, and status
Definition established; no transaction-specific purpose finding.
R004-P1-C002 Saved research record

Zero interest alone does not exclude coverage; written repayment in more than four installments is relevant under the general coverage rule.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S004, §1(c)(1)
Assumptions, conditions, exclusions, and status
Other coverage conditions and exemptions still matter; E03 assumes the relevant consumer setting.
R004-P1-C003 Saved research record

Business/commercial/agricultural purpose and organizational-credit provisions are coverage gateways; mixed-purpose analysis cannot be replaced by a label.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S004, §3(a), comments 3(a)-1–10
Assumptions, conditions, exclusions, and status
Gateway answered; actual classification unresolved and outside this pass.
R004-P1-C004 Saved research record

§18 excludes mortgage transactions subject to §19(e) and (f) from its general disclosure framework; security can change applicable provisions.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S007, §18 introductory paragraph; §18(s) gateway
Assumptions, conditions, exclusions, and status
Examples assume the non-mortgage setting; no mortgage-specialized conclusion.
R004-P1-C005 Saved research record

Disclosures reflect the legal obligation; the disclosure calculation is not independent permission to impose a charge.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S004, §1(b); S006, §17(c)(1), comments 1–2
Assumptions, conditions, exclusions, and status
Contract and applicable law remain required.
R004-P1-C006 Saved research record

B is the model’s interest-bearing principal, kept distinct from unpaid accrued interest U.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
Defined accounting model; S004, §2(b)(3); S006, §17(c)(1)
Assumptions, conditions, exclusions, and status
No universal statutory definition of every contract’s principal balance is asserted.
R004-P1-C007 Saved research record

A periodic rate applies to a specified period; an annual note rate requires its stated conversion/accrual convention.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S004, §2(a)(21), comment 1
Assumptions, conditions, exclusions, and status
Decimal per period in calculations; fee-inclusive APR is not substituted for the note rate.
R004-P1-C008 Saved research record

Finance charge is the legally classified dollar cost of consumer credit, including direct or indirect qualifying charges.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S001, §1605(a); S005, §4(a)
Assumptions, conditions, exclusions, and status
Coverage and exclusions required.
R004-P1-C009 Saved research record

Interest and loan fees are listed finance-charge categories, subject to the express exclusions.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S005, §4(b)(1), (3), introductory qualification to (b)
Assumptions, conditions, exclusions, and status
A fee label does not bypass (c)–(e).
R004-P1-C010 Saved research record

A charge of a type payable in a comparable cash transaction is excluded; a credit-specific excess requires separate treatment.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S001, §1605(a); S005, §4(a), comment 4(a)-1
Assumptions, conditions, exclusions, and status
Requires a genuinely comparable cash-charge basis.
R004-P1-C011 Saved research record

Application fees charged to all applicants, whether or not credit is extended, are excluded.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S005, §4(c)(1), comment 4(c)(1)-1
Assumptions, conditions, exclusions, and status
E05’s excluded branch is conditional on satisfying this test, not merely naming the fee “application.”
R004-P1-C012 Saved research record

Third-party charges can be included when use is required or to the extent retained by the creditor, unless otherwise excluded.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S005, §4(a)(1)(i)–(ii)
Assumptions, conditions, exclusions, and status
Consumer choice of provider does not by itself settle inclusion.
R004-P1-C013 Saved research record

Closing-agent charges have a separate test concerning required services, required charges, or retained portions.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S001, §1605(a); S005, §4(a)(2)
Assumptions, conditions, exclusions, and status
Not a universal rule for all third-party fees; mortgage-broker special rule not generalized.
R004-P1-C014 Saved research record

Specified voluntary credit-insurance premiums can be excluded only with the required optionality, written cost/term disclosures, and affirmative request.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S001, §1605(b); S005, §4(d)(1)(i)–(iii)
Assumptions, conditions, exclusions, and status
Optionality alone is insufficient. No insurance product is evaluated.
R004-P1-C015 Saved research record

Specified property-insurance premiums can qualify for exclusion under consumer-choice and disclosure conditions, even where insurance is required.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S001, §1605(c); S005, §4(d)(2)(i)–(ii)
Assumptions, conditions, exclusions, and status
Includes the stated conditions concerning single-interest insurance/subrogation where relevant; no universal “mandatory fee” rule.
R004-P1-C016 Saved research record

The listed bona fide, reasonable real-estate-related fee exclusion has a defined real-property/residential-mortgage scope.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S001, §1605(e); S005, §4(c)(7)(i)–(v)
Assumptions, conditions, exclusions, and status
Not transferred to all unsecured loans.
R004-P1-C017 Saved research record

Certain security-related public-official charges and substitute insurance require the specified itemization, disclosure, and statutory conditions for exclusion.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S001, §1605(d); S005, §4(e)
Assumptions, conditions, exclusions, and status
No blanket exclusion for every “government” or third-party charge.
R004-P1-C018 Saved research record

Charges for actual unanticipated late payment/default can be excluded from finance charge under §4(c)(2).

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S005, §4(c)(2); S007, §18(l) and relevant commentary
Assumptions, conditions, exclusions, and status
Exclusion is not authorization, waiver of cash cost, or proof that a disputed fee qualifies.
R004-P1-C019 Saved research record

A prepaid finance charge includes qualifying charges paid separately before/at consummation or withheld from proceeds; precomputed interest is not automatically prepaid merely because precomputed.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S004, §2(a)(23), comments 1–3
Assumptions, conditions, exclusions, and status
Classification as finance charge must first be established.
R004-P1-C020 Saved research record

Amount financed follows §18(b)’s calculation and must avoid double subtraction of included finance charges.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S003, §1638(a)(2); S007, §18(b)(1)–(3), comment 18(b)(3)-1
Assumptions, conditions, exclusions, and status
Distinguish the regulatory principal-loan input from the note face amount.
R004-P1-C021 Saved research record

Amount financed need not equal cash delivered directly to the consumer.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S007, §18(c)(1)(i)–(iv)
Assumptions, conditions, exclusions, and status
Amounts credited or paid on the consumer’s behalf may differ from direct proceeds.
R004-P1-C022 Saved research record

The payment schedule addresses number, amounts, and timing; prepaid finance charges are not separately inserted as schedule payments.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S007, §18(g), comments 18(g)-1, -4
Assumptions, conditions, exclusions, and status
Other permitted components can appear in scheduled payments; allocation remains a separate question.
R004-P1-C023 Saved research record

Total of payments is the sum of disclosed schedule payments; amount financed + finance charge is valid for the simple E05 streams, not asserted as every possible cash-flow identity.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S003, §1638(a)(5); S007, comment 18(h)-2 and 18(g)-1
Assumptions, conditions, exclusions, and status
Optional or other schedule components and separate upfront cash require careful reconciliation.
R004-P1-C024 Saved research record

Total interest is the sum of modeled interest accruals; it need not equal finance charge or interest paid.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
Defined arithmetic; S005, §4(b); E02, E05, E06
Assumptions, conditions, exclusions, and status
Period and accrual/payment basis must be stated.
R004-P1-C025 Saved research record

Closed-end legal APR depends on amount and timing under the applicable actuarial or United States Rule framework.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S002, §1606(a); S008, §22(a)(1)
Assumptions, conditions, exclusions, and status
Legal method identified; E05 legal result held.
R004-P1-C026 Saved research record

Appendix J describes APR as a nominal annual rate based on the unit-period rate and number of unit periods per year.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S009, Appendix J(b)(1), (b)(4)–(5)
Assumptions, conditions, exclusions, and status
This legal annualization is distinct from (1+r)^m - 1; full equation implementation unread.
R004-P1-C027 Saved research record

The general regular-transaction APR accuracy allowance is ±1/8 percentage point.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S008, §22(a)(2)
Assumptions, conditions, exclusions, and status
0.125 percentage point, not 0.125% relative error.
R004-P1-C028 Saved research record

The specified irregular-transaction allowance is ±1/4 percentage point; an irregular first period or first/final payment alone does not trigger that definition.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S008, §22(a)(3), relevant commentary
Assumptions, conditions, exclusions, and status
E02’s final cent adjustment alone is not a basis to assume irregular tolerance.
R004-P1-C029 Saved research record

§18(d)(2)’s finance-charge dollar tolerances differ from APR percentage-point tolerances.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S007, §18(d)(2)
Assumptions, conditions, exclusions, and status
Non-real-property/non-dwelling category: ±$5 at amount financed ≤$1,000; ±$10 above $1,000.
R004-P1-C030 Saved research record

The original amortization method alone does not determine reportable APR.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S002, §1606(a); S005, §4; S007, §18(b); S008, §22(a)(1)
Assumptions, conditions, exclusions, and status
Also requires correct classification, amount financed, dates, payments, and legal calculation method.
R004-P1-C031 Saved research record

A constant-period mathematical effective annual rate is (1+r)^m - 1.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
Derived by multiplying one-period growth factors m times
Assumptions, conditions, exclusions, and status
Compounding/equivalent-rate assumption; not charging authority or a legally labeled APR.
R004-P1-C032 Saved research record

A numerical IRR is a root of a specified discounted cash-flow equation; convergence alone does not verify legal APR compliance.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
Derived present-value identity; S008, §22(b)(2), comment 22(a)(1)-5
Assumptions, conditions, exclusions, and status
E05 is expressly an approximate numerical estimate.
R004-P1-C033 Saved research record

Constant-balance simple accrual is B*a*d/D; segmented accrual sums such terms under the same stated model.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
S013, steps 2–3; algebraic extension stated in §2.1
Assumptions, conditions, exclusions, and status
Dollar balance, annual decimal rate, counted days, stated denominator; actual application held.
R004-P1-C034 Saved research record

Identified sources discuss 365/360 distinctions and a stated 365/366 convention; none establishes one universal convention.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
S006, comment 17(c)(3)-1(ii); S004, comment 2(a)(21)-1; S013, step 2
Assumptions, conditions, exclusions, and status
Complete Actual/Actual and 30/360 conventions not established.
R004-P1-C035 Saved research record

Actual payment-crediting dates, inclusivity, partial-payment effects, and due-date changes require the legal obligation and applicable rules.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
S006, §17(c)(1), comments 1–2; §17(c)(2)(i), comment 3
Assumptions, conditions, exclusions, and status
No receipt/posting/value-date or holiday rule invented.
R004-P1-C036 Saved research record

Accrued unpaid interest and capitalized interest are separate accounting states; APR computational descriptions do not grant capitalization authority.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
S008, comments 22(a)(1)-2–3; S009, Appendix J(a)(2)–(3); E06
Assumptions, conditions, exclusions, and status
Real capitalization permission unresolved.
R004-P1-C037 Saved research record

Ledger precision, posted-cent rounding, and cash-payment rounding can produce different totals and final installments.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
Derived E01/E02 calculations; S006, comment 17(c)(3)-1(i)
Assumptions, conditions, exclusions, and status
The chosen half-up posting rule is hypothetical, not a universal legal requirement.
R004-P1-C038 Saved research record

r = annual nominal rate / 12 is used only because the monthly convention defines that relationship.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
Model definition; S004, §2(a)(21); algebraic effective-rate conversion
Assumptions, conditions, exclusions, and status
Not substituted for daily accrual or fee-inclusive APR.
R004-P1-C039 Saved research record

Under the equal-period, interest-first, no-fee model, B_k = B_(k-1)*(1+r) - M.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
Derived balance conservation in §2.2
Assumptions, conditions, exclusions, and status
Requires adequate payment or separate unpaid-interest treatment.
R004-P1-C040 Saved research record

For r>0, equal end-period payments amortizing P over n periods satisfy M=P*r/[1-(1+r)^(-n)].

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
Derivation in §2.2 from C039
Assumptions, conditions, exclusions, and status
Fixed rate, equal periods, full amortization, no omitted charges.
R004-P1-C041 Saved research record

At zero rate, use M=P/n, then explicitly handle cent rounding in the final installment.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
Derived E03
Assumptions, conditions, exclusions, and status
No division by zero.
R004-P1-C042 Saved research record

A positive terminal balance requires explicit residual/balloon treatment; it is not a zero ending balance.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
Balance identity C039; E02/E03 final-payment checks
Assumptions, conditions, exclusions, and status
Actual maturity and residual terms required.
R004-P1-C043 Saved research record

Extra principal reduces later model interest only after application to principal; the calculation does not establish due-date advancement or recast rights.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
Derived E04; S006, §17(c)(1); S007, §18(k), (p)
Assumptions, conditions, exclusions, and status
Immediate extra-principal application and no penalty are assumptions.
R004-P1-C044 Saved research record

Declining-balance and precomputed-charge prepayment analyses require separate treatment; E04 savings cannot be mechanically transferred.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
S007, §18(k)(1)–(2); S004, comment 2(a)(23)-3
Assumptions, conditions, exclusions, and status
Full rebate, penalty, add-on, and Rule-of-78s law remains held.
R004-P1-C045 Saved research record

E01’s 365/360 end-rounded charges are $98.63/$100.00, with a $1.37 difference.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
E01 displayed inputs, equations, and rounding comparison
Assumptions, conditions, exclusions, and status
Derived arithmetic; denominator application not adjudicated.
R004-P1-C046 Saved research record

E02’s posted-cent schedule pays $10,000 principal and $661.86 interest, ending at exactly zero after an $888.47 final payment.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
E02 complete 12-row schedule
Assumptions, conditions, exclusions, and status
Verified within stated monthly and rounding model.
R004-P1-C047 Saved research record

E03’s eleven $833.33 payments plus $833.37 repay exactly $10,000 with no interest.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
E03 arithmetic
Assumptions, conditions, exclusions, and status
Zero rate and no fees only.
R004-P1-C048 Saved research record

E04’s controlled extra-principal path produces $491.29 interest and saves $170.57 relative to E02.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
E04 complete 10-row schedule and comparison
Assumptions, conditions, exclusions, and status
Same original principal/rate/convention; allocation and no-penalty assumptions explicit.
R004-P1-C049 Saved research record

E05’s included-fee branch yields conditional amount financed $9,700 and finance charge $961.86 while preserving the $10,000 note balance.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
S007, comment 18(b)(3)-1; E05 cash table
Assumptions, conditions, exclusions, and status
Separate-at-origination fee; no double counting; legal classification conditional.
R004-P1-C050 Saved research record

E05’s numerical annualized roots are approximately 12.0001146283% for V=10000 and 17.8250427572% for V=9700.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
E05 equation, bracket, iterations, residuals
Assumptions, conditions, exclusions, and status
Decimal monthly roots; not legal APR results.
R004-P1-C051 Saved research record

E05’s corresponding effective annualized numerical rates are approximately 12.6826309005% and 19.3558891893%.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
Derived from C050 using 100*((1+q)^12-1)
Assumptions, conditions, exclusions, and status
Mathematical annual equivalence only.
R004-P1-C052 Saved research record

E06 without capitalization ends with $1,000 principal plus $15 unpaid interest after $15 cash paid.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
E06 Branch A
Assumptions, conditions, exclusions, and status
Interest accrues only on original principal; three-month observation.
R004-P1-C053 Saved research record

E06 with stipulated monthly capitalization ends at $1,015.15 after $30.15 new interest and $15 cash paid.

Recorded check status: supported with explicit model and legal limits

Source and exact pinpoint
E06 Branch B
Assumptions, conditions, exclusions, and status
Cent posting; capitalization legality and contract permission not established.
R004-P1-C054 Saved research record

The CFPB Withdrawn Guidance register was freshly checked; no circular, bulletin, or advisory supports this report’s substantive conclusions.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S012, full register and metadata
Assumptions, conditions, exclusions, and status
Withdrawal is not treated here as alteration or repeal of the retrieved controlling texts.
R004-P1-C055 Saved research record

Retrieval date and source compilation/effective dates are different; this report preserves the displayed dates and gaps.

Recorded check status: supported with selected primary and evidence limits

Source and exact pinpoint
S001–S004, S006–S009, S011–S013
Assumptions, conditions, exclusions, and status
No complete amendment-lag or section-effective-history certification.
R004-P1-C056 Saved research record

Complete operative Appendix J equation content was not readable; therefore the legal APR calculation is held.

Recorded check status: current HTML equation gap observed historical failures attributed legal APR held

Source and exact pinpoint
S009–S011; failure log below
Assumptions, conditions, exclusions, and status
Prose read and numerical math do not substitute for the missing legal-method read.

Sources, pinpoints and access limits

Keep the source version, actual read extent and jurisdiction with the proposition. A link or researcher access claim is not a substitute for an operative primary passage.

R004-P1-S001 Saved research record

U.S. House, U.S. Code, 15 U.S.C. §1605 — Determination of finance charge. https://uscode.house.gov/us/usc/119-121/t15/s1605/

Recorded check status: fresh selected primary body checked

Exact relevant location
§1605(a)–(f), especially (a) general definition and third-party closing charges; (b)–(e) conditional exclusions
Version, effective trigger, or status
Body displayed currency through P.L. 119-121, October 9, 2026. Source credits include enactment May 29, 1968 and later amendments; effective-date history was not independently reconstructed.
Actual check date and fresh read extent
2026-10-27 PDT. Fresh: operative (a)–(f) and selected notes. Recovered after failed alternate routes.
Jurisdiction and contract limits
Federal TILA classification; does not establish coverage or charging authority for a particular loan. uscode.house.gov
Direct source URLs
https://uscode.house.gov/us/usc/119-121/t15/s1605/
https://uscode.house.gov/us/usc/119-121/t15/s1605/?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
House1605(a)-(f), displayedcurrency line15 and selectednotes; packet01.
coordinator result
Finance-charge and conditional exclusion framework supported; PL119-121/October9 displayed, no October10-27 session-law completeness claim.
R004-P1-S002 Saved research record

U.S. House, U.S. Code, 15 U.S.C. §1606 — Determination of annual percentage rate. https://uscode.house.gov/us/usc/119-121/t15/s1606/

Recorded check status: fresh selected primary body checked

Exact relevant location
§1606(a)–(e), especially (a)(1) and (c)
Version, effective trigger, or status
Body displayed currency through P.L. 119-121, October 9, 2026. Original 1968 provision with later amendments; no independent effective-history audit.
Actual check date and fresh read extent
2026-10-27 PDT. Fresh: complete operative (a)–(e).
Jurisdiction and contract limits
Statutory APR computation authority; its computational allocation is not a universal servicing waterfall. uscode.house.gov
Direct source URLs
https://uscode.house.gov/us/usc/119-121/t15/s1606/
https://uscode.house.gov/us/usc/119-121/t15/s1606/?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
House1606(a)-(e),currency and selectednotes; packet01.
coordinator result
Nominal/actuarial statutory framework supported; computational allocation is not a universal servicing clause.
R004-P1-S003 Saved research record

U.S. House, U.S. Code, 15 U.S.C. §1638 — Requirements for certain mortgages and other consumer credit transactions. https://uscode.house.gov/us/usc/119-118/t15/s1638/

Recorded check status: fresh selected primary body checked

Exact relevant location
Relevant complete §1638(a)(1)–(12)
Version, effective trigger, or status
Page body stated currency through P.L. 119-120, October 7, 2026, despite the different number in its URL. That displayed body currency is recorded; no inference from the URL alone.
Actual check date and fresh read extent
2026-10-27 PDT. Fresh: relevant (a)(1)–(12); later mortgage material encountered but not fully investigated.
Jurisdiction and contract limits
Federal closed-end disclosures; mortgage-specialized provisions excluded from full analysis. uscode.house.gov
Direct source URLs
https://uscode.house.gov/us/usc/119-118/t15/s1638/
https://uscode.house.gov/us/usc/119-118/t15/s1638/?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
House1638(a)(1)-(12) and currency line15; packet01.
coordinator result
Amount-financed/disclosure distinctions supported. Bodycurrency PL119-120/October7 despite119-118 URL. Actual heading Transactions other than under an open end credit plan; report source-title wording is a minor label variation, not a different section.
R004-P1-S004 Saved research record

CFPB, Regulation Z index; §§1026.1, .2, .3 and embedded official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/; https://www.consumerfinance.gov/rules-policy/regulations/1026/1/; https://www.consumerfinance.gov/rules-policy/regulations/1026/2/; https://www.consumerfinance.gov/rules-policy/regulations/1026/3/

Recorded check status: fresh selected primary body and index checked

Exact relevant location
§1(a)–(c); §2(a)(10)–(14), (20)–(23), (b); relevant definition comments; §3(a) and comments, selected §3(b)
Version, effective trigger, or status
Current-page designation. Index: Part 1026 most recently amended April 8, 2026. This is part-wide metadata, not individual-section effective dating.
Actual check date and fresh read extent
2026-10-27 PDT. Fresh: identified operative paragraphs and relevant comments; index read for metadata/discovery, not as substantive body evidence.
Jurisdiction and contract limits
Consumer/closed-end/creditor/exemption gateway only; no transaction-specific coverage determination. Consumer Financial Protection Bureau +3
Direct source URLs
https://www.consumerfinance.gov/rules-policy/regulations/1026/
https://www.consumerfinance.gov/rules-policy/regulations/1026/1/
https://www.consumerfinance.gov/rules-policy/regulations/1026/2/
https://www.consumerfinance.gov/rules-policy/regulations/1026/3/
https://www.consumerfinance.gov/rules-policy/regulations/1026/?utm_source=chatgpt.com
https://www.consumerfinance.gov/rules-policy/regulations/1026/1/?utm_source=chatgpt.com
https://www.consumerfinance.gov/rules-policy/regulations/1026/2/?utm_source=chatgpt.com
https://www.consumerfinance.gov/rules-policy/regulations/1026/3/?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
CFPB1(b),1(c)(1) fourconditions;2(a)(10),(12),(13),(17)(i),(21),(23) and selectedcomments;3(a) purposecomments1-8 selected; Part1026index April8metadata and official-edition disclaimer. Packets08-11.
coordinator result
Conditional gateway/definitions supported. No full exemption/product/creditor or underlying CFPA carveout audit. April8is part-wide metadata, not every section amendment.
R004-P1-S005 Saved research record

CFPB and eCFR, §1026.4 — Finance charge; official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/4/; https://www.consumerfinance.gov/rules-policy/regulations/1026/interp-4/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-A/section-1026.4

Recorded check status: fresh selected primary body checked

Exact relevant location
Relevant complete rules in (a)–(f); comments on comparable cash charges, application fees, third parties, insurance, security charges, and late charges
Version, effective trigger, or status
CFPB current text; eCFR Title 12 displayed through October 23, 2026. No claim that date is this section’s amendment date.
Actual check date and fresh read extent
2026-10-27 PDT. Fresh: CFPB operative clauses and relevant embedded commentary; separate interpretation page’s opening definition; eCFR visible body through (d)(3)(ii). Unrelated open-end material was not a separate investigation.
Jurisdiction and contract limits
Conditional federal classification rules. Real-estate and mortgage exceptions are not generalized to unsecured credit. ecfr.gov +2
Direct source URLs
https://www.consumerfinance.gov/rules-policy/regulations/1026/4/
https://www.consumerfinance.gov/rules-policy/regulations/1026/interp-4/
https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-A/section-1026.4
https://www.consumerfinance.gov/rules-policy/regulations/1026/4/?utm_source=chatgpt.com
https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-A/section-1026.4?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
CFPB4(a),comments4(a)-1,4(a)(1)-(3),4(b)introduction/(1),4(c)(1)-(2),4(c)(7)introduction/comments,4(d)(1)-(2),4(e)(1)-(3)/selectedcomments and4(f). Packets02-04,07.
coordinator result
Fee label/optionality/recipient insufficient. Selected conditional rules support report; remaining mortgage/open-end/special-coverage details not broadly accepted.
R004-P1-S006 Saved research record

CFPB and eCFR, §1026.17 — General disclosure requirements; official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/17/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.17

Recorded check status: fresh selected primary body checked

Exact relevant location
§17(c)(1)–(3); comments 17(c)(1)-1–2, 17(c)(2)(i)-3, 17(c)(3)-1–2; selected (c)(4) material
Version, effective trigger, or status
Current agency text; eCFR displayed through October 23, 2026. Disclosure inputs reflect the legal obligation.
Actual check date and fresh read extent
2026-10-27 PDT. Fresh: complete relevant clauses/comments above; odd-first-period material only to identify the gateway, not apply the full method.
Jurisdiction and contract limits
Disclosure assumptions are not universal accrual, receipt-date, capitalization, or holiday-servicing rules. Consumer Financial Protection Bureau +2
Direct source URLs
https://www.consumerfinance.gov/rules-policy/regulations/1026/17/
https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.17
https://www.consumerfinance.gov/rules-policy/regulations/1026/17/?utm_source=chatgpt.com
https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.17?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
CFPB17(c)(1) comments1-2;17(c)(2)(i)comment3;17(c)(3)comment1(i)-(ii). Packets06,10.
coordinator result
Legal obligation/current schedule distinct from observed behavior; final-cent adjustment and360tool-versus-365actual distinctions supported. No universal receipt/rounding/accrual authority.
R004-P1-S007 Saved research record

CFPB and eCFR, §1026.18 — Content of disclosures; official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/18/; https://www.consumerfinance.gov/rules-policy/regulations/1026/interp-18/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.18

Recorded check status: fresh selected primary body checked

Exact relevant location
Introductory scope; (b), (c), (d), (e), (g), (h), (k), (l), (p); relevant comments including 18(b)(3)-1–2, 18(g)-1, -4, 18(h)-2
Version, effective trigger, or status
Current agency text; eCFR displayed through October 23, 2026. Underlying section-specific effective history not fully audited.
Actual check date and fresh read extent
2026-10-27 PDT. Fresh: relevant complete rules and associated comments; §18(c)(1)–(3) and its relevant itemization material recovered in fresh reads. Mortgage tables not fully investigated.
Jurisdiction and contract limits
Examples use the non-mortgage framework. Prepayment disclosures do not resolve substantive prepayment rights. ecfr.gov +3
Direct source URLs
https://www.consumerfinance.gov/rules-policy/regulations/1026/18/
https://www.consumerfinance.gov/rules-policy/regulations/1026/interp-18/
https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.18
https://www.consumerfinance.gov/rules-policy/regulations/1026/18/?utm_source=chatgpt.com
https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.18?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
CFPB18intro/scope;18(b)(1)-(3) operative clauses and relevant18(b)(3)-1 examples;18(d)(2),18(g)comments1/4,18(h)comment2,18(k)(1)-(2) and selectedcomments/18(l). Packets02-04,06,10.
coordinator result
Included/excluded/separate/withheld/financed inputs and avoidance of double subtraction supported. Substantive prepayment and actual charging permission remain held.
R004-P1-S008 Saved research record

CFPB and eCFR, §1026.22 — Determination of APR; official interpretations. https://www.consumerfinance.gov/rules-policy/regulations/1026/22/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.22

Recorded check status: fresh selected primary body checked with failed ecfr crosscheck

Exact relevant location
Entire operative section and embedded commentary; especially (a)(1)–(3), (b)(2), comments 22(a)(1)-1–5
Version, effective trigger, or status
Current text; eCFR displayed through October 23, 2026. Section history cited 76 FR 79772, Dec. 22, 2011; 78 FR 80112, Dec. 31, 2013; 80 FR 80229, Dec. 24, 2015. Underlying rulemaking effective dates not separately read.
Actual check date and fresh read extent
2026-10-27 PDT. Fresh: full section and embedded comments. Mortgage tolerances and add-on shortcut provisions were read but not applied.
Jurisdiction and contract limits
Provides APR methods/accuracy framework; does not validate the present numerical routine or authorize contract charges. Consumer Financial Protection Bureau +1
Direct source URLs
https://www.consumerfinance.gov/rules-policy/regulations/1026/22/
https://www.ecfr.gov/current/title-12/chapter-X/part-1026/subpart-C/section-1026.22
https://www.consumerfinance.gov/rules-policy/regulations/1026/22/?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
CFPB22(a)(1)-(3),comments22(a)(1)-1 through5 and22(b)(1)-(2),selected mortgage-tolerance text not applied; packets05-07,09-10. eCFR22 returned Request Access/CAPTCHA redirect to unblock.federalregister.gov, packet11.
coordinator result
Actuarial/U.S.Rule/tolerance/computation-tool propositions supported by agency text; eCFR October23 observation remains researcher-attributed. No CAPTCHA/API workaround, official-edition/currentness audit remains open.
R004-P1-S009 Saved research record

CFPB/eCFR, Appendix J — APR computations for closed-end credit; official interpretation. https://www.consumerfinance.gov/rules-policy/regulations/1026/j/; https://www.consumerfinance.gov/rules-policy/regulations/1026/interp-j/; https://www.ecfr.gov/current/title-12/chapter-X/part-1026/appendix-Appendix%20J%20to%20Part%201026

Recorded check status: fresh partial primary body checked

Exact relevant location
Readable (a), (b)(1)–(6), textual (b)(9), example headings/introductions; complete official comment J-1–2
Version, effective trigger, or status
Linked from current Regulation Z. The current display did not make all equation assets readable.
Actual check date and fresh read extent
2026-10-27 PDT. Fresh partial body: prose read; eCFR extraction stopped before the needed equation content. Not a complete operative-equation read.
Jurisdiction and contract limits
Supports framework only. Legal calculation held because symbols/equations/examples in (b)(7)–(9) and relevant (c) panels were not readable. Consumer Financial Protection Bureau +3
Direct source URLs
https://www.consumerfinance.gov/rules-policy/regulations/1026/j/
https://www.consumerfinance.gov/rules-policy/regulations/1026/interp-j/
https://www.ecfr.gov/current/title-12/chapter-X/part-1026/appendix-Appendix%20J%20to%20Part%201026
https://www.ecfr.gov/current/title-12/chapter-X/part-1026/appendix-Appendix%20J%20to%20Part%201026?utm_source=chatgpt.com
https://www.consumerfinance.gov/rules-policy/regulations/1026/J/?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
CFPBJ officialcomments1-2;J(a)(1)-(3),J(b)(1)-(6),J(b)(7)-(9) textualheadings/iteration prose andJ(c)(1)-(7)equation-link headings. Packets05-07,09-10.
coordinator result
General equation/symbol/iteration/example content appears as image links in retrieved text. No complete equation-image read/visual verification; legal APR remains held.
R004-P1-S010 Saved research record

CFPB, Appendix J equation/image assets, same underlying document as S009. https://files.consumerfinance.gov/eregulations/ER22DE11.062-1.png; https://files.consumerfinance.gov/eregulations/ER22DE11.062-2.png; https://files.consumerfinance.gov/eregulations/ER22DE11.063-1.png; https://files.consumerfinance.gov/eregulations/ER22DE11.063-2.png; https://files.consumerfinance.gov/eregulations/ER22DE11.064-1.png; https://files.consumerfinance.gov/eregulations/ER22DE11.066-1.png

Recorded check status: researcher attributed failed assets not retried

Exact relevant location
Symbol panels, general equation, iteration example, regular-payment example, odd-final-payment example
Version, effective trigger, or status
Assets linked by current page. Filename dates are not treated as independently verified adoption/effective dates.
Actual check date and fresh read extent
2026-10-27 PDT. Attempted: responses were image placeholders without readable image contents. No equation read or visual verification claimed.
Jurisdiction and contract limits
Failed recovery, not corroborating substantive evidence.
Direct source URLs
https://files.consumerfinance.gov/eregulations/ER22DE11.062-1.png
https://files.consumerfinance.gov/eregulations/ER22DE11.062-2.png
https://files.consumerfinance.gov/eregulations/ER22DE11.063-1.png
https://files.consumerfinance.gov/eregulations/ER22DE11.063-2.png
https://files.consumerfinance.gov/eregulations/ER22DE11.064-1.png
https://files.consumerfinance.gov/eregulations/ER22DE11.066-1.png

Recorded coordinator check boundaries

coordinator read limits
Whole original source row and failure log read; six direct image routes not reattempted in this review.
coordinator result
Prior researcher failure retained. No new asset failure, equation-body or image-pixel verification credited.
R004-P1-S011 Saved research record

U.S. Government Publishing Office, 2025 CFR, Title 12, volume 9, Appendix J. https://www.govinfo.gov/content/pkg/CFR-2025-title12-vol9/pdf/CFR-2025-title12-vol9-part1026-appJ.pdf

Recorded check status: researcher attributed historical pdf not reopened

Exact relevant location
Printed pages 436–447; zero-based PDF indices 0–11
Version, effective trigger, or status
January 1, 2025 edition, historical backup rather than proof of October 2026 currency
Actual check date and fresh read extent
2026-10-27 PDT. Fresh extracted text: substantive prose on printed pp. 436–437, indices 0–1. Later pages supplied headers/graphic markers without readable equations. Screenshot attempts at indices 2–3 did not yield inspectable content. No visual inspection claimed.
Jurisdiction and contract limits
Backup failed to close the Appendix J equation gap. govinfo.gov +1
Direct source URLs
https://www.govinfo.gov/content/pkg/CFR-2025-title12-vol9/pdf/CFR-2025-title12-vol9-part1026-appJ.pdf
https://www.govinfo.gov/content/pkg/CFR-2025-title12-vol9/pdf/CFR-2025-title12-vol9-part1026-appJ.pdf?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
Whole original source row and failure log read;2025annual PDF and screenshot results not independently reopened.
coordinator result
Historical Jan1,2025 edition/pp436-447 not authenticated as current October2026. No coordinator PDF pixel or full12page read.
R004-P1-S012 Saved research record

CFPB, Withdrawn guidance. https://www.consumerfinance.gov/compliance/guidance/withdrawn-guidance/

Recorded check status: fresh selected register and metadata checked

Exact relevant location
Register entries and last-modified metadata
Version, effective trigger, or status
Displayed last modified July 22, 2026, 12:12 PM EDT
Actual check date and fresh read extent
2026-10-27 PDT. Fresh: register body and metadata read.
Jurisdiction and contract limits
No CFPB circular, bulletin, or advisory was relied on. Withdrawal register not treated as repeal of retrieved statutes, regulations, or Supplement I. Consumer Financial Protection Bureau +1
Direct source URLs
https://www.consumerfinance.gov/compliance/guidance/withdrawn-guidance/
https://www.consumerfinance.gov/compliance/guidance/withdrawn-guidance/?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
WithdrawnGuidance selectedregisterbody and last-modified line179; packets08-09.
coordinator result
July22,2026 12:12PMEDT metadata supported. Whole R004report uses no CFPBcircular/bulletin/advisory for substantive conclusion. No individual withdrawal notice opened or regulation-repeal inference.
R004-P1-S013 Saved research record

Bank of America, public generic Explanation of Simple Interest Calculation. https://secure.bankofamerica.com/content/pdf/en_us/Explanation_of_Simple_Interest_Calculation.pdf

Recorded check status: fresh complete one page parsed text checked

Exact relevant location
One unnumbered printed page; zero-based PDF index 0; steps 2–3
Version, effective trigger, or status
Document marked Rev. 12/17/2010
Actual check date and fresh read extent
2026-10-27 PDT. Fresh: complete extracted text of the one-page document. Text read, not visual inspection.
Jurisdiction and contract limits
Establishes only its stated 365/366 convention. Not a current-policy finding, consumer agreement, or universal legal rule. secure.bankofamerica.com
Direct source URLs
https://secure.bankofamerica.com/content/pdf/en_us/Explanation_of_Simple_Interest_Calculation.pdf
https://secure.bankofamerica.com/content/pdf/en_us/Explanation_of_Simple_Interest_Calculation.pdf?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
Generic BankofAmerica one-page PDF complete extractedlines0-29/index0; packet05.
coordinator result
Rev12/17/2010;365/366 stated. No current agreement/policy/universal rule. Handout displayed2.33*33/29 results use underlying unrounded rate; report does not import those as daily-cent-posting arithmetic. Parsed text only, no pixels.
R004-P1-S014 Saved research record

FDIC, Consumer Compliance Examination Manual, TILA section. https://www.fdic.gov/consumer-compliance-examination-manual/v-1-truth-lending-act-tila

Recorded check status: researcher attributed discovery failure not retried

Exact relevant location
Search discovery only
Version, effective trigger, or status
Body access returned 403
Actual check date and fresh read extent
2026-10-27 PDT. Failed body access: no substantive body reliance
Jurisdiction and contract limits
Search snippet is not evidence of a complete operative read. Current Regulation Z commentary supplied the relied-on denominator discussion instead.
Direct source URLs
https://www.fdic.gov/consumer-compliance-examination-manual/v-1-truth-lending-act-tila
https://www.fdic.gov/consumer-compliance-examination-manual/v-1-truth-lending-act-tila?utm_source=chatgpt.com

Recorded coordinator check boundaries

coordinator read limits
Whole original source row/failurelog read; FDIC403notreattempted.
coordinator result
No substantive FDIC body read or fresh failed-route evidence credited.

What was examined—and what is still missing

The saved component-level coverage record keeps answered, partial, blank and unresolved branches distinct. A coverage label is not acceptance of a whole subject or jurisdiction.

coverage-1 Saved research record

1 — Closed-end consumer gateway

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered as a gateway
Claim/example links
C001–C004
Exact missing authority or term; next bounded action
Actual creditor/transaction coverage facts absent by design; any later application requires the relevant coverage provisions and authorized facts.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-2 Saved research record

1 — Principal balance

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered as model definition; actual balance composition unresolved
Claim/example links
C006, C020–C021
Exact missing authority or term; next bounded action
Missing interest-bearing-balance clause and lawful treatment of financed charges/capitalization; inspect a published generic contract in a later packet.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-3 Saved research record

1 — Interest/note/periodic rate

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered
Claim/example links
C007, C038
Exact missing authority or term; next bounded action
Actual annual-rate conversion and accrual clause absent; do not infer from payment frequency.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-4 Saved research record

1 — Finance charge

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered, conditional classification framework
Claim/example links
C008–C018
Exact missing authority or term; next bounded action
Actual fee purpose, payee, comparable-cash treatment, and exclusion facts absent.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-5 Saved research record

1 — Amount financed

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered
Claim/example links
C019–C021; E05
Exact missing authority or term; next bounded action
Actual principal-loan input, included charges, and disbursement structure needed for application.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-6 Saved research record

1 — Payment and total of payments

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered
Claim/example links
C022–C023; E02–E05
Exact missing authority or term; next bounded action
Actual schedule and additional components absent; do not equate total of payments with every origination cash outflow.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-7 Saved research record

1 — Total interest

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered
Claim/example links
C024; E02, E04, E06
Exact missing authority or term; next bounded action
Actual accrual period and paid-versus-accrued basis must be specified.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-8 Saved research record

1 — Legal APR versus note rate

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered conceptually; calculation held
Claim/example links
C025–C030, C056
Exact missing authority or term; next bounded action
Missing readable operative Appendix J equations and complete applicable calculation implementation.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-9 Saved research record

1 — Effective annual yield and numerical IRR

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered mathematically
Claim/example links
C031–C032, C050–C051
Exact missing authority or term; next bounded action
No additional authority needed for stated algebra; no statutory APR equivalence asserted.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-10 Saved research record

1 — Fee inclusion/exclusion and timing affect comparison

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered conditionally
Claim/example links
C008–C023, C030; E05
Exact missing authority or term; next bounded action
Actual classification facts and legally applicable dates required before a legal APR.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-11 Saved research record

1 — Open-end, deferred-interest, mortgage-specialized full inquiry

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Excluded as directed
Claim/example links
C004; remaining packets
Exact missing authority or term; next bounded action
Separate product-specific sources and methods required.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-12 Saved research record

2 — Constant-balance daily formula

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered
Claim/example links
C033; E01
Exact missing authority or term; next bounded action
Actual rate, balance base, days, and denominator needed for application.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-13 Saved research record

2 — 365 versus 360

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered as sourced distinction and hypothetical arithmetic
Claim/example links
C034–C045; E01
Exact missing authority or term; next bounded action
No actual adopted denominator; next read a published generic accrual clause and applicable law.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-14 Saved research record

2 — Leap-year/actual-year alternative

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Partial
Claim/example links
C034; E01; S013
Exact missing authority or term; next bounded action
Published 365/366 statement read; complete cross-year Actual/Actual rules and current contract adoption not established.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-15 Saved research record

2 — Receipt, posting, value date and endpoint inclusivity

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Unresolved for actual application
Claim/example links
C035
Exact missing authority or term; next bounded action
Missing credited-date and day-inclusion clause plus applicable legal requirements; later packet must establish both.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-16 Saved research record

2 — Partial payments, prepayments, and residuals

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered as model boundaries
Claim/example links
C035, C042–C044; E04
Exact missing authority or term; next bounded action
Missing partial-payment holding/application, principal-curtailment, and residual terms.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-17 Saved research record

2 — Accrued versus capitalized interest

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered mathematically; permission unresolved
Claim/example links
C036; E06
Exact missing authority or term; next bounded action
Missing capitalization event, base, timing, and applicable authorization/restriction.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-18 Saved research record

2 — Ledger precision versus cash rounding

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered
Claim/example links
C037; E01–E03
Exact missing authority or term; next bounded action
Actual posting/rounding clause or authoritative servicing rule absent.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-19 Saved research record

2 — Late/extra payments and due dates

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered as non-inference
Claim/example links
C035, C043
Exact missing authority or term; next bounded action
Missing any contractual due-date advancement, modification, recast, or deferment provision.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-20 Saved research record

3 — Positive-rate payment formula and recurrence

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered and derived
Claim/example links
C039–C040; E02
Exact missing authority or term; next bounded action
Formula applies only to stated constant-period model.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-21 Saved research record

3 — Number and frequency of payments

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered for equal monthly periods
Claim/example links
C022, C038–C040
Exact missing authority or term; next bounded action
Actual first-payment date and irregular-period terms absent; no real calendar assumed.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-22 Saved research record

3 — First two allocations and last installment

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered with complete schedule
Claim/example links
C046; E02
Exact missing authority or term; next bounded action
No missing mathematical input for the displayed model.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-23 Saved research record

3 — Rounding, balloon, residual cases

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered as arithmetic and gateway
Claim/example links
C037, C042; E02–E03
Exact missing authority or term; next bounded action
Actual balloon/maturity and residual disposition needed beyond the model.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-24 Saved research record

3 — When annual rate/12 applies

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered with explicit condition
Claim/example links
C038
Exact missing authority or term; next bounded action
Actual monthly conversion convention would need contractual support.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-25 Saved research record

3 — Monthly versus daily separation

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered
Claim/example links
C033–C040; E01–E02
Exact missing authority or term; next bounded action
No conversion or equivalence silently imposed.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-26 Saved research record

3 — Zero rate

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered separately
Claim/example links
C041, C047; E03
Exact missing authority or term; next bounded action
No division by zero; final four-cent adjustment shown.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-27 Saved research record

3 — Insufficient payment/negative amortization boundary

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered mathematically; full law deferred
Claim/example links
C036, C052–C053; E06
Exact missing authority or term; next bounded action
Missing capitalization and product-specific negative-amortization/minimum-payment law.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-28 Saved research record

4 — Complete actual Appendix J method

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Partial; legal calculation held
Claim/example links
C025–C030, C056; S009–S011
Exact missing authority or term; next bounded action
Readable (b)(7)–(9) equation panels and applicable (c) example needed; obtain an accessible official rendering in a later packet.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-29 Saved research record

4 — Actual official calculation conventions

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered to readable extent
Claim/example links
C026–C029
Exact missing authority or term; next bounded action
Unit-period/annualization prose and tolerances read; this does not close the equation gap.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-30 Saved research record

4 — Cash-flow timing/frequency

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered for numerical model
Claim/example links
E05
Exact missing authority or term; next bounded action
Relative times 0–12 equal model months supplied; actual legal dates/odd-day rules unresolved.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-31 Saved research record

4 — Legal APR versus numerical estimate

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered expressly
Claim/example links
C032, C050, C056
Exact missing authority or term; next bounded action
All numerical rates remain non-certified; no computed legal APR reported.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-32 Saved research record

4 — Numerical convergence, tolerance, units

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered
Claim/example links
C027–C029, C050; E05
Exact missing authority or term; next bounded action
Bisection and dollar residual checked; not a general calculator validation.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-33 Saved research record

4 — Mandatory, optional, third-party fees

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered as conditional tests
Claim/example links
C009–C018
Exact missing authority or term; next bounded action
Actual fee facts and compliance with exclusion conditions required.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-34 Saved research record

4 — Prepaid charge, net proceeds, financed principal

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered with branches
Claim/example links
C019–C021, C049; E05
Exact missing authority or term; next bounded action
Actual separate/withheld/financed structure needed; financed-on-top version requires a new schedule.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-35 Saved research record

4 — Original amortization does not determine APR alone

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered
Claim/example links
C030; E05
Exact missing authority or term; next bounded action
Correct legal classification and calculation method remain independent prerequisites.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-36 Saved research record

5 — Same original principal/rate/contract convention

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered within stipulated model
Claim/example links
C046, C048; E02/E04
Exact missing authority or term; next bounded action
Both paths use identical original parameters; no unrelated-loan comparison.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-37 Saved research record

5 — Specified extra principal and allocation order

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered as an assumption
Claim/example links
C043, C048; E04
Exact missing authority or term; next bounded action
Actual waterfall and right to immediate principal application not established.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-38 Saved research record

5 — Interest saved, total cash, final partial payment

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered and reconciled
Claim/example links
C048; E04
Exact missing authority or term; next bounded action
No missing numerical input for the displayed comparison.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-39 Saved research record

5 — Prepayment penalty/rebate/right

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Unresolved substantively
Claim/example links
C044
Exact missing authority or term; next bounded action
Requires complete current federal/product/jurisdictional prepayment authority and published contractual terms.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-40 Saved research record

5 — Add-on/precomputed/Rule-of-78s transfer

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Excluded from computation; gateway preserved
Claim/example links
C019, C044
Exact missing authority or term; next bounded action
Separate current-law and contract packet; no mechanical use of E04 savings.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-41 Saved research record

6 — Operative clauses, exceptions, commentary

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered for relied-on propositions; Appendix J partial
Claim/example links
S001–S009; C056
Exact missing authority or term; next bounded action
Missing equation content identified rather than filled from memory or snippets.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-42 Saved research record

6 — Currentness, citation, adoption/version dates

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered with express limits
Claim/example links
C055; source table
Exact missing authority or term; next bounded action
Compilation lag and complete section-specific effective histories not fully closed; later targeted official amendment audit if required.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-43 Saved research record

6 — Withdrawn Guidance register

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered
Claim/example links
C054; S012
Exact missing authority or term; next bounded action
No circular/bulletin/advisory reliance requiring further withdrawal analysis.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-44 Saved research record

6 — Public contract/source limits

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered
Claim/example links
S013; C034–C035
Exact missing authority or term; next bounded action
Generic 2010 instruction supplies only its stated convention; no agreement or present provider-policy inference.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-45 Saved research record

6 — Prohibited records/actions

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Observed
Claim/example links
Session activity statement; read log
Exact missing authority or term; next bounded action
No owner-restricted records or actions undertaken; no next action required.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance
coverage-46 Saved research record

Delivery — Complete visible tables, self-check, remaining dimensions

Recorded check status: recorded; no individual primary acceptance inferred

Status and reason
Answered
Claim/example links
All tables; §§8–9
Exact missing authority or term; next bounded action
Self-check is not independent review; parent A004 and calculator/publication acceptance remain open.

Recorded coordinator check boundaries

coordinator acceptance
scoped_review_complete_with_limits_not_parent_or_actual_contract_acceptance

Corrections, review and scope

Read the evidence with its boundaries. These are saved research components, including revisions. A scoped coordinator review checks selected evidence; it does not certify every claim, a complete jurisdiction, current law or individual applicability. Dates and access limits remain attached to the records.

How to read the research →

No currently queued material correction is mapped to this component. This does not remove its currentness, access, jurisdiction or application limits.

Recorded review disposition

accepted with limits

Other components in this research series

Record integrity

Original saved Markdown SHA-256: ea7f2d4f0b7abf7faed039dca025f431c49148c151f7aecd9ccf7b88b1f49dda. Public formatting, private-reference removal and correction annotations are separate from that immutable original.

Get debt settlement help